
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Everyone Is Watching Royal Gold (RGLD) Today
Royal Gold (RGLD) continues to attract attention after posting annual revenue of US$1.54b and net income of US$737.96m, putting the precious metals royalty specialist firmly on investors’ watchlists.
Royal Gold’s share price has eased 0.7% over the last day and 3.8% over the past week. However, a 9.4% 1‑month share price return and 17.1% 90‑day gain sit alongside a 34.4% 1‑year total shareholder return and very strong 3‑ and 5‑year total shareholder returns, pointing to momentum that has been building rather than fading.
Compare Royal Gold’s momentum with other precious metals players by scanning our curated list of 35 elite gold producer stocks.
Bulls view Royal Gold’s recent double digit 3 month run as confirmation of a high quality royalty engine, while bears worry the price already reflects that. Which side does the current valuation support?
Most Popular Narrative: 18% Undervalued
On the most followed narrative, Royal Gold’s fair value of $305.67 sits above the last close of $252.28, which puts a clear spotlight on the growth and margin story that underpins that gap.
The strategic acquisitions of Sandstorm Gold and Horizon Copper will significantly diversify Royal Gold's asset base, reducing single-asset risk and increasing exposure to long-term growth projects, which should drive more stable and growing revenue streams and improve net margins.
Read the complete narrative. Read the complete narrative.
Want to understand why this framework supports a higher value for Royal Gold? The narrative leans on rising earnings, fatter margins and a richer future profit multiple. Curious which revenue path and profitability mix have been baked into that story? The full narrative lays out the exact assumptions the model is using.
Result: Fair Value of $305.67 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the narrative can unravel if Royal Gold’s heavy reliance on gold, combined with any prolonged production setbacks at key partner mines, feeds through to softer royalty inflows.
Find out about the key risks to this Royal Gold narrative.
Another View on Royal Gold’s Valuation
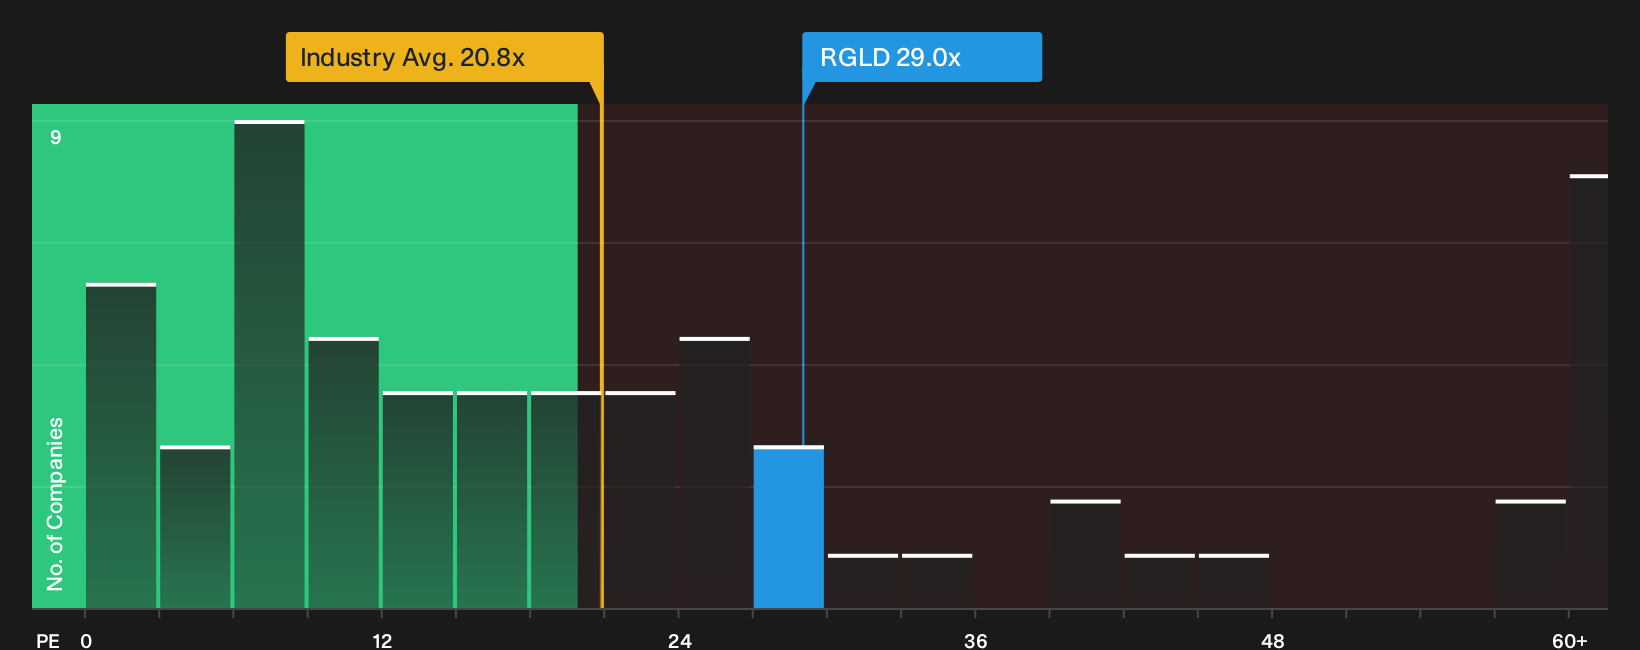
The story looks very different when the focus shifts from fair value models to what investors are actually paying today. Royal Gold trades on a P/E of 29x while US Metals and Mining peers average 20.8x, and its own fair ratio sits lower again at 25.1x.
That combination points to investors already paying a meaningful premium for Royal Gold versus both the sector and its fair ratio, which compresses the margin for error if growth or returns undershoot expectations. The key question is whether that higher P/E reflects durable quality or simply optimism that could cool quickly.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Royal Gold’s outlook so far. Review the data carefully, move quickly, and shape your own take on the 3 key rewards and 1 important warning sign.
Hunting For More Ideas Beyond Royal Gold?
Do not stop with one ticker. Broaden your watchlist with fresh opportunities that match your priorities on value, resilience and income using the Simply Wall Street Screener.
- Target stronger upside potential by scanning a curated pool of 32 high quality undervalued stocks that combine quality financials with prices that lag underlying fundamentals.
- Fortify your portfolio with companies that aim for staying power, using our filter of 11 resilient stocks with low risk scores designed to prioritise resilient balance sheets and business models.
- Strengthen your income stream by reviewing a focused set of 6 dividend fortresses built around higher yields and an assessment of payout stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com