
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ExlService Holdings (EXLS) Launches Go Beyond Brand, Is The AI Story Already Priced In?
ExlService Holdings (EXLS) has marked its 20th year as a public company with a fresh “Go Beyond” brand launch, tying its identity closely to data, AI and execution-led services.
The new Go Beyond identity arrives after a busy stretch for ExlService Holdings, including the August 2026 iMerit acquisition, a presentation at Citi’s Global TMT Conference, and a recent 1-day share price return of 1.85%. This comes despite the share price falling 14.44% year to date and a 1-year total shareholder return decline of 19.11%. These metrics are set against 3-year and 5-year total shareholder returns of 21.21% and 44.56%, which point to longer term momentum built over several years rather than in recent months.
Scan beyond ExlService Holdings and compare its AI and data-led positioning with a hand-picked set of 74 profitable AI stocks that aren't just burning cash.
ExlService Holdings now pairs a refreshed, AI-heavy narrative with a share price that has retreated over the past year. Investors may be weighing whether that combination supports taking a position today or waiting for a potentially lower entry point if expectations adjust further.
Most Popular Narrative: 91.6% Overvalued
ExlService Holdings closed at $35.26, while the leading narrative pegs fair value near $18.40, which puts the focus squarely on how that gap is justified.
Offshore analytics and managed-operations provider that runs mission-critical claims, underwriting, payment-integrity and finance workflows for large insurers, healthcare payers and banks, and is repositioning that base into data and AI-led delivery. Roughly 53% of revenue is recurring, embedded operations protected by 12 to 30 months of transition friction, which is enough to make permanent capital loss unlikely at a low entry price. It is not enough to underwrite compounding, five years of mix shift into AI-led work has produced no gross margin expansion, contracts are terminable without cause, and the AI work is re-won through pilots rather than inherited. The thesis is therefore a price thesis, not a quality thesis
Want to see why this narrative calls ExlService Holdings a price thesis rather than a quality story. The revenue mix, contract structure and margin profile hide a key assumption about how much earnings power needs to be repriced before that $18.40 fair value starts to look sensible.
Result: Fair Value of $18.40 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, ExlService Holdings carries some potential spoilers for that price-led thesis, including heavy reliance on a concentrated client base and contracts that can be terminated without cause.
Find out about the key risks to this ExlService Holdings narrative.
Another View On ExlService Holdings’ Valuation
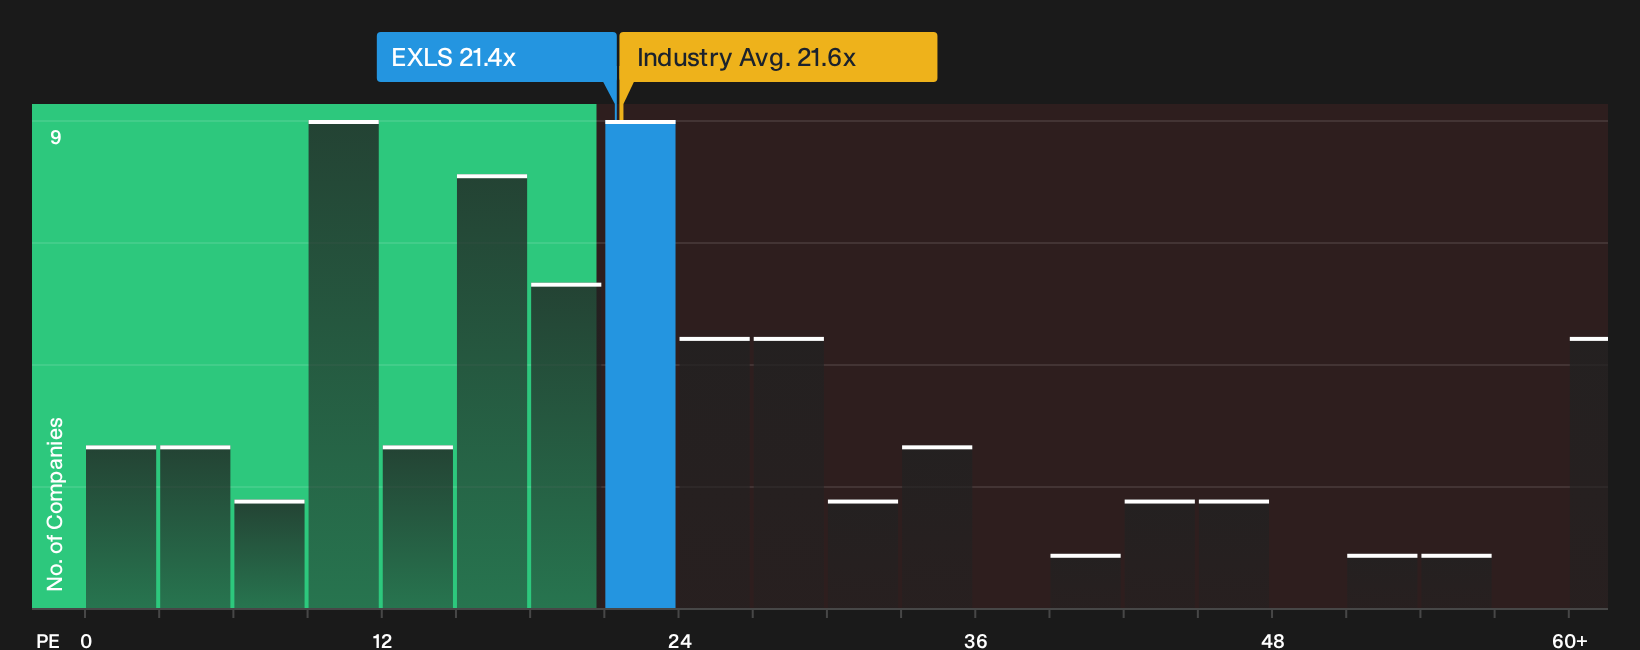
The narrative fair value of $18.40 paints ExlService Holdings as heavily overvalued, yet the market’s own yardstick tells a different story. At a P/E of 21.4x, the stock sits almost on top of its 21.5x fair ratio and very close to the US Professional Services average of 21.6x, even though it looks expensive versus peers at 14.2x. That mix of near fair value on broad metrics and a premium to direct rivals leaves a simple question: Is the real risk in the price, or in assuming the peer discount is justified?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Reading through these mixed signals on ExlService Holdings, it can be hard to know which datapoint to trust most. Move quickly, test the numbers yourself and pressure test the bullish angles before they get fully priced in. To see what the optimism is built on, start with the 4 key rewards.
Looking for more investment ideas beyond ExlService Holdings?
If you want a fuller watchlist around ExlService Holdings, use the Simply Wall Street Screener to surface fresh ideas that fit different styles and risk levels.
- Target potential bargains with resilient earnings by scanning a curated 32 high quality undervalued stocks that already combine quality fundamentals with attractive pricing.
- Prioritize staying power in tougher markets by reviewing a list of solid balance sheet and fundamentals (23 results) that can help anchor your portfolio.
- Hunt for less crowded opportunities by filtering a 15 high quality undiscovered gems that many investors may not be watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com