
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Alnylam Pharmaceuticals (ALNY) Gains Attention After Fresh RNAi Data, Is It 33% Undervalued?
Alnylam Pharmaceuticals (ALNY) is back in focus after fresh RNA interference data at the European Society of Cardiology Congress 2026, paired with an upcoming appearance at the Wells Fargo Annual Healthcare Conference.
At a share price of $248.68, Alnylam Pharmaceuticals has seen a 30-day share price return of 8.76%, even as the year-to-date share price return has fallen 37.86%. The 3-year total shareholder return of 34.43% points to longer term momentum that recent news could help rebuild.
Compare Alnylam Pharmaceuticals with other RNA and biotech players that may be set up for their own data driven moves using the hand picked 15 high quality undiscovered gems.
Alnylam Pharmaceuticals now pairs a broad RNAi franchise with a share price that has bounced in the past month but remains weaker over the year. Is that combination being valued generously or conservatively today?
Most Popular Narrative: 33% Undervalued
Analysts following Alnylam Pharmaceuticals see fair value at $371.35 compared with the recent $248.68 share price, framing a sizeable valuation gap driven by ATTR and RNAi assumptions.
The analysts have a consensus price target of $371.35 for Alnylam Pharmaceuticals based on their expectations of its future earnings growth, profit margins and other risk factors.
In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $8.8 billion, earnings will come to $1.8 billion, and it would be trading on a PE ratio of 35.7x, assuming you use a discount rate of 7.6%.
Curious what has to happen between now and 2029 for that kind of earnings, margin profile, and valuation multiple to line up for Alnylam Pharmaceuticals? The narrative leans heavily on ATTR momentum, a wider RNAi portfolio, and a richer profitability mix than today, all filtered through that single discount rate assumption.
Result: Fair Value of $371.35 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the bullish Alnylam Pharmaceuticals story can flip fast if Amvuttra uptake stalls further or if upcoming ATTR and nucresiran data land poorly.
Find out about the key risks to this Alnylam Pharmaceuticals narrative.
Another View on Alnylam Pharmaceuticals Valuation
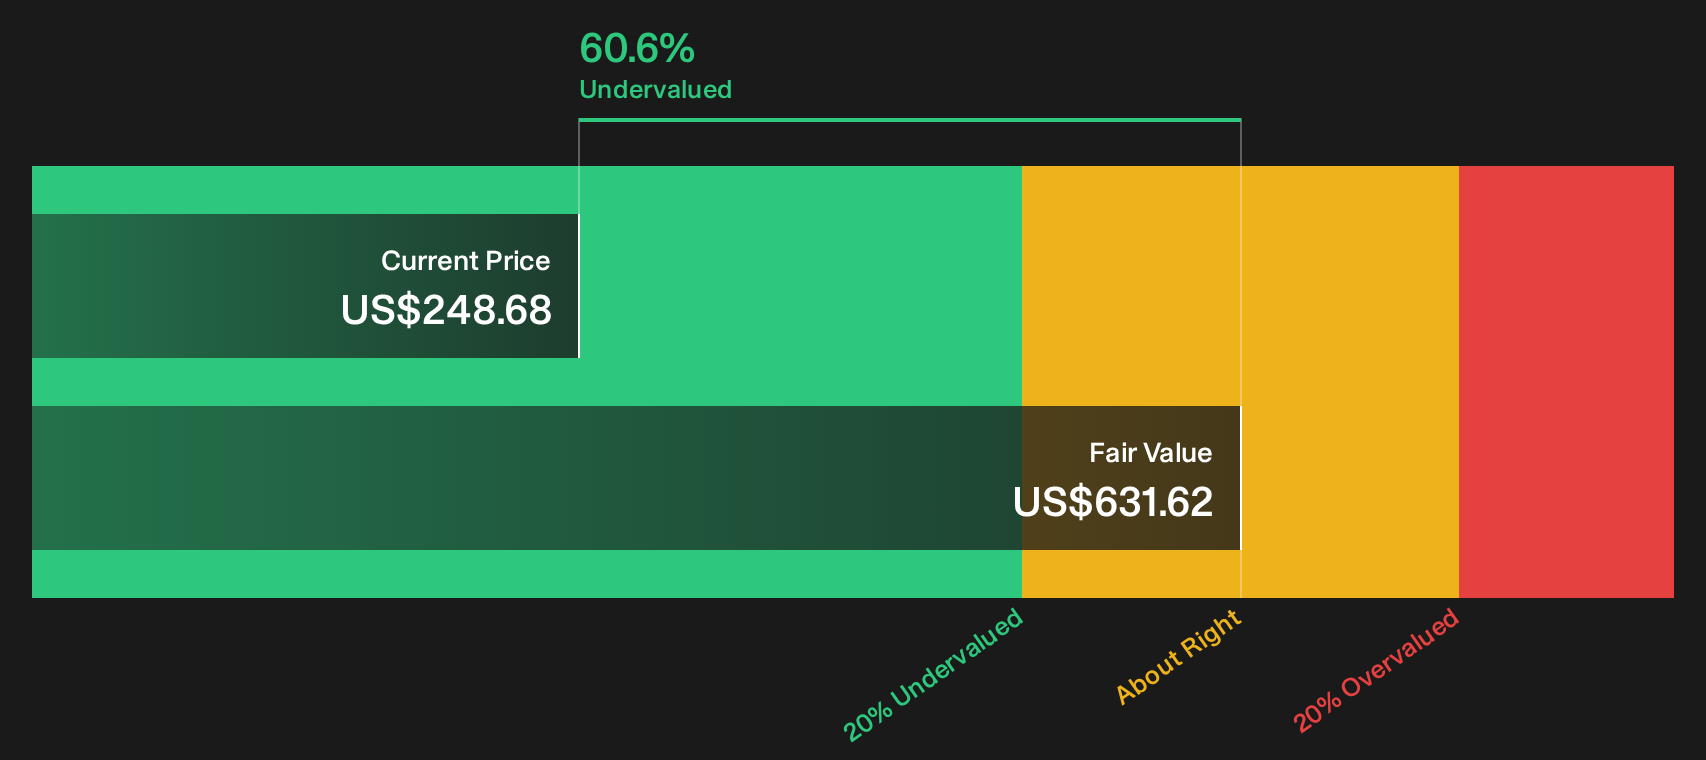
Analyst targets and the Simply Wall St DCF model do not line up neatly. While the consensus fair value sits at $371.35, our DCF estimate for Alnylam Pharmaceuticals is $631.62, which flags the stock as materially undervalued on future cash flows. Which yardstick do you trust more for such a complex RNAi story?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Alnylam Pharmaceuticals is split. If you think this story is moving quickly, now is the time to test the numbers and pressure check the upside case by reviewing the 3 key rewards.
Looking for more Alnylam Pharmaceuticals sized ideas?
If you like the setup around Alnylam Pharmaceuticals but do nothing else, you could miss companies quietly lining up their own inflection points right now.
- Chase potential mispricings by scanning a curated pool of candidates through the 32 high quality undervalued stocks.
- Prioritize resilience first and hunt for businesses with sturdier finances using the list of solid balance sheet and fundamentals (23 results).
- Target stability plus income by zeroing in on companies offering meaningful payouts through the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com