
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Kinsale Capital Group (KNSL) Rebound Tests Valuation As E&S Growth Story Stays In Focus
Kinsale Capital Group (KNSL) has drawn fresh attention after recent trading left the shares around US$360.01, with short term returns under pressure while the past 3 months show a double digit gain.
Viewed over a longer stretch, Kinsale Capital Group’s recent pullback tells a mixed story. The share price has eased over the past week and month, yet the 90 day share price return of 15.45% and 5 year total shareholder return of 123.62% point to earlier momentum that has cooled in the past year as total shareholder return declined 16.39%.
Compare Kinsale Capital Group’s recent pullback with other financially robust insurers by scanning our hand picked list of solid balance sheet and fundamentals (23 results) for potential alternatives and complements.
Kinsale Capital Group’s sharp 90 day rebound, set against weaker 1 year and 3 year returns, raises a simple issue: Is the meaningful upside still ahead, or has the stock already used up most of its rerating?
Most Popular Narrative: 2% Overvalued
Kinsale Capital Group’s latest close at $360.01 sits slightly above a narrative fair value of about $354.67, so the story now hinges on what assumptions justify that gap.
The secular shift of risks from standard markets into the E&S channel, particularly for homeowners and catastrophe-exposed lines (e.g., in California, Texas, and coastal regions), is broadening Kinsale's long-term premium base and enabling sustainable top-line growth even as competition intensifies in select lines.
Want to see what that premium shift means for Kinsale Capital Group’s top line, margins, and future earnings multiple? The full narrative spells out the exact growth mix, profitability path, and valuation bridge that support this fair value estimate.
Result: Fair Value of $354.67 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the narrative for Kinsale Capital Group can be knocked off course if competition keeps pressuring premiums or if catastrophe exposed homeowners business delivers outsized losses.
Find out about the key risks to this Kinsale Capital Group narrative.
Another View On Kinsale Capital Group’s Value
The narrative fair value places Kinsale Capital Group around $354.67 and describes the stock as slightly overvalued. Our DCF model presents a different perspective. Based on those cash flow assumptions, KNSL appears materially undervalued with an estimated value of $562.41 per share. Which lens do you trust more when cash flows and earnings multiples diverge?
Look into how the SWS DCF model arrives at its fair value.
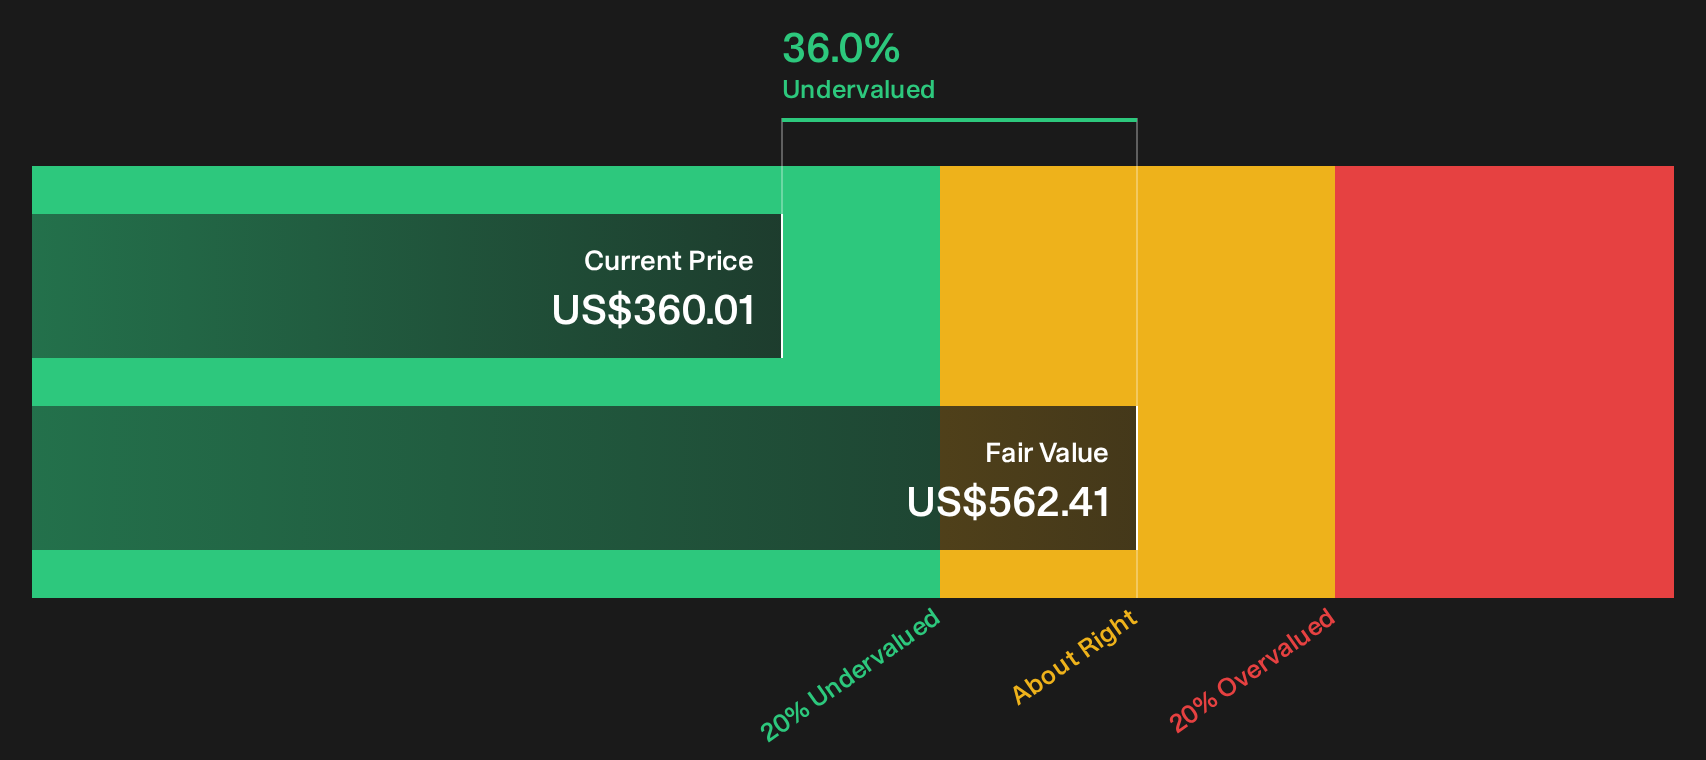
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kinsale Capital Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Kinsale Capital Group often create useful moments for fresh research. Move quickly, review the underlying numbers, and weigh the 2 key rewards and 1 important warning sign.
Looking for more Kinsale Capital Group sized ideas?
If you stop with Kinsale Capital Group, you risk missing companies that better fit your goals, risk tolerance, or income needs across different market conditions.
- Target potential mispricing by scanning our focused list of 32 high quality undervalued stocks that pair strong fundamentals with prices that may not fully reflect their underlying strength.
- Strengthen income potential by reviewing a curated set of 6 dividend fortresses that aim to combine higher yields with resilient business models.
- Dial down portfolio stress by filtering for 11 resilient stocks with low risk scores designed for investors who prioritise steadier balance sheets and lower volatility profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com