
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
TD SYNNEX (SNX) Stock May Be 7% Undervalued On Cash Flow
TD SYNNEX stock has had a strong three year run, yet the valuation checks now suggest something more muted, with the Discounted Cash Flow (DCF) intrinsic value estimate pointing to a share price that is close to where the market is trading.
- Over the past three years, TD SYNNEX has returned 177.4%, which puts fresh attention on whether recent gains are already pricing in much of the good news.
- The company’s role as a large scale IT distributor can support cash flow generation, while thin industry margins and execution missteps on costs may pressure that cash conversion and weigh on what investors are willing to pay.
- The broader checks form a mixed picture rather than a clear bargain or clear overvaluation, with a value score of 4 and market multiples that still screen TD SYNNEX as undervalued.
The issue now is whether TD SYNNEX at around US$269 already reflects a fair estimate of its intrinsic value or still leaves room for mispricing.
Capitalize on TD SYNNEX’s strong three year run by comparing it with 32 high quality undervalued stocks that still screen as potentially mispriced on cash flows and balance sheet strength.Is TD SYNNEX Fairly Priced on Cash Flow?
The Discounted Cash Flow (DCF) model here projects what TD SYNNEX’s future cash generation could be worth in today’s dollars. The latest twelve month free cash flow sits at about $358 million, and the model assumes those cash flows continue growing rather than shrinking, using a two stage forecast that tapers to steadier growth over time.
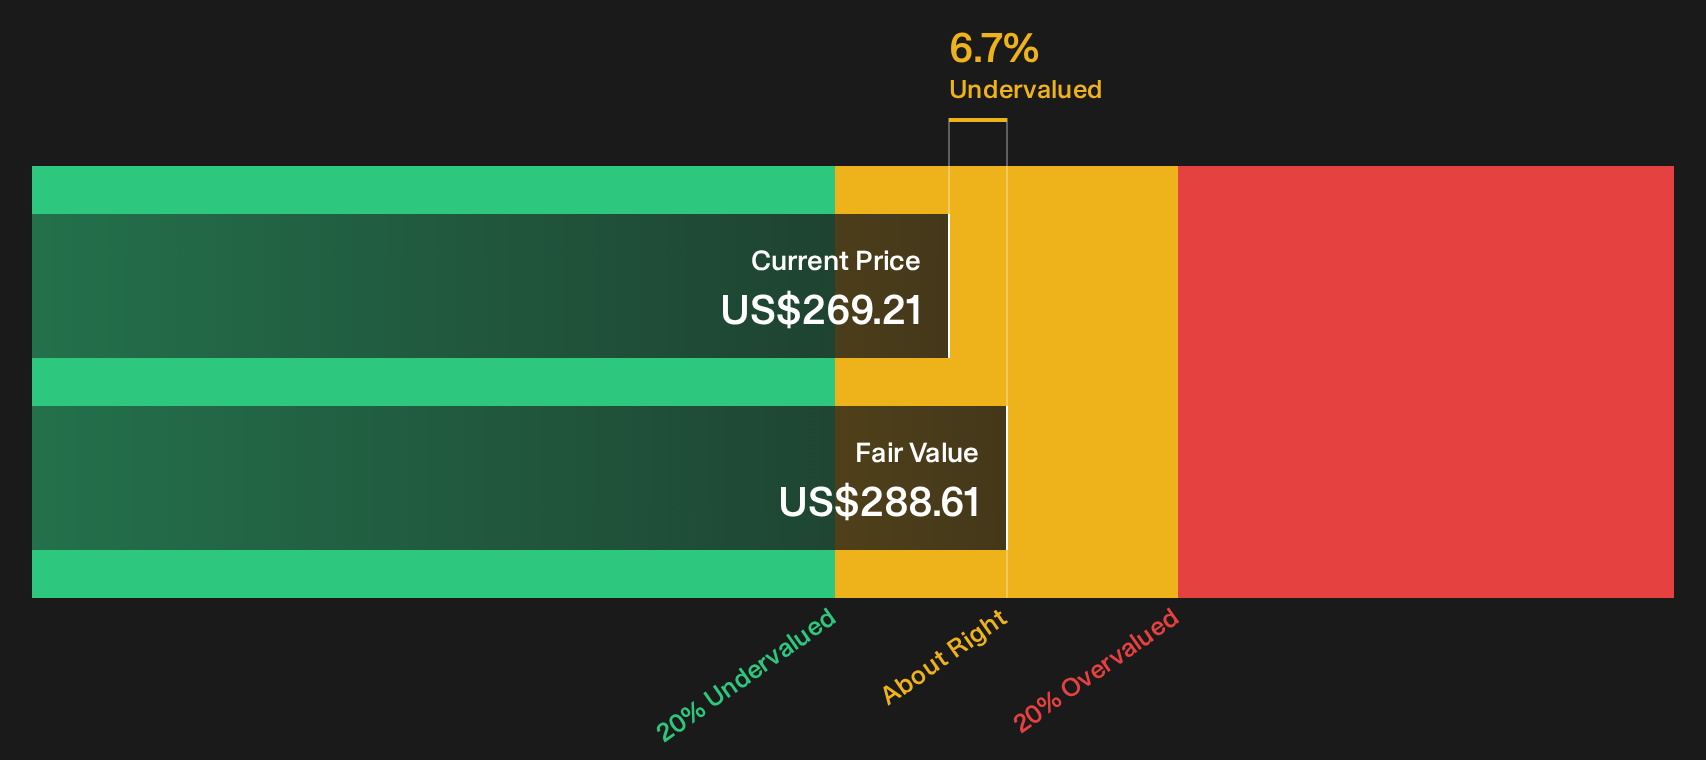
On those assumptions, the DCF points to an intrinsic value of about $289 per share, compared with the recent price around $269. That gap implies the stock trades at roughly a 6.7% discount to the model’s estimate, even after a strong multi year share price run. The implied upside is not huge, but the output suggests TD SYNNEX is priced close to what its projected cash flows support rather than at an extreme bargain or bubble level.
On this set of cash flow projections, TD SYNNEX appears roughly fairly valued relative to its DCF based intrinsic value estimate.
TD SYNNEX is fairly valued according to our Discounted Cash Flow (DCF), but this can change at a moment's notice. Track the value in your watchlist or portfolio and be alerted on when to act.
Is TD SYNNEX a Bargain on Earnings?
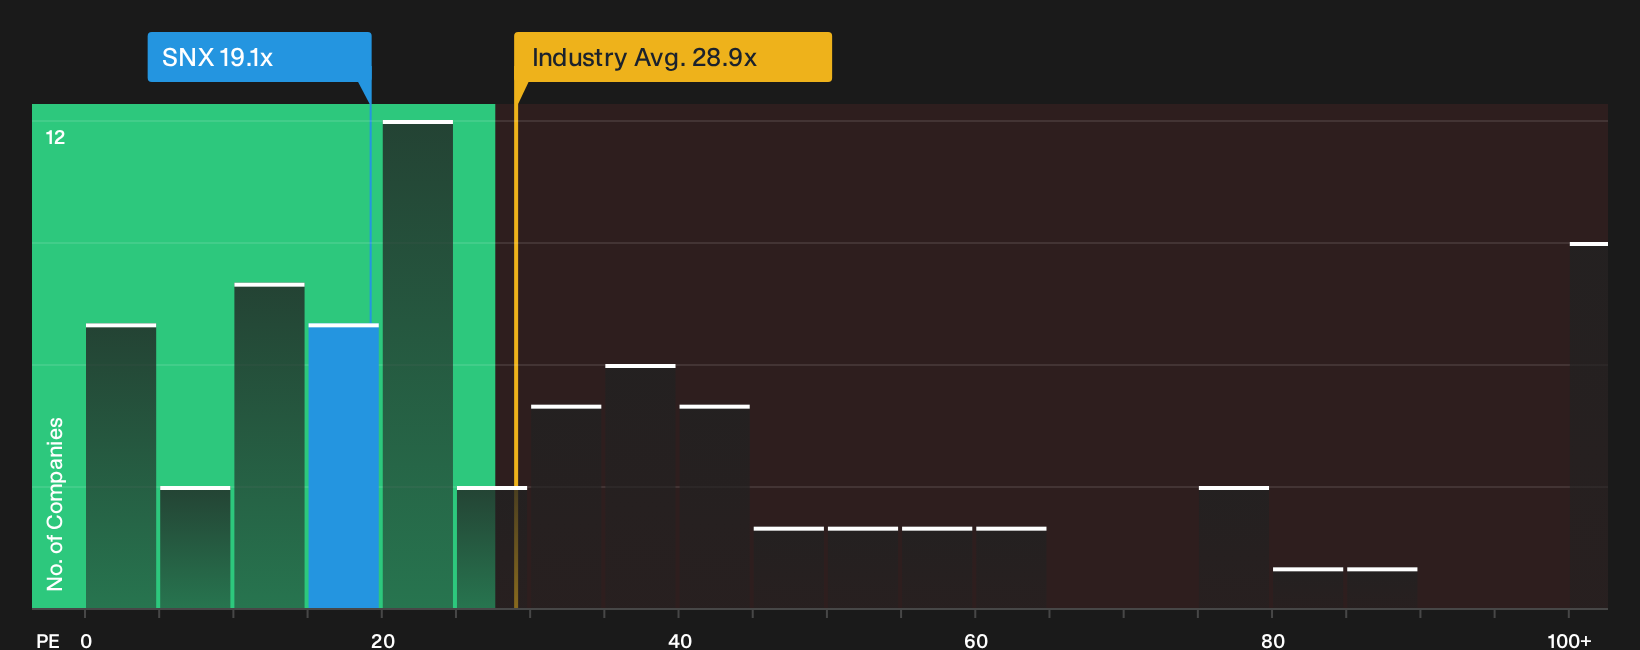
P/E is a useful lens for TD SYNNEX because earnings sit at the center of how investors usually value large distributors with relatively steady profit bases. At the current share price, the stock trades on a P/E of about 19.1x, which is slightly above the peer average of 17.8x but below the broader electronic industry average near 28.9x. That already places TD SYNNEX in a middle zone, not priced like a high flying growth story and not treated as a deep value play either.
The more tailored fair P/E ratio for TD SYNNEX is 26.6x, which factors in its sector, scale and risk profile. Against that benchmark, the current 19.1x multiple sits meaningfully lower. This indicates the market is assigning a discount relative to what the model suggests investors might be willing to pay for these earnings. If you are comparing potential ideas, this gap is worth noting alongside the DCF work and balance sheet checks.
On this earnings multiple, TD SYNNEX stock appears undervalued relative to the fair P/E level implied by the model.
See what the numbers say about this price — find out in our valuation breakdown.
The TD SYNNEX Narrative: What Would Justify Today's Price?
Narratives for TD SYNNEX pick up where this valuation puzzle leaves off by spelling out the specific assumptions on growth, margins and earnings that would need to hold for the stock to be worth materially more or less than today’s price. They sit on Simply Wall St’s Community page so you can see how each one frames fair value as a thesis about TD SYNNEX’s business that can be revisited over time rather than a one off snapshot.
One of the top community narratives on TD SYNNEX: 19% undervalued
"Ongoing data center build-outs and the proliferation of hybrid/cloud IT infrastructure, as evidenced by high growth in the Advanced Solutions and Hyve businesses, are increasing demand for complex integration and lifecycle services..."
Read one of the top narratives on TD SYNNEX
Do you think there's more to the story for TD SYNNEX? Head over to our Community to see what others are saying!
The Bottom Line
The Discounted Cash Flow (DCF) work suggests TD SYNNEX is trading close to its intrinsic value, with only a modest discount implied by the model. Market multiples point to an undervalued stock on earnings, which hints that sentiment toward the distributor is still cautious. That split leaves the real hinge on whether TD SYNNEX can sustain cash conversion while managing the thin margin structure of large scale IT distribution. The key question from here is whether the current discount on the P/E is compensation for execution risk on costs or an opportunity if the business continues to turn revenue into dependable free cash flow.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com