
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
RTX (RTX) Could Be 15% Undervalued On Its Backlog Driven Growth Narrative
RTX’s New Laser Alliance With Xcimer
RTX (RTX) has taken a minority stake in Xcimer Energy and entered a teaming agreement that links pulsed laser technology with the contractor’s defense systems for potential future directed energy applications.
RTX’s share price has eased over the past month, with a 30-day share price return of -11.34%, even as the 90-day share price return of 7.65% and 1-year total shareholder return of 28.72% reflect momentum that has built over a longer stretch. Recent facility expansion for radar and electronic warfare systems and the fresh Xcimer partnership sit within that backdrop, alongside multiyear total shareholder returns above 160% that keep attention on how growth projects and perceived risk are being priced in.
Spot future defense and aerospace breakouts by scanning the hand-picked 39 power grid technology and infrastructure stocks.RTX now trades at US$197.68, below both its analyst target and intrinsic value estimate, after a sharp 30 day pullback. Does that gap signal mispricing, or a fair penalty for execution and risk?
Most Popular Narrative: 14.9% Undervalued
RTX’s widely followed valuation narrative places fair value at $232.27, above the last close of $197.68. This frames the recent pullback as a potential discount to that storyline.
Robust and growing backlog, highlighted by a 1.86 quarter book-to-bill ratio, $236 billion backlog (up 15% year-over-year), and major new international contracts (e.g., EU, MENA, Asia-Pacific) indicate RTX is well-positioned to benefit from sustained increases in global defense spending and heightened geopolitical tensions, setting up strong visibility for future revenue growth.
Read the complete narrative. Read the complete narrative.
Want to see what sits behind that backlog driven valuation call? The narrative leans on steady top line expansion, firmer margins, and a rich future earnings multiple. Curious which revenue path and profitability mix support that fair value gap.
Result: Fair Value of $232.27 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, RTX carries real pressure points, especially if jet engine reliability issues or shifts in defense budgets begin to chip away at that backlog story.
Find out about the key risks to this RTX narrative.
Another View: RTX Through The P/E Lens
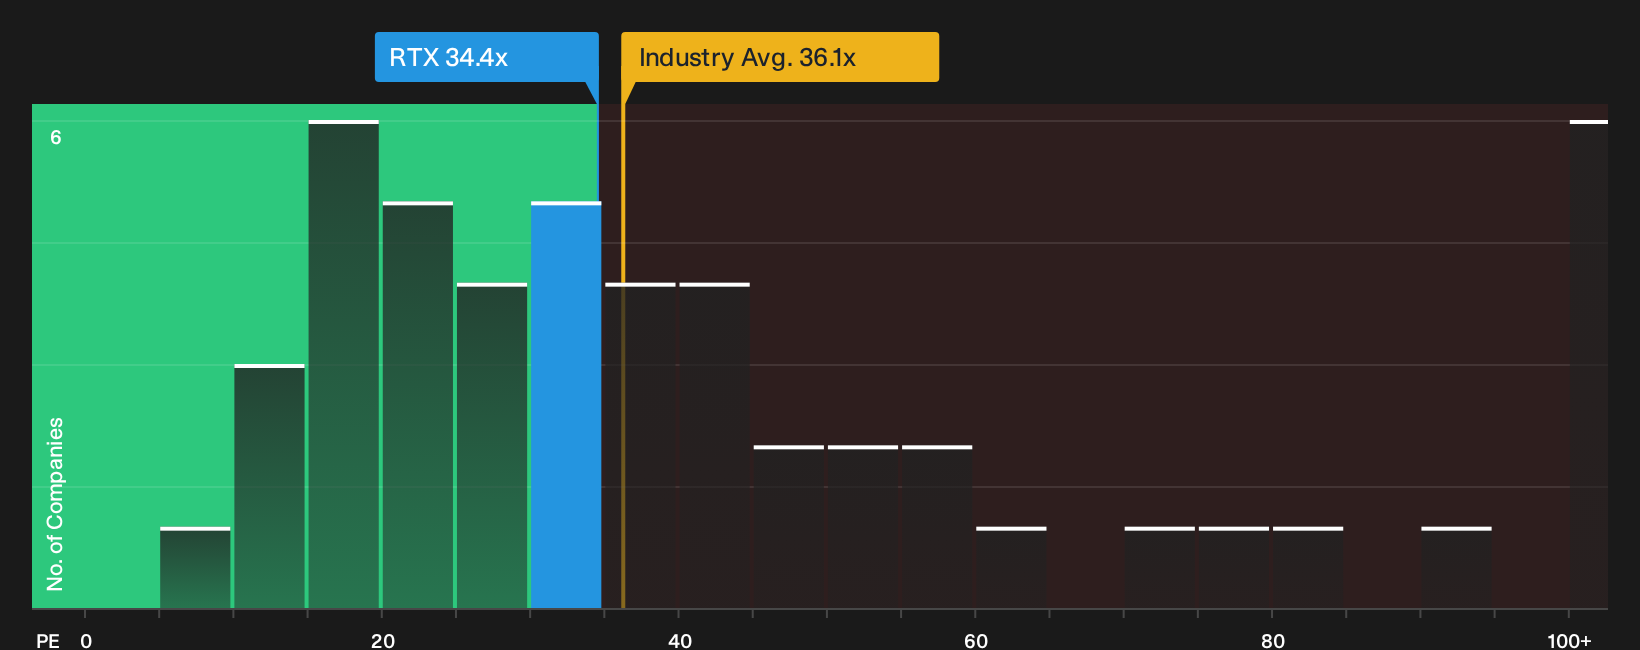
There is a wrinkle in the RTX story when shifting from fair value estimates to simple P/E math. The stock trades on a 34.4x P/E, slightly above its own fair ratio of 32.7x, which hints at some valuation risk if sentiment cools and that gap closes.
Set against peers, RTX looks different again. The same 34.4x multiple sits below the US Aerospace & Defense industry average of 36.1x and under the 39.4x peer group level. Investors are effectively paying less per dollar of earnings than for many rivals, even if the fair ratio suggests a touch of stretch on company specific terms.
For anyone weighing that mix of relative value and fair ratio premium, the real question is whether RTX earns the right to keep trading on this richer earnings tag or if the share price eventually drifts closer to the fair ratio that the market could move towards.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on RTX so far. If you want to move quickly and form your own take, start with the 3 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond RTX?
If RTX has you thinking harder about valuation, do not stop there. A few focused screeners can surface other opportunities that fit your style quickly.
- Target resilient payouts and potential income strength by scanning 6 dividend fortresses, which could help anchor your portfolio when markets get choppy.
- Hunt for quality at a discount and compare your RTX view with a wider field by running the 32 high quality undervalued stocks before prices move away from you.
- Prioritise financial robustness and aim to sleep better at night by checking the list of solid balance sheet and fundamentals (23 results) so you are not the last to notice weak fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com