
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To American Tower (AMT) $1.6 Billion Debt Refinance
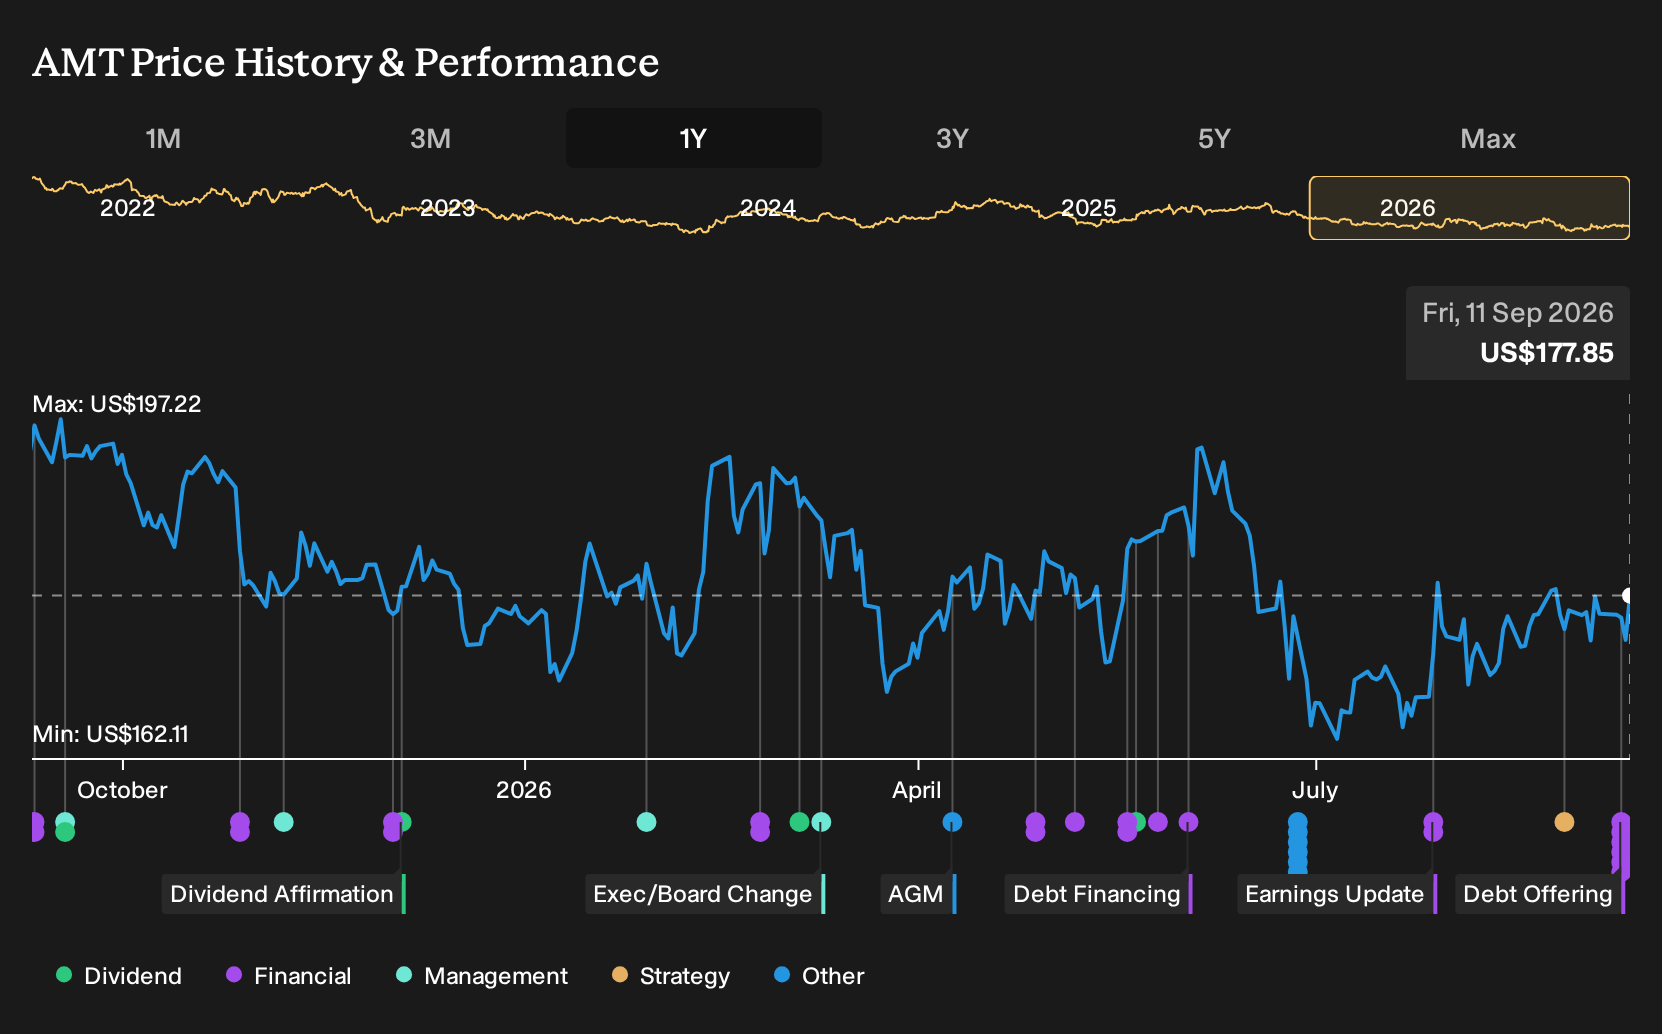
- American Tower completed a US$1.6b offering of senior unsecured fixed rate notes maturing in 2031, 2033 and 2036, with coupons between 5.30% and 5.75% and small original issue discounts near par.
- The refinancing, focused on retiring 2026 notes and repaying its multicurrency revolving credit facility, reshapes American Tower’s interest cost profile and keeps liquidity available for tower and data center investment.
- We will look at how American Tower’s investment narrative is shaped by this large refinancing that extends the debt maturity profile.
Scan how American Tower’s refinancing compares with peers by reviewing hand picked infrastructure and real estate operators in the 11 resilient stocks with low risk scores that emphasize balance sheet resilience and measured risk taking.
American Tower Investment Narrative Recap
To own American Tower, you need to be comfortable with a slow and steady story. The core belief is that rising mobile data use and denser 5G networks can support ongoing lease amendments on towers and growing demand at CoreSite’s data centers. The recent US$1.6b refinancing looks more like housekeeping than a shift in that thesis.
The near term swing factor is still carrier spending translating into actual colocations and amendments on existing sites, while the biggest risk remains funding costs and refinancing drag on AFFO per share. Extending maturities and preserving revolving credit capacity helps manage that risk but does not remove it.
The key development is American Tower’s registered public offering of senior unsecured notes maturing in 2031, 2033 and 2036. Around US$1.58b of net proceeds are earmarked to retire US$600m of notes due 2026 and repay borrowings on the US$6b multicurrency revolver, with the remainder available for general corporate purposes.
For you as a shareholder, that matters because the catalyst is still incremental tower leasing and data center utilization rather than financial engineering. The refinancing extends the debt ladder and preserves liquidity that can be directed to U.S. and other developed markets. The main execution watchpoints remain interest expense, churn events and how quickly CoreSite’s capacity is leased.
What The New Debt Means Against American Tower’s Forecasts
American Tower's narrative points to revenues of US$12.5b and earnings of US$3.8b by 2029, based on analyst estimates. That profile assumes revenue expands by 4.4% per year and earnings rise by about US$0.4b from US$3.4b today, with that step up in profit tied to 2029 forecasts.
Uncover how American Tower's fair value indicates a 21% potential upside to its current price before the discount to the market closes.
Exploring Other Perspectives
Fair value estimates for American Tower from three private investors in the Simply Wall St Community span roughly US$216 to US$295 per share, so you are seeing a wide spread rather than a tight cluster. In comparison, refinancing at coupons between 5.30% and 5.75% makes interest costs a key swing factor for how those different narratives play out.
Explore 2 other American Tower fair value estimates, including one that suggests it could be worth just $215.70!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your American Tower research is our analysis highlighting 6 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for American Tower. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Tower's overall financial health at a glance.
Looking For More Investment Ideas Beyond American Tower?
Once you have formed a view on American Tower, it helps to set it against a wider opportunity set so you can decide where it really deserves space in your portfolio.
- If you want to focus on potential mispricing, scan our broader universe of quality opportunities through the 32 high quality undervalued stocks that already filters for fundamentals.
- For investors who care most about steady income, line up American Tower against high yielding payers by reviewing the 6 dividend fortresses curated for durability.
- When capital protection is your first priority, compare this stock with companies screened for robust finances in the list of solid balance sheet and fundamentals (23 results) and see which balance sheets you trust most.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com