
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Newmark Group (NMRK) Could Be 26% Undervalued Following Its Manhattan Lease Win
Newmark Group (NMRK) moved into focus after announcing it represented Havas Health in a 254,118-square-foot headquarters expansion and long-term lease extension at 200 Madison Avenue in Midtown Manhattan.
Set against this leasing win, Newmark Group’s recent price action has been mixed, with the share price down 15.03% year to date and the 1-year total shareholder return declining 24.33%. By contrast, the 3-year total shareholder return sits at roughly 2.2x the starting level, pointing to longer term momentum that contrasts with softer recent trading.
Scan how Newmark Group compares with other commercial real estate specialists by reviewing our curated list of list of solid balance sheet and fundamentals (23 results)
Newmark Group trades at a steep discount to both analyst targets and an estimated intrinsic value, even after this leasing headline. Is that a pricing error, or is the market applying deserved caution to a complex real estate cycle?
Most Popular Narrative: 26.4% Undervalued
Newmark Group's most followed valuation story pegs fair value at $19.58 per share, well above the recent $14.42 close. This puts that Midtown lease win into a wider context for investors weighing the stock.
Accelerated expansion in alternative asset classes such as data centers, supported by robust demand stemming from AI and digital infrastructure, is driving above-industry revenue growth and higher-margin capital markets activities, positioning Newmark for long-term top-line and earnings expansion.
It is worth asking what kind of revenue ramp, margin profile, and future earnings multiple are built into that $19.58 figure. The narrative leans heavily on compounding earnings power and a richer mix of fee income. The full set of assumptions shows how far Newmark Group may need to push both profitability and scale to close that valuation gap.
Result: Fair Value of $19.58 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Newmark Group’s push into newer regions and data center heavy sectors could backfire if integration drags or if activity in those hot pockets cools faster than expected.
Find out about the key risks to this Newmark Group narrative.
Another Look At Newmark Group’s Price Tag
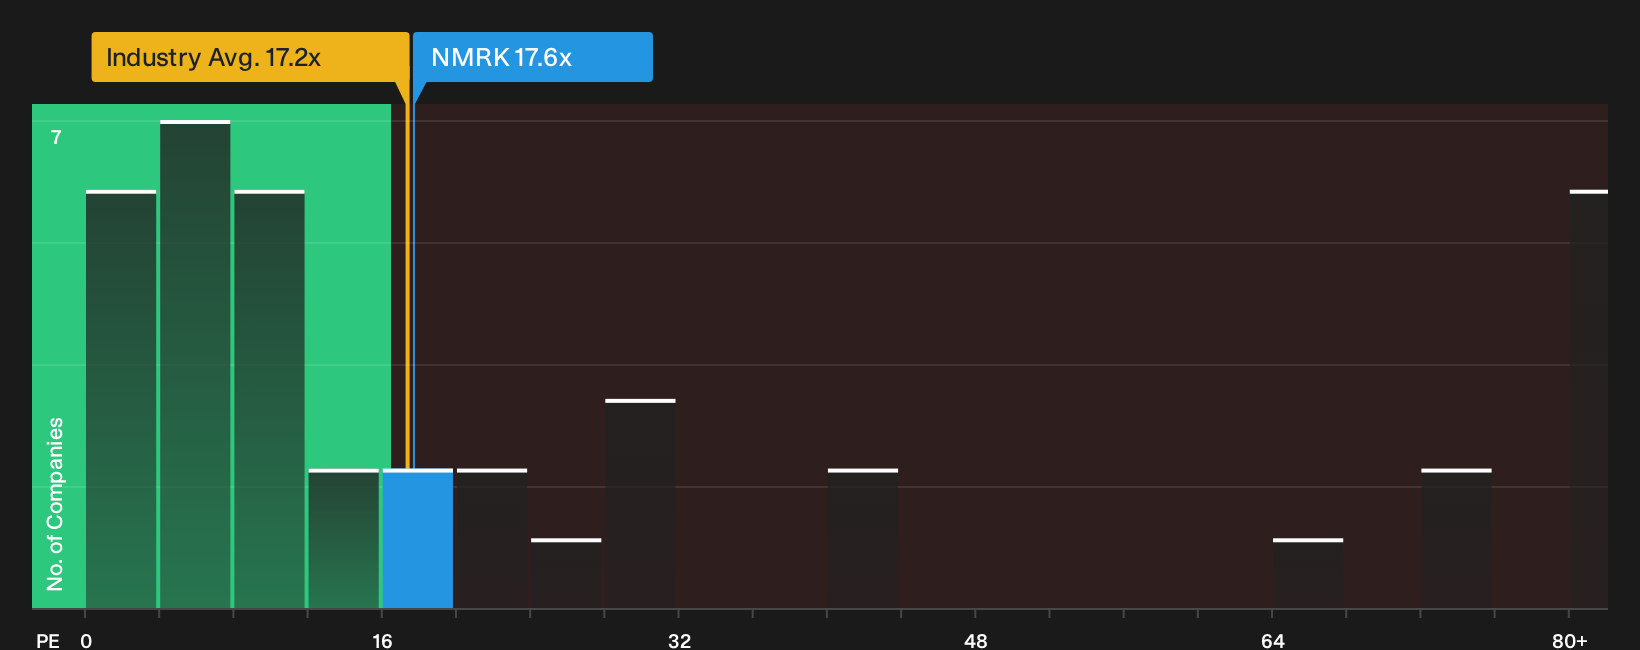
The first story leans on future earnings power. A second check uses today’s P/E. Newmark Group trades on 17.6x earnings, slightly richer than the US Real Estate sector at 16.4x, but below a fair ratio of 26.8x. Is that a margin of safety, or a warning that expectations are already full?
For investors comparing these signals, the numbers leave room for debate. The full valuation breakdown helps show where the pressure points really sit. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Newmark Group is mixed, with clear risks on one side and potential rewards on the other. Check the numbers, pressure test the narratives, and then weigh the 4 key rewards and 2 important warning signs.
Looking for more Newmark Group sized investment ideas?
If you want to keep sharpening your edge beyond Newmark Group, use the Simply Wall Street Screener to uncover fresh stock ideas before they get crowded.
- Target opportunity rich value setups by scanning companies trading below what their fundamentals might justify through the 32 high quality undervalued stocks.
- Prioritise sleep at night holdings by focusing on businesses with healthier finances and robust metrics using the 11 resilient stocks with low risk scores.
- Get ahead of the crowd by searching for quality businesses that the market has not fully focused on yet via the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com