
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Construction Slowdown Could Be A Key Test For Martin Marietta Stock (MLM)
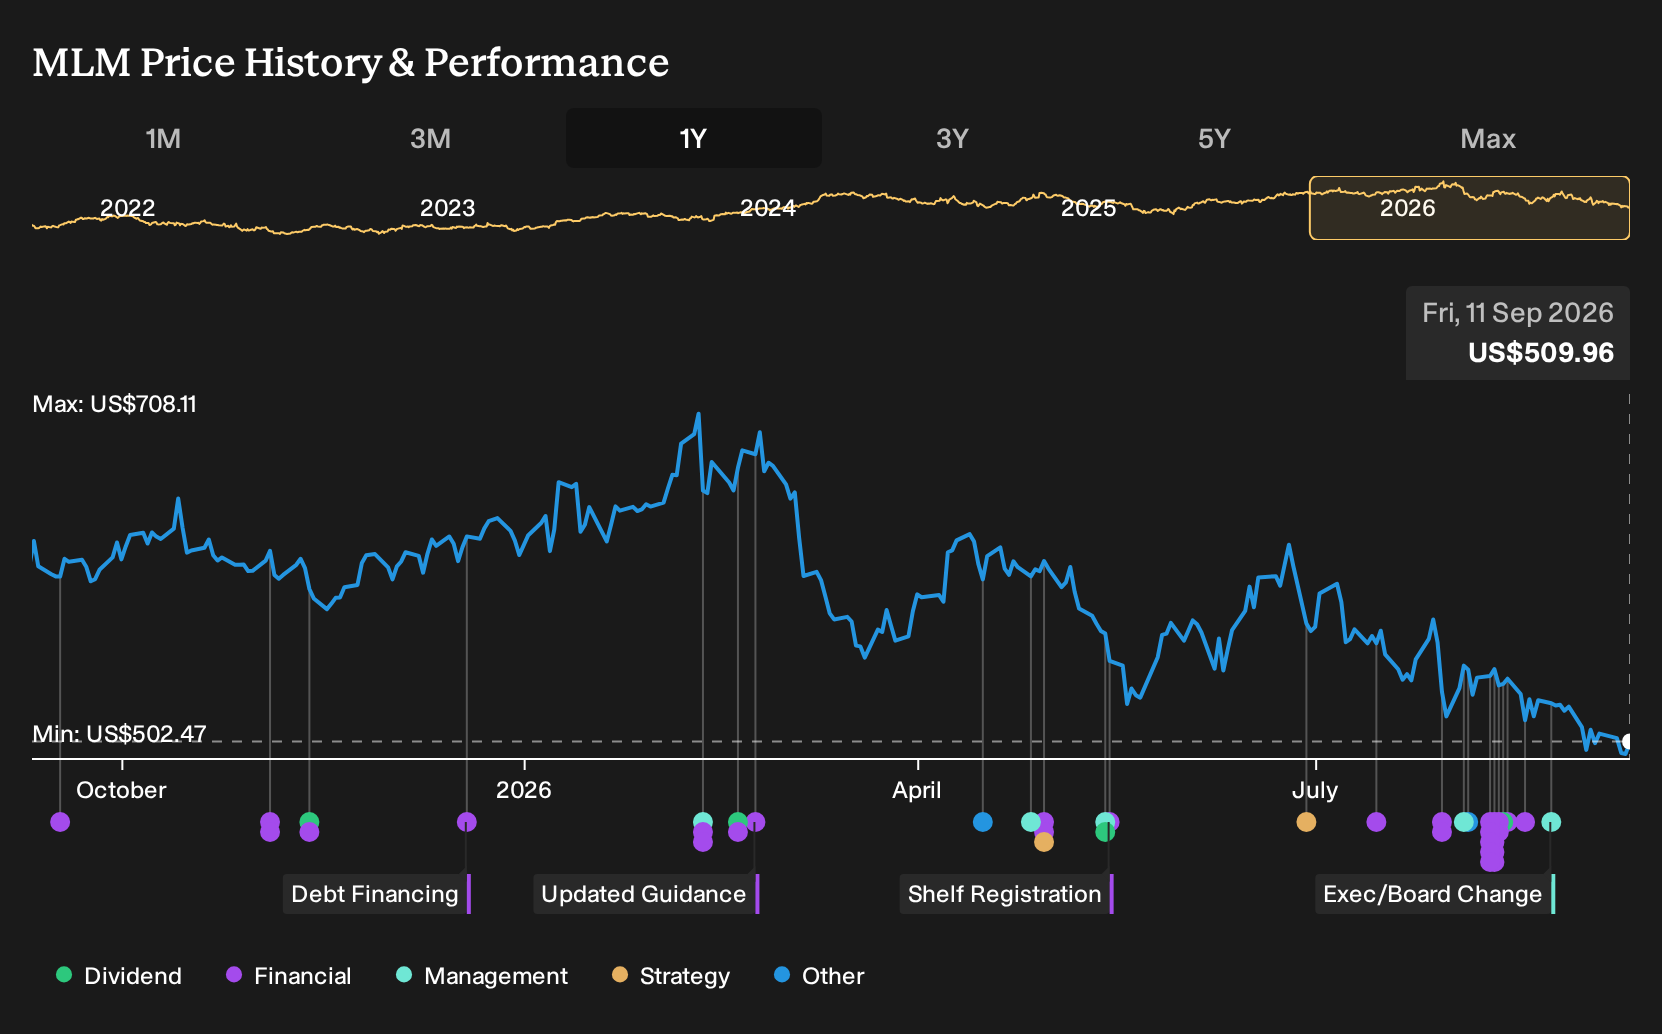
- Martin Marietta Materials has been dealing with weaker demand from residential and private nonresidential construction along with higher fuel, energy, raw-material, and equipment costs, while acquisition-related charges have pressured profitability.
- The proposed Lhoist North America acquisition has raised concerns about potential share dilution and higher leverage, which has added to investor uncertainty around Martin Marietta Materials at a time when construction end markets already look challenging.
- We will now look at how this softer construction demand backdrop may reshape Martin Marietta Materials' broader investment narrative.
Compare Martin Marietta Materials' current challenges with a curated 39 power grid technology and infrastructure stocks that could also be shaped by infrastructure demand and construction spending cycles.
Martin Marietta Materials Investment Narrative Recap
For an investor to own Martin Marietta Materials, there needs to be conviction that infrastructure, public works, data center, and industrial projects can offset softer residential and private nonresidential activity over time. Recent news mainly reinforces that near term picture. Demand still looks mixed across end markets, and higher fuel, energy, and equipment costs are pressuring margins.
The key short term swing factor is whether infrastructure and large project demand can keep volumes and pricing firm while housing related categories stay weak. The biggest risk right now sits on the cost and balance sheet side. Elevated input costs and the potential for higher leverage from acquisitions could weigh on profitability if demand disappointment lasts longer than expected.
The most relevant current development is the proposed acquisition of Lhoist North America. This deal would expand Martin Marietta Materials further into magnesia and lime, building on the existing chemicals footprint that already includes magnesia based products for steel, soil stabilization, and environmental uses. That shifts the business mix slightly further away from pure aggregates.
For you as a shareholder, the near term questions around Lhoist are largely execution and balance sheet related. Management needs to integrate new operations efficiently, manage acquisition related charges, and handle any share issuance or extra borrowing without stretching leverage. The deal could influence how quickly the firm can fund future projects, respond to any slowdown in public spending, and keep net margins from slipping further after the recent compression from 16.1% to 13.9%.
Martin Marietta Materials' current analyst narrative points to revenues of US$8.8b and earnings of US$1.6b by 2029, based on an assumed 9.6% yearly revenue growth rate, which implies an earnings increase of about US$670m from current earnings of US$930.0m.
Uncover why Martin Marietta Materials' fair value indicates a 30% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Martin Marietta Materials focuses on pricing risk rather than infrastructure support. The most cautious analysts assumed only 7.7% annual revenue growth and earnings of about US$1.5b by 2029 before this news. That is materially below the consensus path and shows how sharply opinions can diverge. Use this news as a prompt to test both stories for yourself.
Explore 3 other Martin Marietta Materials fair value estimates, including one that suggests it could be worth just $571.60.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Martin Marietta Materials research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Martin Marietta Materials. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Martin Marietta Materials' overall financial health at a glance.
Looking For More Investment Ideas Beyond Martin Marietta Materials?
Once you have a view on Martin Marietta Materials, it can help to line it up against other opportunities and see where it truly fits in your portfolio. The Simply Wall St Screener lets you filter the market by fundamentals so you can compare businesses on the same footing.
- If capital preservation sits high on your list, start with resilient candidates through the 11 resilient stocks with low risk scores that already meet strict risk filters.
- For investors hunting for quality at a reasonable entry point, line up potential opportunities using the 32 high quality undervalued stocks based on fundamentals, not hype.
- If you want sturdier balance sheets to complement a holding like Martin Marietta Materials, build a watchlist from the list of solid balance sheet and fundamentals (23 results) and see which businesses match your comfort level on debt and financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com