
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Central Securities (CET) Rallies As Investors Revisit Whether Its Valuation Still Looks Cheap
Central Securities (CET) is back on investor radar after recent share price gains, with the stock closing at US$56. This closed end fund structure and long history naturally raise valuation questions.
Recent trading has been constructive for Central Securities, with a 1-day share price return of 0.90% and a 7-day share price return of 2.23% feeding into a 90-day share price return of 5.44% and a year to date share price return of 10.39%. Over a longer window, the 1-year total shareholder return of 16.58% and 3-year total shareholder return of 81.28% point to momentum that has built gradually rather than in a single spike. This helps frame the current US$56 share price and the fund’s long history in a broader performance and valuation context.
Scan how Central Securities stacks up against other listed funds and managers by running the 15 high quality undiscovered gems while this momentum story is front of mind.
Central Securities has a long operating record and recent returns that look solid on the surface. After this latest move to US$56, are you paying a fair price for that record or stretching for it?
Price-to-Earnings of 7.6x: Is it justified?
Central Securities trades on a P/E of 7.6x at a share price of $56, which screens as inexpensive compared to its own Capital Markets peers.
The P/E ratio compares what investors currently pay for each dollar of earnings. For a closed end fund manager like Central Securities, this frames how the market is treating its profit stream from investment income and fees.
CET's earnings have grown by 8.6% per year over the past 5 years, although the most recent year shows profit growth of 1.5% and lower net profit margins than the prior period. That mix of a multi year record, a softer recent result and an 11.8% return on equity that is considered low against a 20% benchmark helps explain why the stock trades at a discount multiple.
Compared with the US Capital Markets industry average P/E of 39.6x and a peer average of 13x, Central Securities sits at a lower valuation, which indicates the market is assigning a lower price tag to each dollar of its earnings than it does for comparable groups.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 7.6x
Still, Central Securities relies heavily on US markets and a single closed end fund revenue stream, so any weaker investment income or fee pressure could quickly challenge this valuation story.
Find out about the key risks to this Central Securities narrative.
Another View on Central Securities Fair Value
The earnings multiple paints one picture, but the SWS DCF model offers a very different one. On that cash flow view, Central Securities at $56 is trading below an estimated fair value of $153, which frames the current price as heavily discounted. The real question is whether those model assumptions hold up in the long run.
Look into how the SWS DCF model arrives at its fair value.
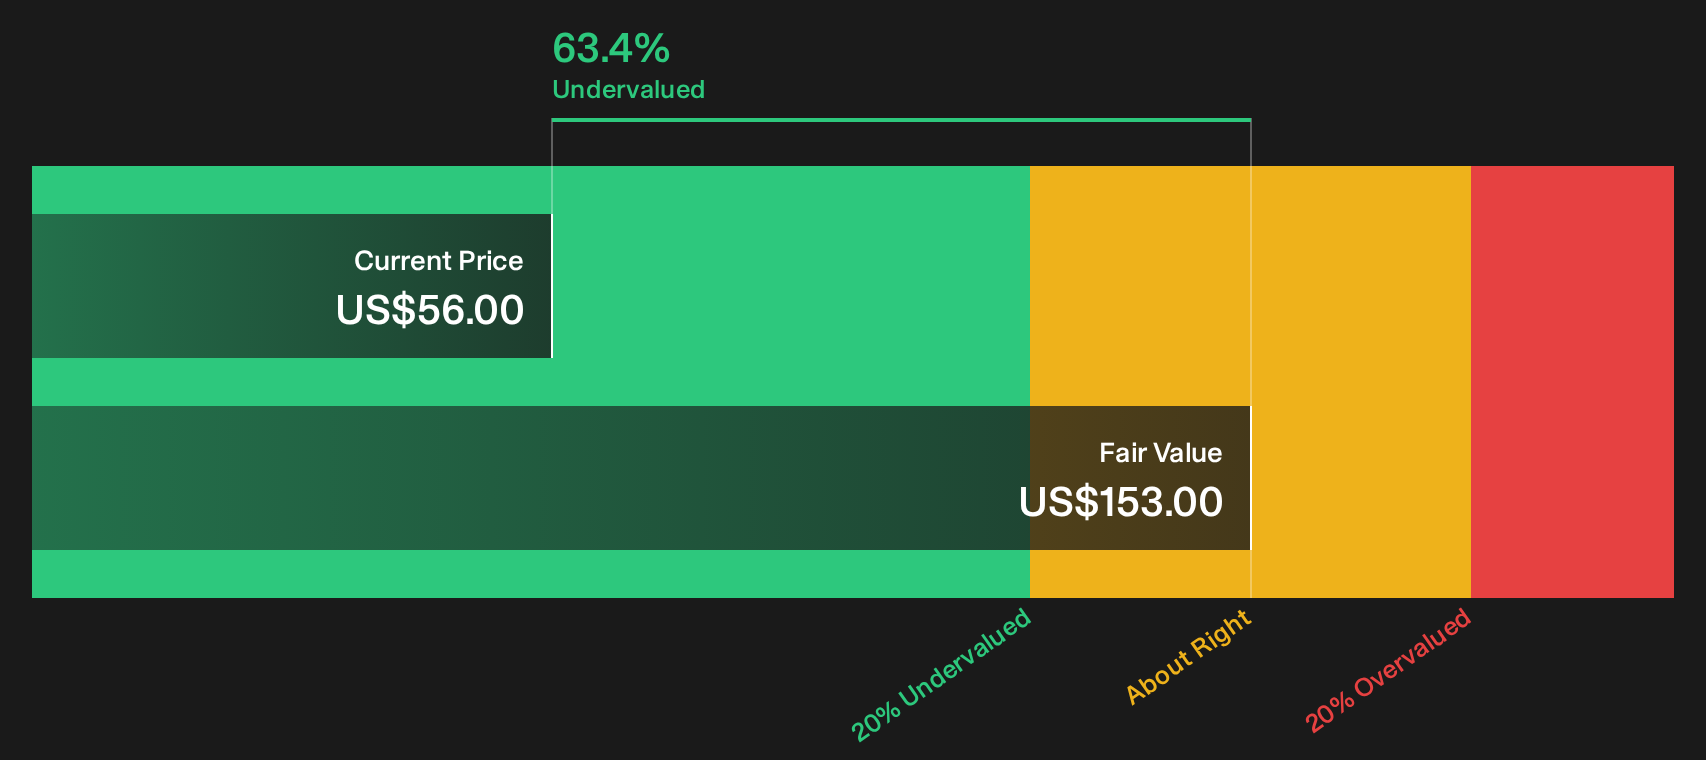
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Central Securities for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Central Securities valuation and risk can be confusing. Review the data yourself and decide quickly where you land on this story by weighing the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Central Securities?
If Central Securities has sharpened your thinking on valuation and risk, you can continue that momentum by widening your opportunity set with targeted screeners.
- Focus on quality at a discount and see which companies currently screen as 32 high quality undervalued stocks for a potential margin of safety.
- Prioritise resilience and sift through a 11 resilient stocks with low risk scores that can help anchor a more balanced portfolio.
- Upgrade the quality of your watchlist by scanning a list of solid balance sheet and fundamentals (23 results) that can handle tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com