
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is New CMO Hire Altering The Investment Case For Boston Beer Stock (SAM)?
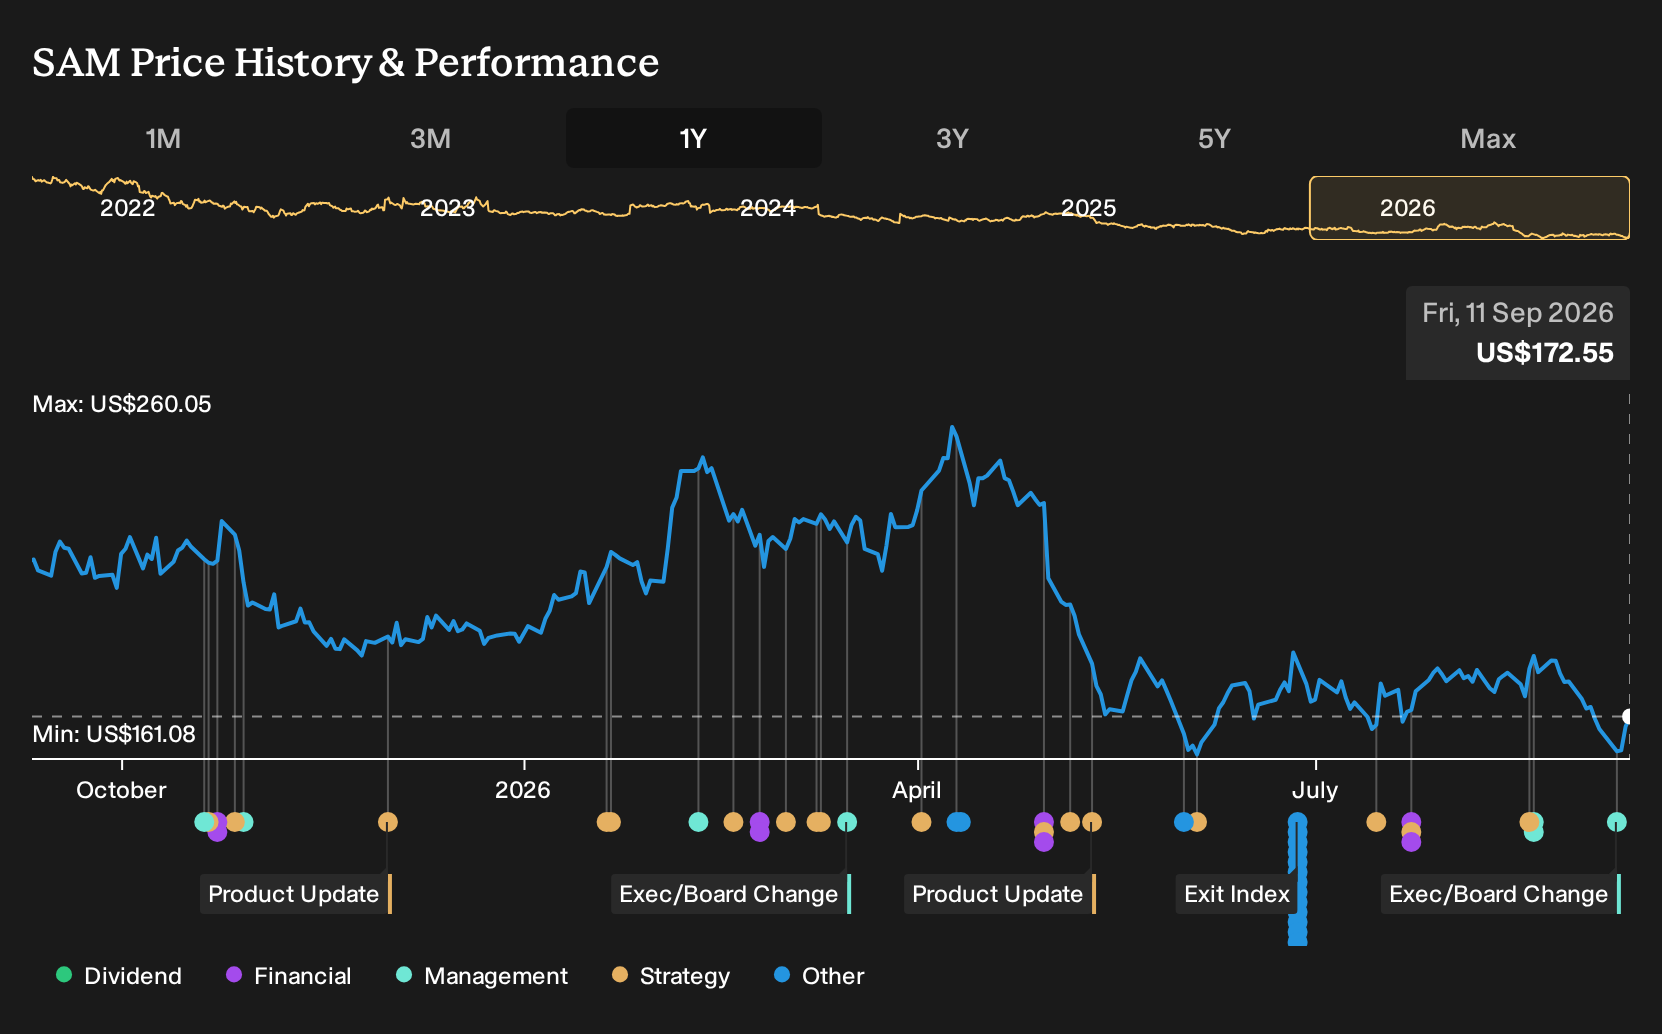
- Boston Beer Company appointed Allison Stransky as Chief Marketing Officer in October 2026, putting her in charge of marketing across Samuel Adams, Dogfish Head, Twisted Tea, Truly Hard Seltzer, Angry Orchard, Sun Cruiser and other brands.
- Stransky brings more than 20 years of consumer and data-focused marketing experience from Samsung, Google, L'Oréal, Unilever and Johnson & Johnson. This background directly relates to Boston Beer Company’s push toward digital, insight-led brand building across crowded Beyond Beer categories.
- The focus now turns to how Boston Beer Company’s investment narrative could be shaped by Stransky’s data-driven, portfolio-wide marketing remit.
Boston Beer Company Investment Narrative Recap
To own Boston Beer Company, you need to believe its mix of beer and Beyond Beer brands can keep consumer interest despite a slow overall category and intense competition. The near term story is about stabilising volumes while protecting margins through pricing, productivity efforts and tighter focus on what actually sells through distributors.
The CMO appointment does not change the core catalyst, which is whether products like Twisted Tea, Truly and Sun Cruiser can sustain demand without excessive discounting. The biggest near term risk still sits in crowded shelves and potential product fatigue in hard seltzer and RTD, which could pressure marketing spend and profitability.
The recent appointment of Allison Stransky as Chief Marketing Officer matters most because it directly touches Boston Beer Company’s key risk and key opportunity. Marketing decisions now span Samuel Adams, Twisted Tea, Truly, Angry Orchard and newer brands under a single, data focused leader tied closely into the CEO and COO.
For you as a shareholder, the operational question is simple: Can this unified, insight led marketing approach sharpen which SKUs get support, how budgets shift between beer and Beyond Beer, and where digital spend actually drives repeat buying? Execution on that front will feed straight into volume resilience, mix, and ultimately margin outcomes.
Boston Beer Company’s current loss of $70.4 million is set against analyst expectations for earnings of $107.3 million on US$1.9b of revenue by 2029. This implies a very large earnings swing in value terms rather than a modest uptick, while overall revenue is assumed to stay broadly flat over that period.
Uncover why Boston Beer Company's fair value indicates a 16% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One more optimistic angle on Boston Beer Company puts Sun Cruiser at the centre of the story. The most bullish analysts were already modelling revenue around US$2.0b and earnings of about US$148.7 million by 2029 before this CMO news. You can compare that upbeat view with your own and decide which narrative feels more realistic.
Explore 2 other Boston Beer Company fair value estimates, including one that suggests as much as 69% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Boston Beer Company research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Boston Beer Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Boston Beer Company's overall financial health at a glance.
Looking for more Boston Beer Company style ideas?
If the Boston Beer Company story has sharpened your thinking, use that momentum to scan for other businesses that fit the kind of balance sheet strength, income potential, or upside profile you want in your portfolio.
- For investors who want potential upside paired with financial resilience, start with a focused list of companies showing solid fundamentals and strong balance sheets through the list of solid balance sheet and fundamentals (23 results).
- If reliable cash flow and income are priorities, narrow the field to businesses with robust payout profiles using the 6 dividend fortresses.
- When you want ideas that are still off most radars but backed by healthy metrics, scan a curated pool of under-followed opportunities via the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com