
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Vita Coco Company (COCO) Could Be 38% Below Fair Value As Earnings Near
Vita Coco Company (COCO) is back on investors screens after a 1.78% share price gain and fresh attention on its upcoming earnings release, with forecast EPS and revenue expected to expand year over year.
Recent trading has been choppy for Vita Coco Company, with the share price down 20.24% over 30 days and 37.22% over 90 days. However, the 1-year total shareholder return of 31.44% and 3-year total shareholder return of 94.14% point to longer term momentum that recent earnings optimism may be testing rather than reversing.
Scan peer opportunities around Vita Coco Company by reviewing the hand picked 15 high quality undiscovered gems that share strong fundamentals and under the radar momentum potential.
After a sharp pullback yet strong multi year returns, Vita Coco Company now has investors asking a simple thing: Does the current setup still tilt the risk reward in favor of new buyers as valuation comes under the microscope?
Most Popular Narrative: 37.8% Undervalued
The most widely followed valuation narrative for Vita Coco Company places fair value at $83.56, well above the recent $52.01 close. This puts the focus squarely on what is being modeled into future cash flows.
Heightened investment in international markets (notably Europe) is resulting in accelerating sales growth and market share gains, with management expecting international revenues to ultimately rival the Americas business, thus significantly impacting consolidated revenues and earnings power.
Read the complete narrative. Read the complete narrative.
Want to see what earnings trajectory and margin profile have to look like for Vita Coco to earn that premium valuation gap? The core of this story is a step up in global scale, a richer mix of premium coconut products, and a future profit multiple usually reserved for much larger beverage groups. Curious which specific growth and profitability assumptions sit underneath that $83.56 fair value and a higher implied P/E than the wider sector? The full narrative lays out the numbers behind that view in detail.
Result: Fair Value of $83.56 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Vita Coco Company story can break if tariff costs on imported coconuts climb sharply or if private label softness drags on overall revenue momentum.
Find out about the key risks to this Vita Coco Company narrative.
Another View On Vita Coco Company’s Valuation
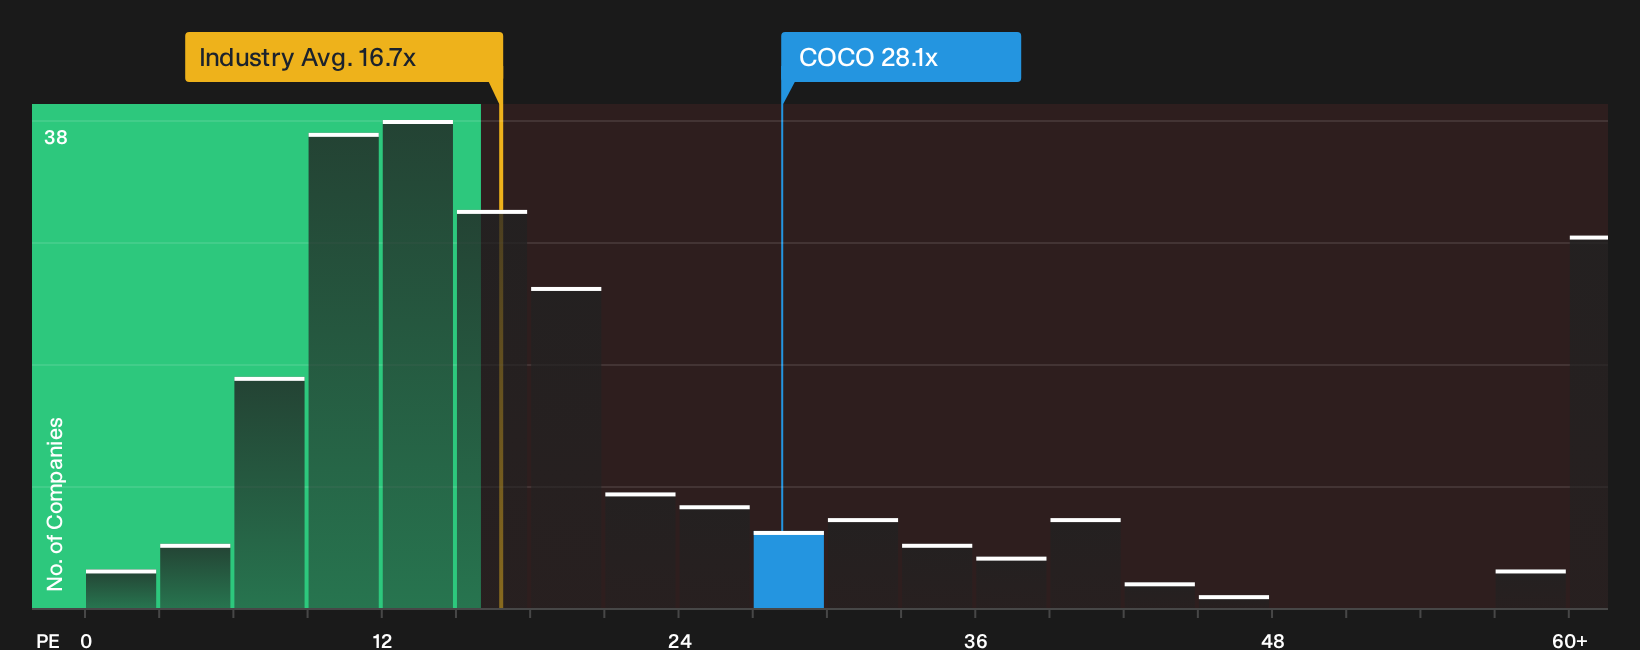
The first story on Vita Coco Company leans on future cash flows and lands on a fair value near $83.56, which screens as undervalued against the $52.01 share price. A simple P/E check tells a different story. COCO trades on 28.1x earnings, far above the Global Beverage group on 16.7x and its own fair ratio of 19.2x. This points to valuation risk rather than a clear bargain and raises the question of which lens you trust more when real money is on the line.
To pressure test that earnings based view against detailed valuation work, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Vita Coco Company is split, which is exactly when fresh data can matter most. Move quickly and pressure test the upside story yourself by reviewing the 4 key rewards.
Looking for more investment ideas beyond Vita Coco Company?
If Vita Coco Company has your attention, do not stop here. Broaden your watchlist across fresh themes and let data driven filters surface ideas you might otherwise miss.
- Target potential value opportunities early by scanning the 32 high quality undervalued stocks that match strong fundamentals with pricing that has not yet caught up.
- Prioritize resilience by focusing on the 11 resilient stocks with low risk scores which highlight businesses with sturdier financial profiles and lower risk scores.
- Hunt for quality off the beaten path through the 15 high quality undiscovered gems that remain underfollowed despite solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com