
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Coherent (COHR) Beat Fourth Quarter Estimates, Is It Still 26% Undervalued?
Coherent (COHR) moved back into focus after reporting fiscal fourth quarter adjusted earnings and revenue above consensus estimates, with Datacenter & Communications driving year over year gains and management pointing to improved margins in early fiscal 2027.
Coherent’s share price reacted quickly to the earnings beat, with a 1-day share price return of 4.16% and a 7-day gain of 8.34%. However, the stock is still down 26.21% over 90 days and 6.28% over 30 days, while total shareholder return over the past year is 196.50% and very large over three and five years, which points to strong long term momentum even as near term sentiment has cooled.
Scan beyond Coherent and see how other optical and datacenter suppliers are positioned with the hand picked 89 AI infrastructure stocks.
Coherent now trades at a sizeable discount to both analyst targets and some intrinsic value estimates after that earnings pop. Is the market being fairly cautious here, or is it mispricing the setup ahead of those margin ambitions?
Most Popular Narrative: 26.5% Undervalued
Coherent's most followed narrative pegs fair value at $415.36 against a last close of $305.37. This frames a sizable valuation gap that rests heavily on data center momentum and margin expansion over time.
The ongoing expansion of AI datacenter infrastructure and high-performance computing is propelling structural growth in demand for advanced optical transceivers (800G, 1.6T, and beyond), optical circuit switches, and related photonics components, which is fueling robust sequential order growth and sustained revenue momentum in Coherent's datacom and communications business.
Read the complete narrative. Read the complete narrative.
This view examines what kind of revenue trajectory and profitability lift would need to hold for that valuation gap to close. The fair value call leans on aggressive top line expansion, improving margins and a richer profit multiple than the broader electronics space. The detailed narrative lays out how those pieces are expected to link together and what would need to go right for Coherent to grow into that profile.
Result: Fair Value of $415.36 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, two pressure points could upset that storyline: tougher optical transceiver competition and any wobble in large customer orders, such as from Apple or hyperscalers.
Find out about the key risks to this Coherent narrative.
Another View: Coherent Looks Expensive On Earnings
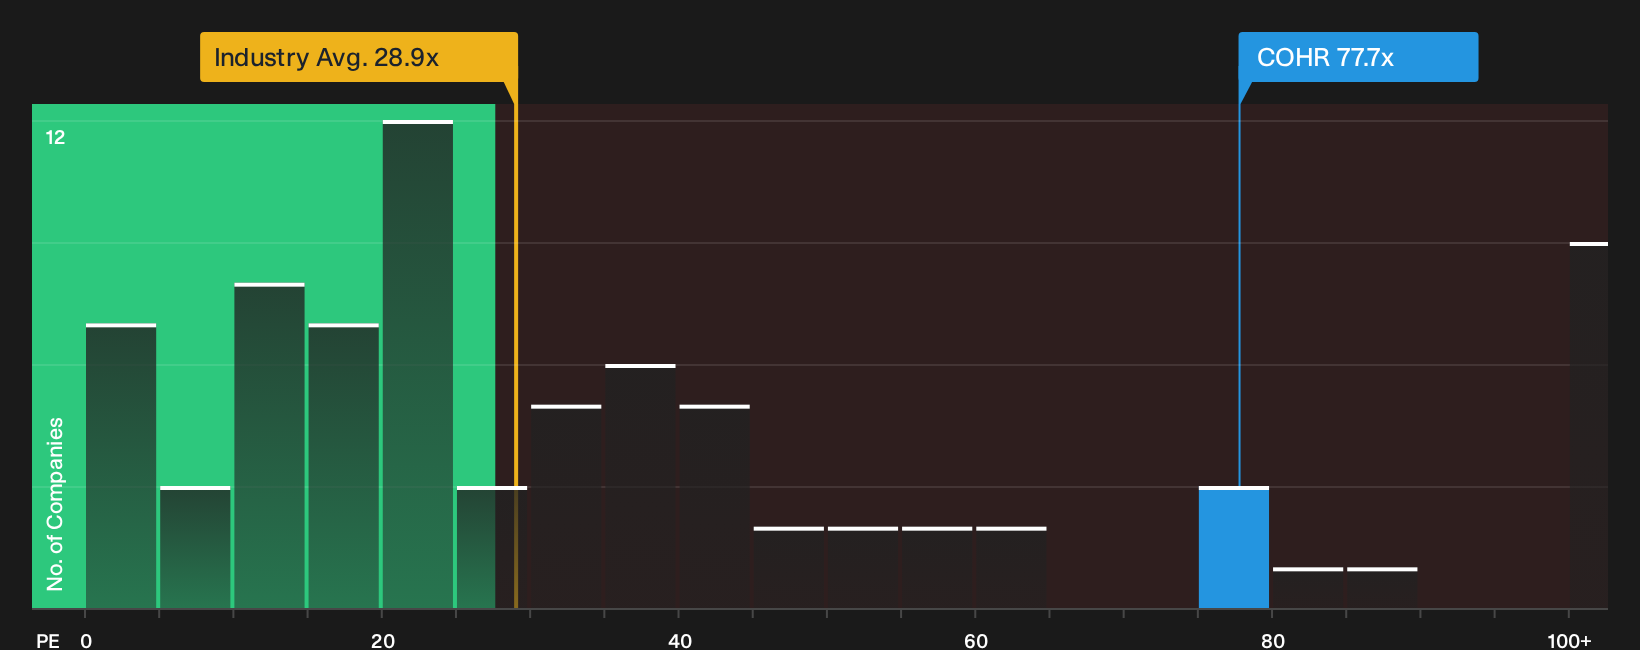
The DCF narrative for Coherent points to undervaluation, yet the earnings multiple tells a very different story. The stock trades on a P/E of 77.7x versus 28.9x for the US Electronic industry and a fair ratio of 65.5x, which signals richer pricing and higher valuation risk if expectations cool.
Investors weighing these opposing signals may want to see how the numbers stack up in more detail through our valuation breakdown, then decide which lens feels more realistic for their own assumptions. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The split between bullish optimism and valuation worries is clear. Move quickly, pull up the full data set, and test whether the upside or the downside case feels stronger to you once you have weighed the 4 key rewards and 2 important warning signs.
Ready for more ideas beyond Coherent?
Do not stop your research with Coherent. Broaden your watchlist with a few focused screens that surface very different types of opportunities before the crowd notices.
- Target potential upside by scanning companies that look cheap on quality and valuation using the 32 high quality undervalued stocks.
- Build income resilience by reviewing businesses that offer higher yields and focus on stable payouts through the 6 dividend fortresses.
- Reduce portfolio stress by filtering for companies with stronger financial footing and cleaner balance sheets via the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com