
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 U.S. Energy Stocks With Inflation Sensitive Cash Flow Stories
Inflation just reminded markets that energy still calls a lot of the shots. August CPI ran hotter than July, with gasoline a key driver, and that ripple runs straight through U.S. oil, gas and refining stocks. For investors, that mix of sticky prices and an upcoming October CPI print creates both risk and potential mispricing. This article examines three U.S. energy sector stocks that are exposed to this inflation story and explains why they may warrant closer attention now.
The three companies in focus here are only a starting sample, since the full screen surfaces 53 more U.S. energy stocks with similar inflation-sensitive stories that are not covered below. To see the broader opportunity set and quickly identify which businesses align with your thesis, head straight into the U.S. Energy Sector Stocks (with emphasis on Oil & Gas and Refining) screener.
Oil States International (OIS)
Oil States International is closely linked to hydrocarbon spending because it supplies the equipment and consumables that keep oil and gas projects running, which makes its performance particularly relevant when inflation data keeps energy prices in focus.
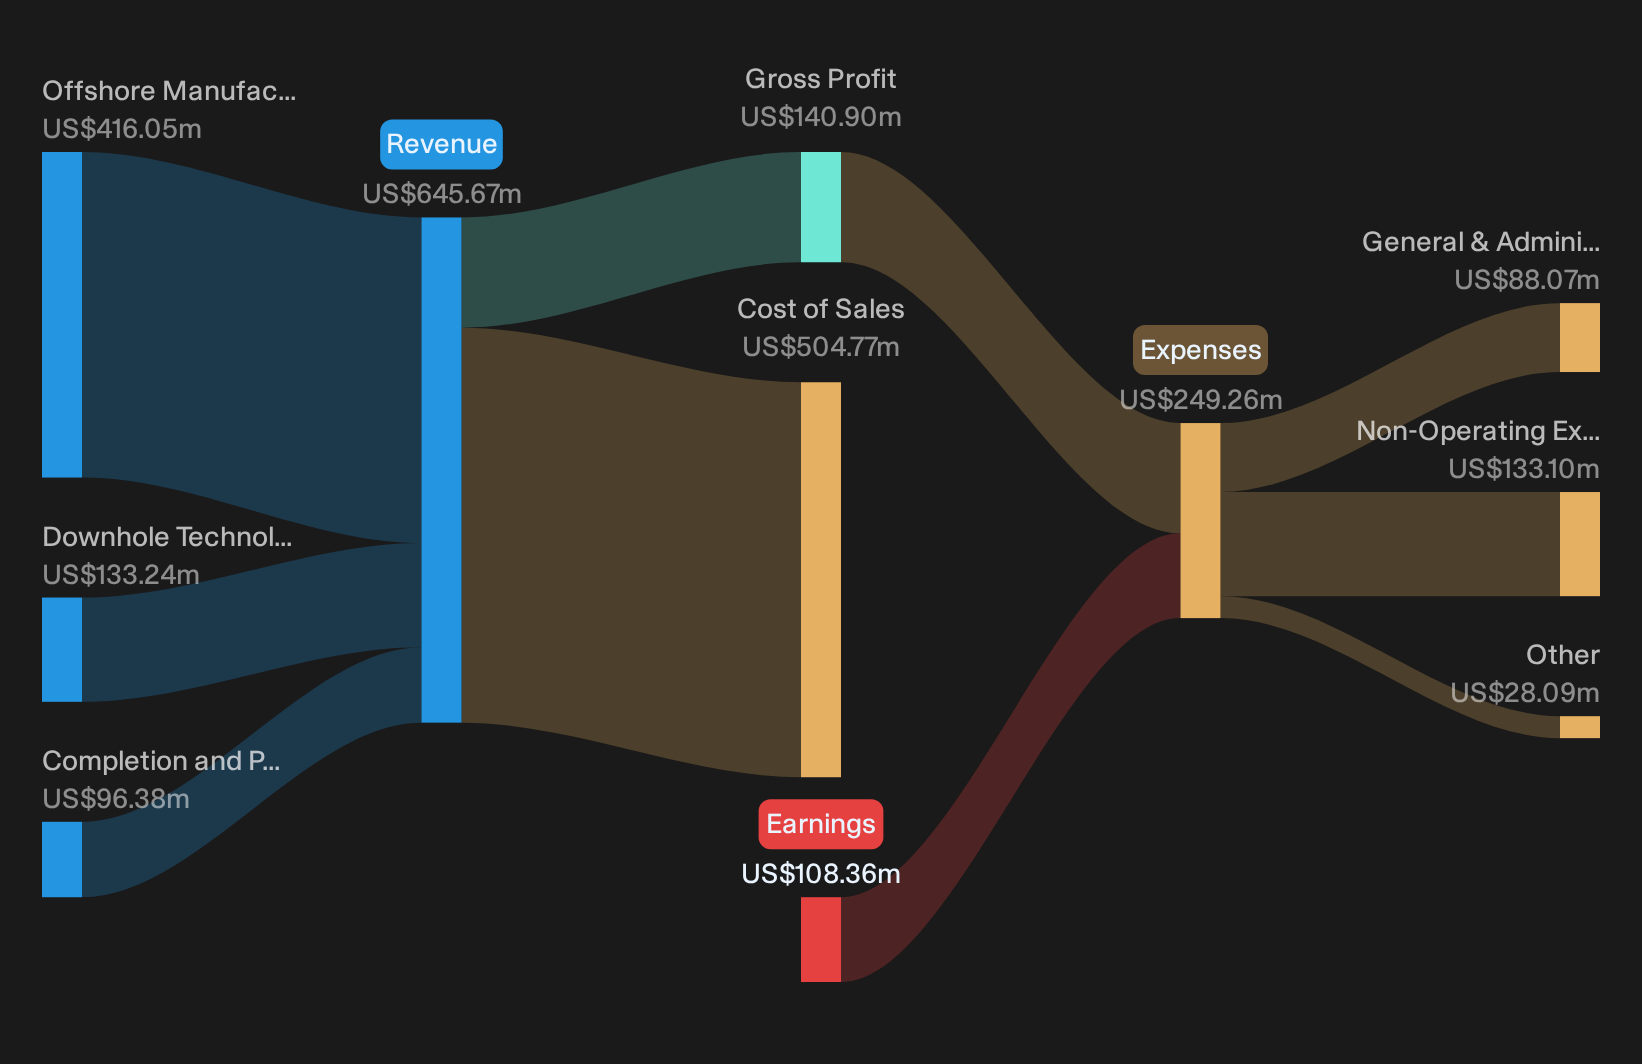
Oil States International supplies engineered equipment and consumables across the oil and gas value chain, with Offshore Manufactured Products generating about $416 million of revenue, Downhole Technologies about $133 million, and Completion and Production Services about $96 million, and the stock valued at roughly $524 million.
"The completion of the Indonesia manufacturing facility not only enables OIS to fill growing Asia-Pacific demand for advanced offshore solutions but also creates a flexible export hub for global projects. This allows for geographic diversification and lower cost manufacturing that can enhance future operating leverage and net income."
What matters next is how a single shift in offshore project activity affects pricing power and operating margins over time.
That margin sensitivity is exactly what the full narrative for Oil States International unpacks, showing how offshore exposure, inflation and project timing could be quietly reshaping Oil States International’s next phase.
Antero Midstream (AM)
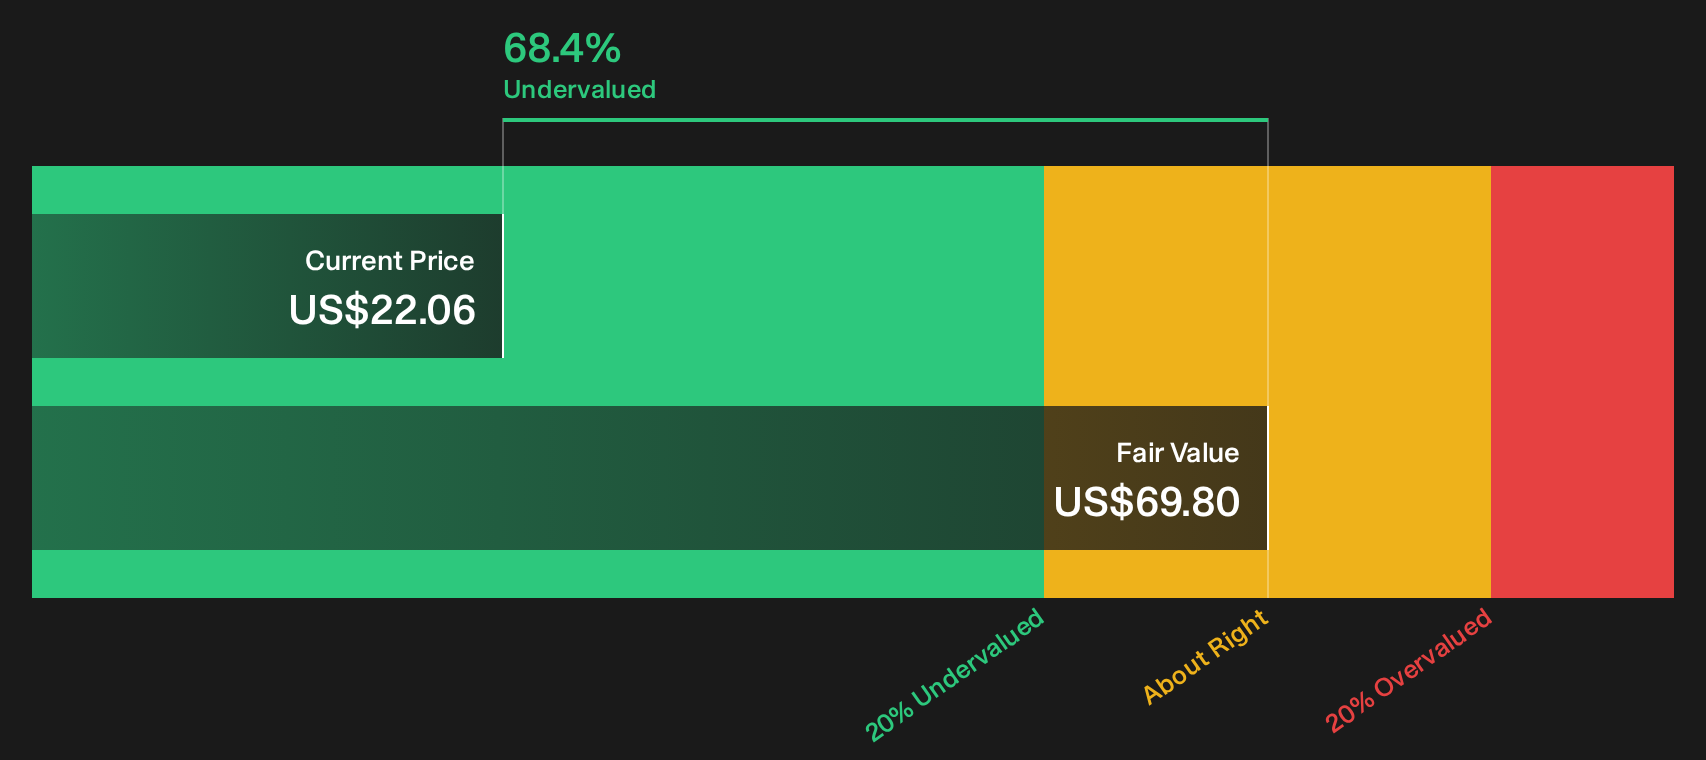
Antero Midstream runs gathering, processing and water systems that move Appalachian natural gas for Antero Resources, a direct fit with the oil and gas infrastructure focus of this screener, with about US$1.03b from Gathering and Processing, US$278 million from Water Handling, and a market value near US$10.5b.
Higher inflation has put energy prices back in the spotlight, and Antero Midstream provides exposure through the pipes and water systems that keep Appalachian gas volumes moving rather than through direct commodity positions.
"Rising U.S. LNG export demand and expansion of Gulf Coast LNG facilities are expected to drive higher natural gas volumes from Appalachia, supporting Antero Midstream's gathering and processing volumes and underpinning sustained revenue growth."
The key issue now is how one pressure point in its capital structure may influence future cash available for both growth spending and dividends.
That pressure point is exactly what the full narrative for Antero Midstream unpacks, revealing how capital allocation, volume growth and inflation can either accelerate or quietly stall Antero Midstream's payout story.
Expro (XPRO)
Expro is tightly linked to the screener’s oil and gas theme because its well services and intervention work track real-world exploration and production activity across key offshore and onshore basins.
Expro provides well construction and well management services for oil and gas producers worldwide. Its revenue is spread across North and Latin America at about $539 million, Europe and Sub-Saharan Africa at roughly $483 million, MENA at around $351 million, and APAC at about $182 million, with the stock valued near $2.0b.
When inflation data keeps energy prices in focus, Expro offers exposure to the project work needed to keep hydrocarbons flowing. This is exactly why it features in this energy services screen.
"Expro's robust order intake and expanding backlog are supported by ongoing growth in global energy demand, particularly in international and offshore markets, positioning the company for steady long-term revenue growth as multiyear deepwater and international projects progress."
What happens if one pressure point in its profitability path improves faster than the market currently expects will matter a lot for investors.
If that profitability unlocks faster than expected, the full narrative for Expro shows how Expro’s backlog, capital intensity and pricing power could be quietly decoupling from headline energy sentiment.

Seeking Fresh Alternatives Beyond Energy?
Fresh ideas move first, and the best entries often come before momentum is obvious. Do not let the next breakout get away while it is still under the radar for now; get in early.
- Target resilient compounding by screening for businesses with strong balance sheets and cash flows using the curated list of solid balance sheet and fundamentals (23 results) that filters out weaker profiles.
- Ride early momentum in companies already generating profits from AI by scanning the hand picked 74 profitable AI stocks that aren't just burning cash before the crowd fully catches on.
- Position ahead of potential yield hunters by reviewing the curated 6 dividend fortresses that highlights businesses combining high payouts with financial robustness.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com