
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CoreCivic (CXW) And The Detention Funding Story After A Run Up In Valuation
CoreCivic (CXW) has drawn fresh attention after recent trading left the stock at US$34.93, with investors weighing solid revenue of US$2.48b against weaker annual net income growth and a year-to-date return of 83.6%.
CoreCivic’s recent move to US$34.93 caps a strong run, with a 6.4% 1 month share price return contributing to an 83.6% year to date share price gain, while the 5 year total shareholder return of 308.1% points to momentum that has been building over a much longer stretch.
Scan beyond CoreCivic’s strong run and compare it with a curated group of resilient businesses in our 11 resilient stocks with low risk scores to see how other stocks with lower risk scores have been performing.
After a 308.1% five year total return and net income that moved in the opposite direction of revenue growth, CoreCivic now forces a sharper question: Does the current price still leave enough upside for the risk you take?
Most Popular Narrative: 16.4% Undervalued
Against CoreCivic’s last close at $34.93, the most followed narrative sets fair value at $41.80. This anchors the debate around how future contracts and earnings might justify that gap.
The unprecedented increase in mandatory government funding for federal detention and border security (notably, $75 billion for ICE and multi-year appropriations through 2029) is catalyzing rapid contracting activity, reactivation of idle facilities, and will significantly boost CoreCivic's recurring revenue and occupancy rates in future quarters.
Pressing demand for secure and reliable detention capacity due to record-high ICE populations and anticipated increases in U.S. Marshals Service detainees is driving new and expanded contracts. This will lift utilization rates at CoreCivic's facilities, with high incremental margins as idle beds are filled.
Want to understand why this narrative points to higher earnings power for CoreCivic while assuming a lower future earnings multiple than today? The entire case hinges on how fast revenue compounds, how margins reset on fuller facilities, and how those cash flows are discounted back. The key inputs are already on the table. The missing piece is how they interact in the full model.
Result: Fair Value of $41.80 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the whole CoreCivic case relies heavily on continued federal detention funding, as well as key ICE and U.S. Marshals contracts remaining in place.
Find out about the key risks to this CoreCivic narrative.
Another View: What Multiples Say About CoreCivic
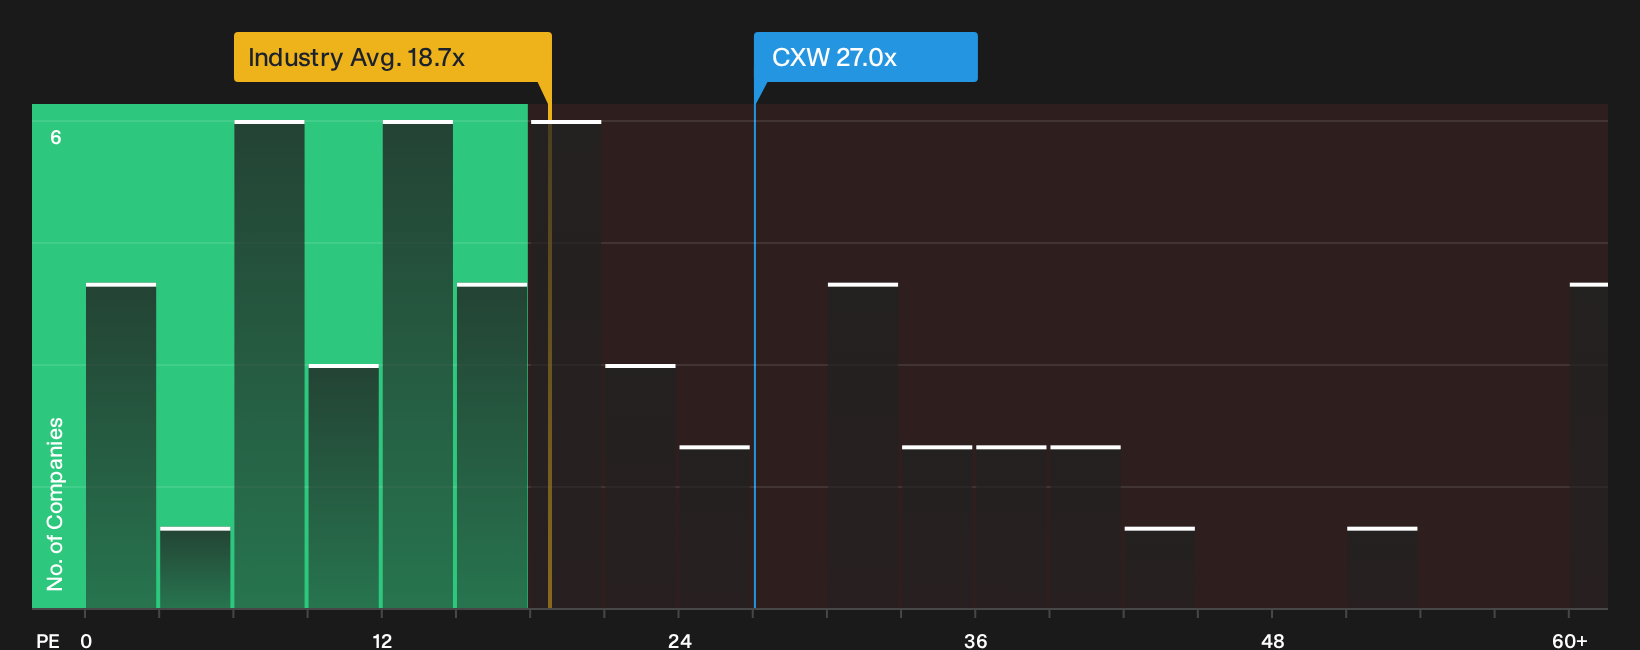
The narrative around a $41.80 fair value leans heavily on forecasts, but the current pricing signals something different. CoreCivic trades on a P/E of 27x compared with a fair ratio of 8.7x, the US Commercial Services average of 17.9x, and a 19.2x peer average.
That gap means investors today are paying a much richer price than both the sector and the level our fair ratio suggests the market could move toward. The real question is whether the earnings story and contract backdrop are strong enough for you to stay comfortable with that valuation risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The mixed sentiment around CoreCivic, with both risks and rewards in play, makes this a moment to check the numbers yourself and move quickly to your own view. To frame that decision with more structure, weigh the 1 key reward and 3 important warning signs.
Looking for more CoreCivic sized investment ideas?
If CoreCivic has you rethinking where risk and reward feel balanced, broaden your watchlist with a few targeted stock ideas sourced from the Simply Wall Street screener.
- Target stability by reviewing companies with strong finances through the list of solid balance sheet and fundamentals (23 results).
- Hunt for potential value by scanning the 32 high quality undervalued stocks before fresh interest crowds the trade.
- Secure potential income streams by assessing high yielding candidates in the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com