
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does Always U Launch Change The Bull Case For UniFirst (UNF)?
- UniFirst launched its Always U workwear line on September 5, 2026, offering higher stretch fabrics, mobility-focused design, and a dedicated women’s range tailored to industrial roles.
- The collection targets a long-ignored operational issue: worker comfort and fit, particularly for women in sectors like construction and manufacturing where standard uniforms have often been poorly suited.
- Investors may now consider how UniFirst’s investment narrative could be influenced by this comfort-focused Always U workwear launch.
Scan beyond UniFirst and find other workwear and industrial service providers aiming to turn functional gear into a retention edge with the list of solid balance sheet and fundamentals (23 results).
UniFirst Investment Narrative Recap
For UniFirst, the big-picture belief is that a relatively steady uniform rental and services model can support gradual revenue expansion and margin repair as operational projects like the ERP rollout and Owensboro expansion mature. The Always U launch could help that story if it supports customer retention and new contract wins in sectors like manufacturing and transportation.
The near term swing factor still sits in wearer levels and pricing discipline. If customer demand softens further or price competition intensifies, the benefit of premium workwear could feel muted. Rising health care expenses and delayed technology payoffs remain key risks that could pressure margins even as new products are added to the route trucks.
The Always U collection is the most relevant recent announcement. It connects directly to UniFirst’s core Uniform & Facility Service Solutions segment, where comfort, fit, and perceived value can influence contract renewals and wearer counts. A women’s line aimed at construction, manufacturing, and transportation also links to labor market realities that customers are already dealing with.
For you as an investor, the question is how effectively UniFirst turns this product refresh into better customer stickiness while it works through ERP timing, cost management, and tariff exposure. If adoption is slower than expected or pricing is too aggressive, the collection could add complexity without meaningfully changing the existing catalysts and risks.
UniFirst's current analyst narrative points to revenues of US$2.7b and earnings of US$165.1m by 2029. These projections are built on forecast annual top line growth of 3.4% and an earnings increase of about US$29.5m from current earnings of US$135.6m.
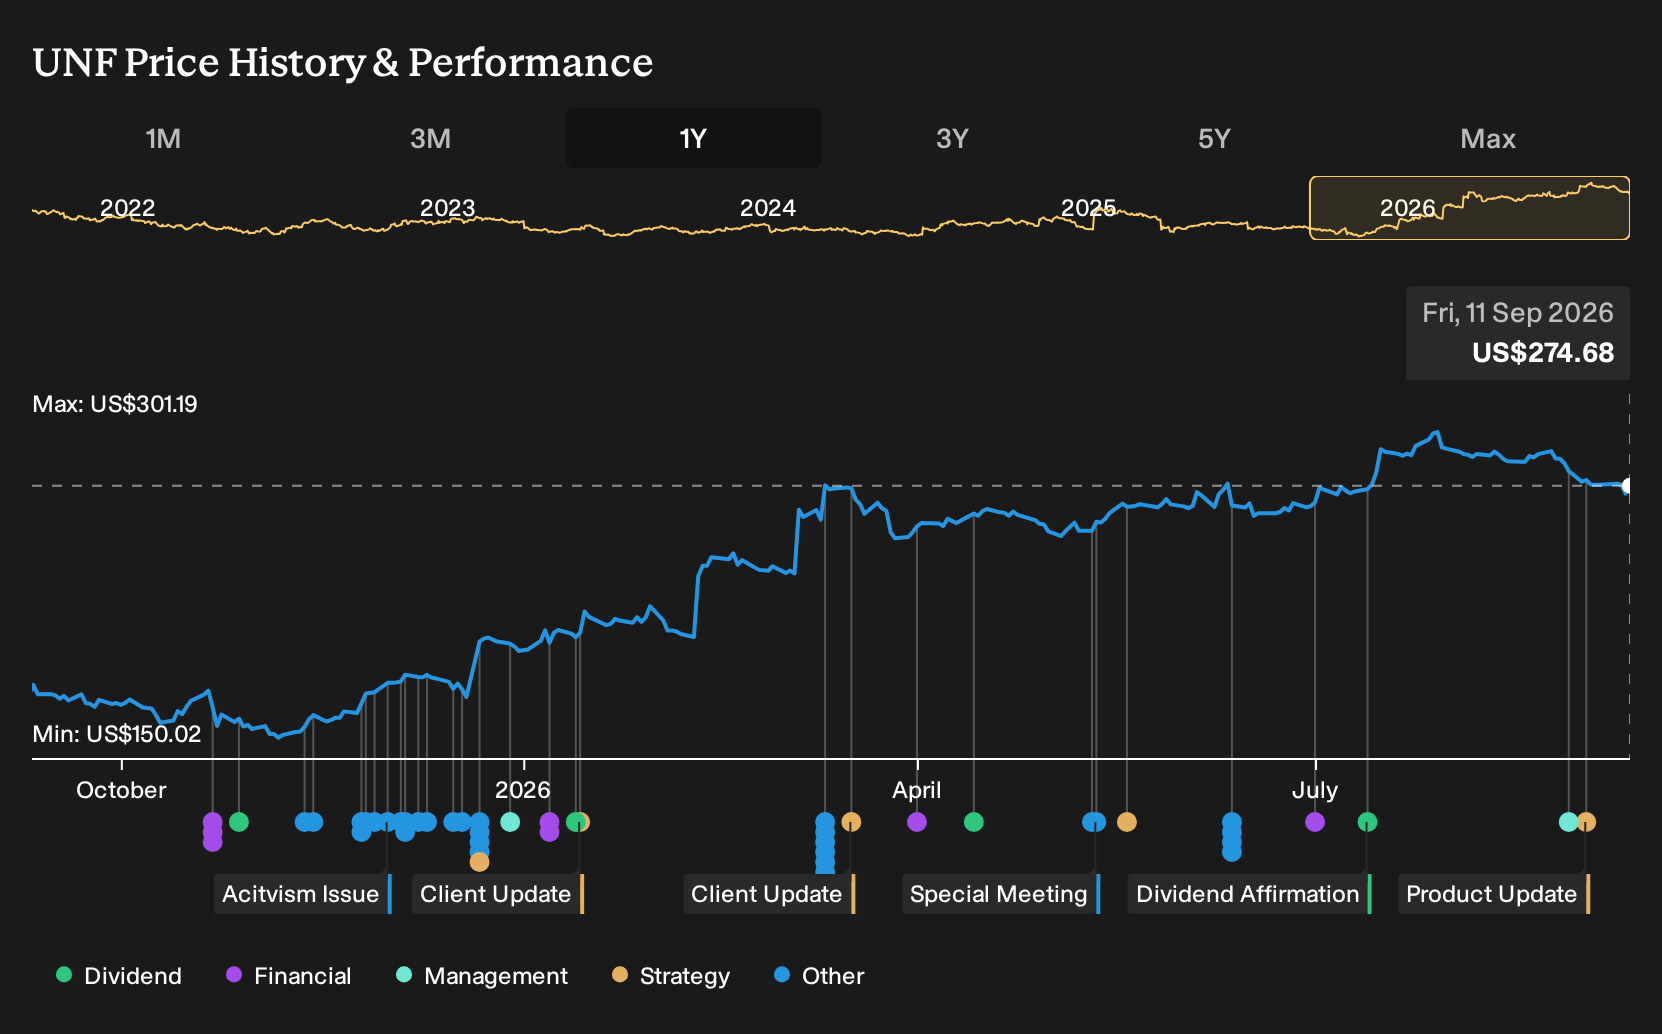
Uncover why UniFirst's fair value is in line with its current price.
Exploring Other Perspectives
One alternate view focuses on ERP execution risk rather than product launches. The most cautious UniFirst analysts were already baking in revenue of about US$2.8b and earnings of US$171.3m by 2029, yet still landed on a lower US$260 price target. That gap shows opinions can differ widely. Use this Always U news to revisit several viewpoints.
Explore 2 other UniFirst fair value estimates, including one that suggests as much as 50% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your UniFirst research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for UniFirst. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UniFirst's overall financial health at a glance.
Looking for more UniFirst-sized investment ideas?
If this UniFirst update has sharpened your thinking on quality, income, and resilience, you can apply that same lens across a broader watchlist using the Simply Wall St Screener.
- If you want potential mispricing with fundamentals to back it up, scan a curated pool of 32 high quality undervalued stocks that pair financial quality with more modest valuations.
- If capital preservation and steadier profiles matter most to you, focus your search on 11 resilient stocks with low risk scores that show stronger balance sheets and lower overall risk scores.
- If you are drawn to resilient franchises that do not rely on heavy leverage or fragile cash flows, you can move beyond UniFirst and review a 15 high quality undiscovered gems that may not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com