
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Rockwell Automation (ROK) Faces Fresh Value Scrutiny, Is The Stock Below Fair Value?
Fresh research comparing Rockwell Automation (ROK) with Kimball Electronics has put valuation in the spotlight, with Zacks rating Rockwell as a #3 Hold while positioning Kimball as the stronger value option.
Rockwell Automation’s share price has eased over the past month, with a 30-day share price return of 4.67% and a 90-day move down 7.59%. However, the year-to-date share price return of 7.49% and 1-year total shareholder return of 25.86% point to earlier momentum that has cooled as valuation debates, such as the recent comparison with Kimball Electronics, draw more attention to what investors are now willing to pay for that track record.
Compare Rockwell Automation with peers on valuation and momentum by scanning our hand picked 32 high quality undervalued stocks that may offer a stronger balance between price and fundamentals.
Rockwell Automation has cooled off after a strong 1-year run, leaving investors weighing fresh gains against the risk of paying too much for recent success. Does the current valuation still leave enough upside to justify that bet?
Most Popular Narrative: 9.7% Undervalued
Rockwell Automation last closed at $428.39, while the most followed narrative pegs fair value at $474.58, using a 9.26% discount rate to frame that gap.
Additional adoption of connected devices, advanced analytics, and IIoT solutions (including AI-driven predictive maintenance and cloud-native software) has driven double-digit growth in Rockwell's software and SaaS offerings, structurally lifting segment margins and strengthening recurring revenue streams, which should support higher blended net margins and earnings.
Investors may want to see what kind of revenue mix and margin profile that software shift assumes. The narrative refers to steadier top line progress and richer profitability to explain that valuation path.
Result: Fair Value of $474.58 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Rockwell Automation story relies on delayed customer CapEx eventually materialising, while heavier U.S.-focused investment could restrain progress in faster growing regions.
Find out about the key risks to this Rockwell Automation narrative.
Another View On Rockwell Automation’s Valuation
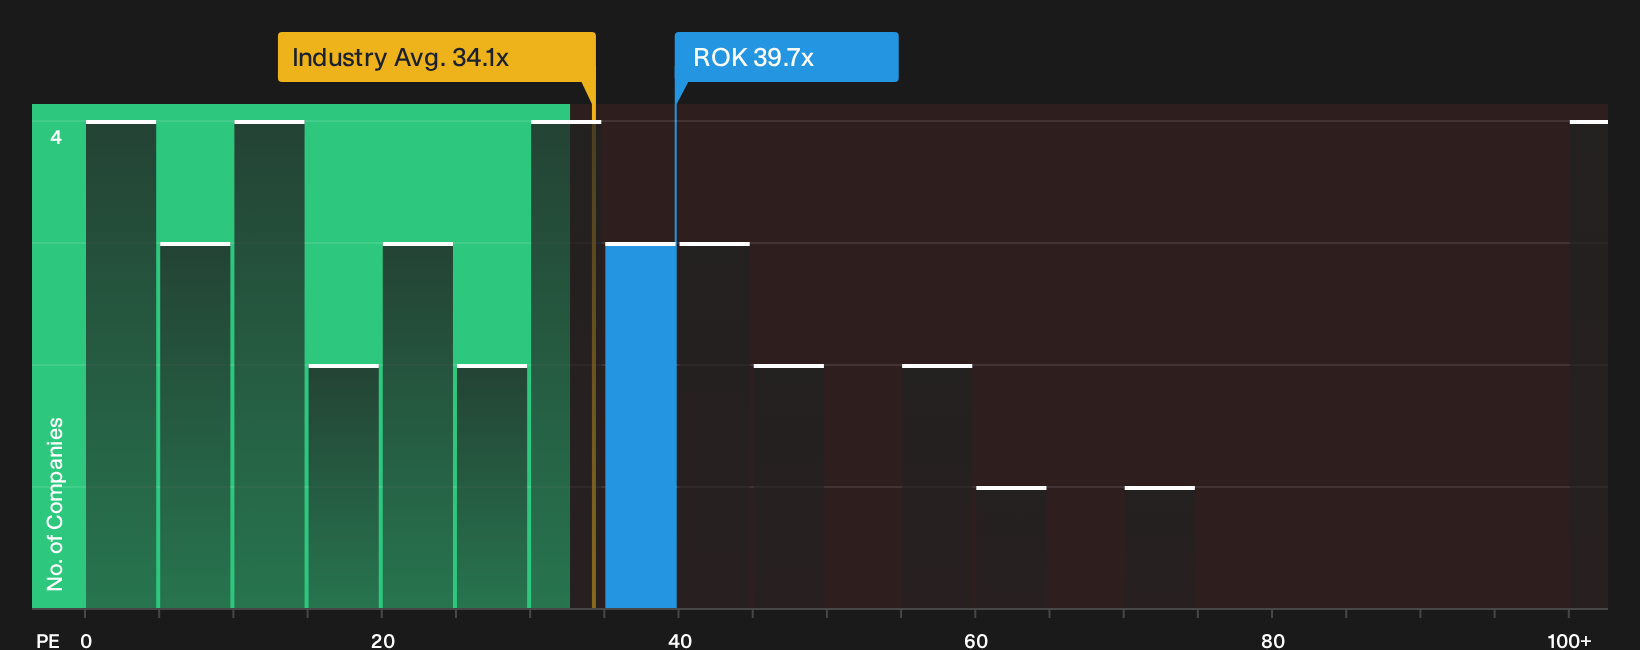
On the other side of the ledger, Rockwell Automation screens as expensive on earnings. The stock trades on a P/E of 39.7x, compared with 34.1x for the US Electrical industry, 34.9x for close peers, and a fair ratio estimate of 27.8x that the market could eventually lean toward. That premium points to potential valuation risk if sentiment cools before the fundamentals catch up. This raises a key question: which signal do you focus on more, the narrative fair value or the current earnings multiple?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Rockwell Automation’s valuation and growth story can create hesitation, so move quickly to review the data, pressure test the assumptions, and weigh the 2 key rewards and 1 important warning sign.
Ready for more Rockwell Automation style investment ideas?
If Rockwell Automation has you thinking harder about price and quality, use that momentum to widen your watchlist with focused, data driven stock ideas.
- Target dependable cash generators by scanning a 6 dividend fortresses that prioritizes income potential with robust underlying businesses.
- Hunt for quality at a discount through a 15 high quality undiscovered gems that highlights strong fundamentals the crowd may be overlooking.
- Cut down on unwanted surprises by filtering for a 11 resilient stocks with low risk scores designed to spotlight resilient balance sheets and steadier return profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com