
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Azrieli Group (TASE:AZRG) Looks Pricey, Is The Premium Already Priced In?
Azrieli Group (TASE:AZRG) has drawn investor attention after its recent share performance, with the stock down 0.8% at the latest close and weaker over the past week and month.
Short term momentum for Azrieli Group has cooled, with the share price down over the past week and quarter. However, the longer view still reflects a stronger picture, supported by a 1 year total shareholder return of 21.8% and a 3 year total shareholder return above 100%.
Spot opportunities beyond Azrieli Group by scanning a curated 99 resilient stocks with low risk scores list that has held up well on quality and risk metrics, even when short-term moves look choppy.Recent weakness in Azrieli Group now sits alongside strong multi year returns and upbeat analyst targets, so does the current valuation still leave more upside than downside for new buyers?
Price-to-Earnings of 26.1x: Is it justified?
On valuation, Azrieli Group trades on a P/E of 26.1x at a last close of ₪389.4, which screens as expensive against both local peers and the wider Israeli real estate sector.
The P/E ratio compares the current share price to earnings per share. For property companies like Azrieli Group, it gives a rough sense of how much investors are paying for each unit of current profit, and it often embeds expectations about future earnings, asset quality and the reliability of cash flows.
Here, the market is attaching a P/E that is more than double the peer average of 12.1x and also above the IL Real Estate industry average of 13.4x. That pricing suggests investors are willing to pay a premium for Azrieli Group relative to sector benchmarks. This may point to expectations around future earnings, the mix of assets across malls, offices, data centers and housing, or perceived resilience that is not reflected in the average real estate stock.
When the stock trades at 26.1x earnings while the IL Real Estate industry sits at 13.4x, the gap is wide and clear. The market is valuing each shekel of Azrieli Group earnings at roughly twice the going rate for the sector, which is a strong signal that expectations are materially higher than for a typical local peer.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 26.1x (OVERVALUED)
Still, a rich 26.1x P/E leaves Azrieli Group exposed if earnings momentum weakens or if investor appetite for premium-priced real estate stocks cools.
Find out about the key risks to this Azrieli Group narrative.
Another View on Azrieli Group’s Valuation
The P/E picture says Azrieli Group looks expensive, and the SWS DCF model points in the same direction. At a share price of ₪389.4 compared with an estimated future cash flow value of ₪88.78, the stock screens as heavily overvalued on this second yardstick too. If both earnings and cash flow signals lean rich, what exactly is the market paying up for?
Look into how the SWS DCF model arrives at its fair value.
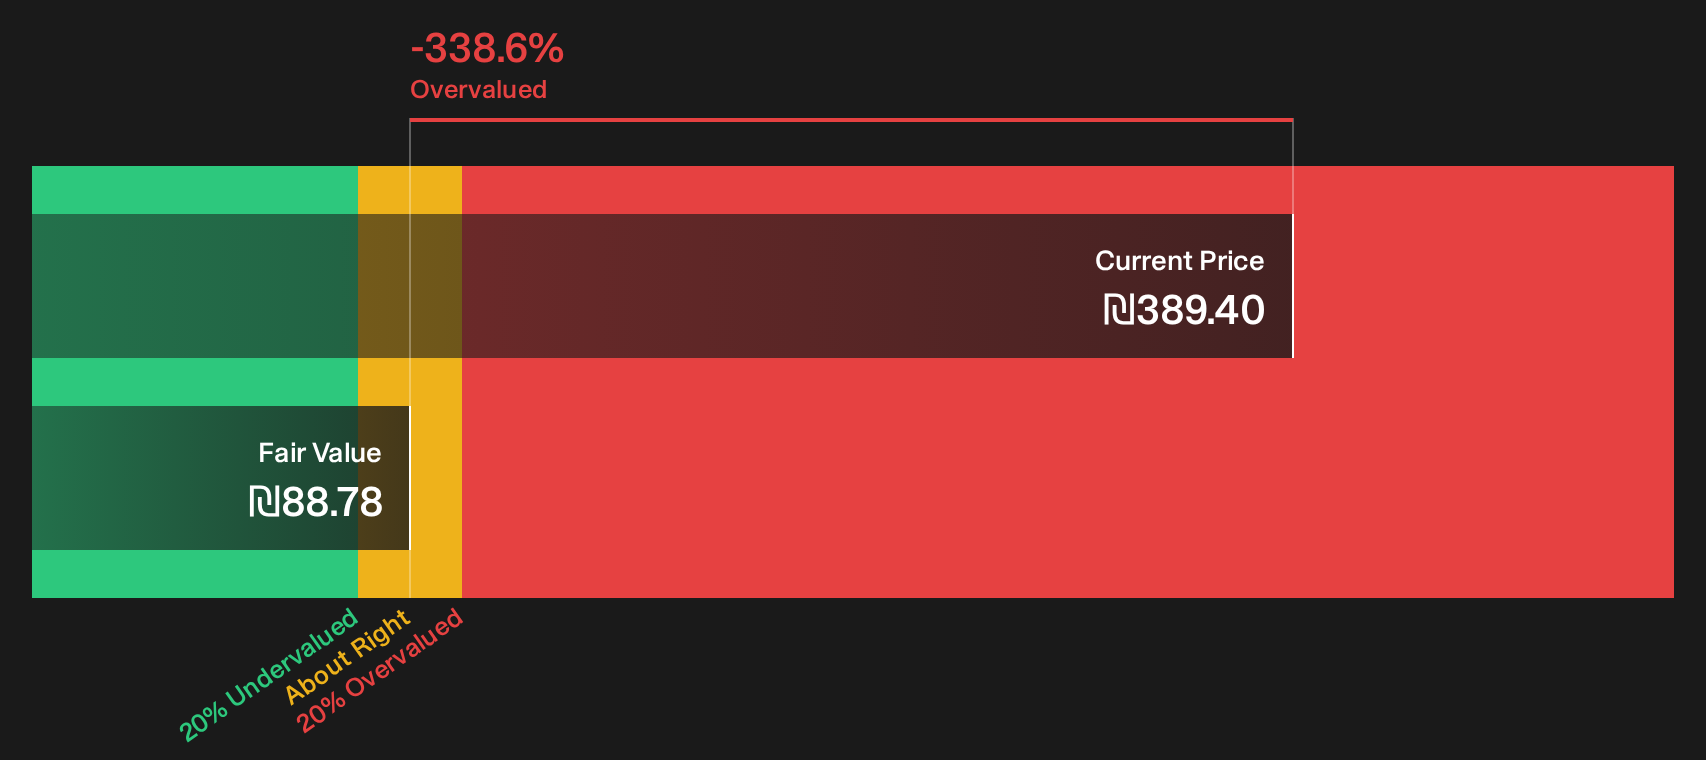
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Azrieli Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 183 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment around Azrieli Group looking stretched on valuation yet backed by solid historical returns, it makes sense to test the data yourself and move quickly to a clear view that fits your risk tolerance. To weigh both the concerns and the potential rewards in one place, start by reviewing the 2 key rewards and 2 important warning signs
Looking for more Azrieli Group sized opportunities?
If Azrieli Group has sharpened your focus on valuation and quality, using a targeted screener can help you spot the next idea before the crowd.
- Chase quality at a discount by scanning a curated set of 183 high quality undervalued stocks that pair solid fundamentals with prices that still look restrained.
- Strengthen your portfolio’s foundation by zeroing in on a list of solid balance sheet and fundamentals (194 results) that can better handle shocks and funding pressures.
- Get ahead of the crowd by reviewing a 619 high quality undiscovered gems list where smaller, under-followed businesses already show strong underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com