
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Is Starwood Property Trust (STWD) Getting Fresh Attention Now?
Starwood Property Trust (STWD) trades around $15.62 after a stretch of weaker share performance, with the stock down over the past month, the past 3 months, year to date, and over the past year.
For Starwood Property Trust, the share price has drifted lower in recent months, with a 7-day share price return of down 2.86% and a 30-day share price return of down 4.17%. The 1-year total shareholder return has declined 15.13%, while 3-year and 5-year total shareholder returns of 0.41% and 2.19% suggest only modest long run progress and fading momentum.
Spot similar ideas by scanning a hand picked 6 dividend fortresses that, like Starwood Property Trust, focuses on income and resilience rather than short term share price moves.Starwood Property Trust now trades at a meaningful discount to published analyst targets after a soft stretch for the share price. Is that a genuine valuation gap, or a fair warning sign about risk?
Most Popular Narrative: 22.9% Undervalued
On the most followed view, Starwood Property Trust’s fair value of $20.25 sits well above the last close at $15.62, which puts the recent share price slide in a different light for investors weighing income against perceived risk.
The acquisition and ramp-up of the net lease portfolio (Fundamental Income), combined with ongoing infrastructure lending growth, position Starwood to generate high-quality, durable earnings streams across a more diversified asset base, supporting both net margin expansion and greater earnings consistency.
Read the complete narrative. Read the complete narrative.
Want to see what kind of revenue mix, profit margin reset, and future earnings multiple are baked into that $20.25 fair value for Starwood Property Trust? The most followed narrative leans on aggressive top line expansion, a slimmer margin profile, and a higher future P/E than the wider mortgage REIT peer group. Curious how those three moving parts fit together in the cash flow model and whether they line up with your own expectations for the business.
Result: Fair Value of $20.25 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Starwood Property Trust story can shift quickly if credit issues in its commercial real estate book deepen, or if funding from capital markets becomes more constrained.
Find out about the key risks to this Starwood Property Trust narrative.
Another View: Multiples Paint A Very Different Picture For Starwood Property Trust
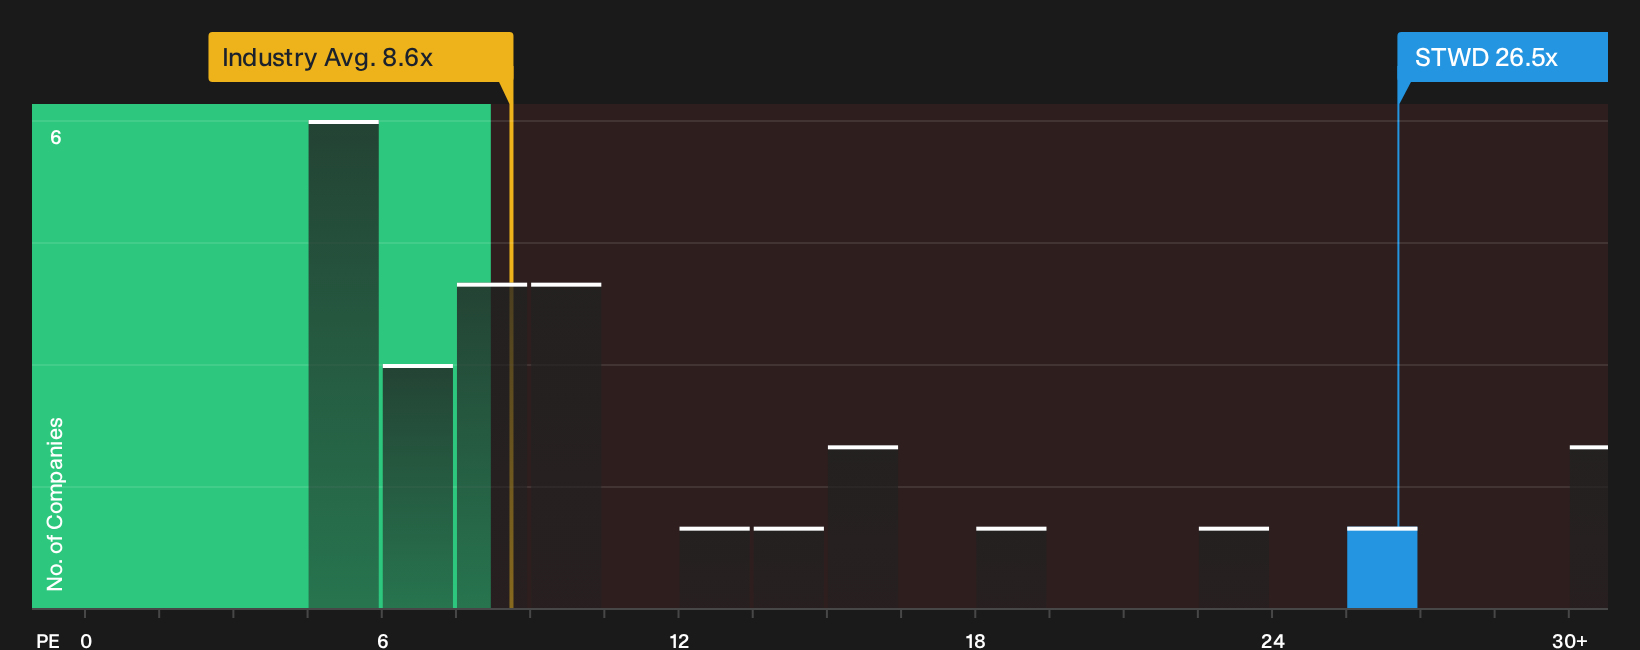
On a simple earnings yardstick, Starwood Property Trust looks far less forgiving. The stock trades on a P/E of 26.5x, compared with 8.6x for the US Mortgage REITs group and a fair ratio estimate of 18.2x, which points to valuation risk rather than a clear bargain. So how much weight do you want to give this richer earnings tag versus the 22.9% undervalued narrative?
Before leaning on that premium P/E, it helps to see how the earnings valuation compares visually against peers and the modelled fair ratio. This can help you decide whether the gap feels justified or stretched for your own risk tolerance. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Starwood Property Trust can feel confusing, so move quickly, check the underlying data for yourself, and pressure test the bullish and cautious arguments side by side using our 2 key rewards and 4 important warning signs.
Looking for more ideas beyond Starwood Property Trust?
If the mixed messages around Starwood Property Trust leave you wanting a wider opportunity set, use curated screeners to spot fresh candidates that match your playbook.
- Target potential mispricing across the market by scanning a focused pool of 32 high quality undervalued stocks that combine quality fundamentals with compressed expectations.
- Zero in on stability and capital strength by reviewing a list of solid balance sheet and fundamentals (23 results) that can help anchor your portfolio when sentiment turns uneasy.
- Get ahead of the crowd by tracking a 15 high quality undiscovered gems that may not be widely followed but already show solid financial underpinnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com