
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Elbit Systems (TASE:ESLT) Rebrands Its US Arm, Is The Stock Below Fair Value?
Elbit Systems (TASE:ESLT) has been in focus after its U.S. operating arm adopted the new Twenty-Six Defense brand, a move paired with new ISR contracts and unusually active options trading.
Recent moves have been upbeat for Elbit Systems, with a 1-day share price return of 2.61% and a 7-day gain of 5.06%. However, the 30-day and 90-day share price returns are down 3.35% and 6.28%. This contrasts with a 19.80% year-to-date share price return and 1-year and 5-year total shareholder returns of 34.53% and 390.40%, which point to long-running momentum supported by the latest ISR wins and the Twenty-Six Defense rebrand.
Compare Elbit Systems with a curated group of defense and security peers by running the 99 resilient stocks with low risk scores that highlights resilient operators with stronger risk profiles and sturdier balance sheets.
Elbit Systems now trades well below analyst targets after a sharp run in recent years and a softer 3 month patch. Is that discount a simple bargain, or a warning the market is sending for good reason?
Most Popular Narrative: 24.8% Undervalued
Elbit Systems closed at ₪2,231, while the most followed narrative pegs fair value at ₪2,965.32, framing the recent pullback as a discount to its long term contract story.
Record $25.2 billion backlog, with close to 70 percent from customers outside Israel and multi year contracts such as the 8 year, $2.3 billion strategic program, provides high visibility on sustained top line growth and supports operating leverage and earnings compounding.
Investors may wish to consider what this backlog could imply for Elbit Systems' future earnings power and valuation multiples. The narrative focuses on compounded margins and steady double digit top line expansion.
Result: Fair Value of ₪2,965.32 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Elbit Systems story can break if defense budgets cool, or if high power laser and directed energy projects fail to win broad adoption.
Find out about the key risks to this Elbit Systems narrative.
Another View: Elbit Systems Through The SWS DCF Lens
There is a sharp contrast once Elbit Systems is run through the SWS DCF model. The DCF output points to a fair value of about ₪995.40 per share, which sits well below the current price of ₪2,231 and frames the stock as expensive on this cash flow view. That gap raises a simple question for you as an investor: Which story feels more realistic, the narrative based on long term contracts, or the cash flows implied by this model?
To understand how this cash flow view is built and which assumptions matter most for Elbit Systems, Look into how the SWS DCF model arrives at its fair value.
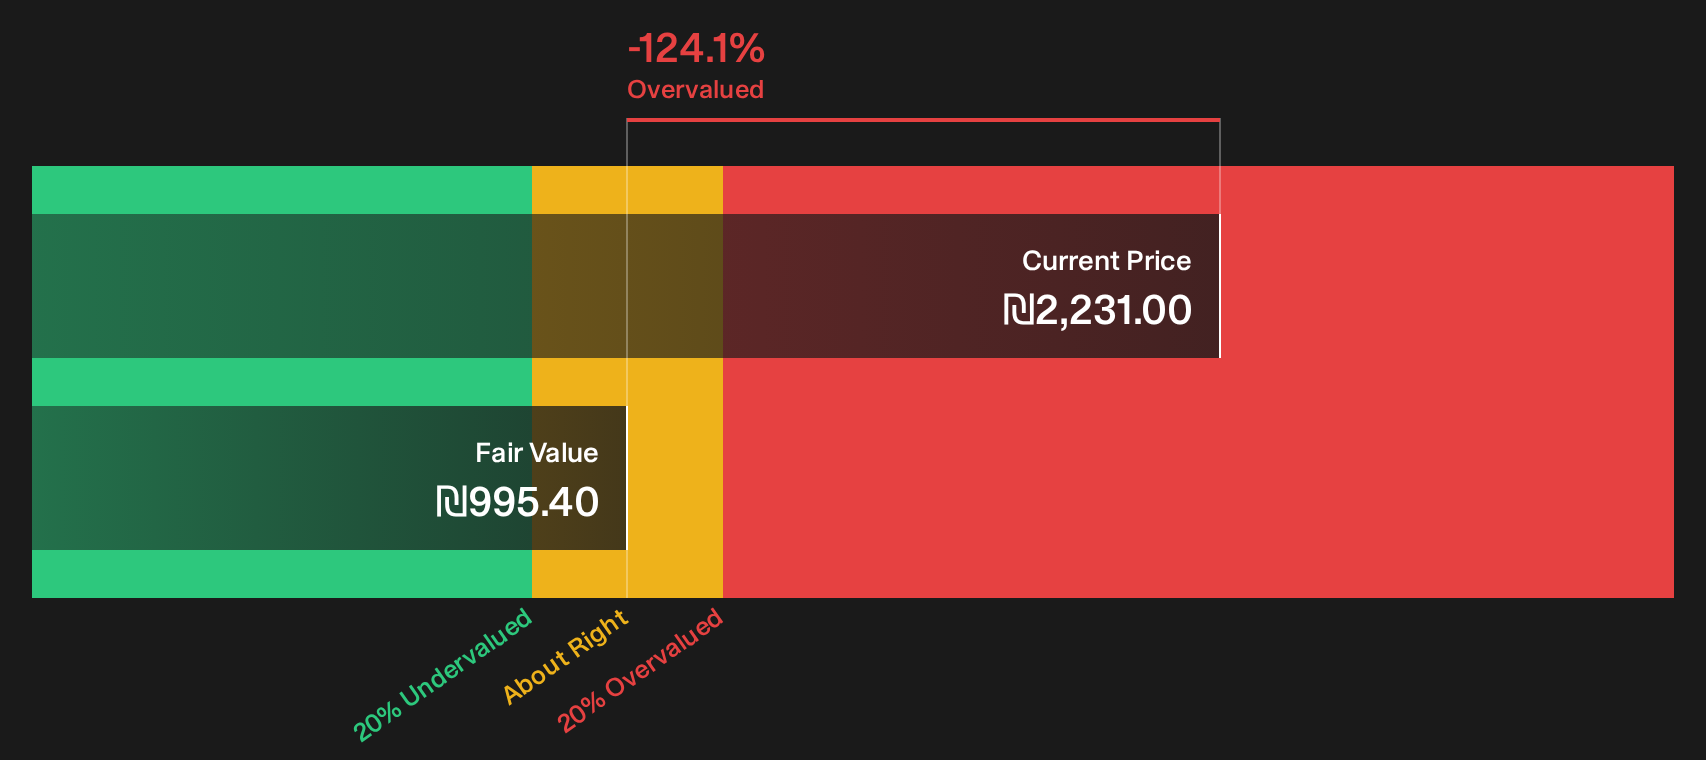
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Elbit Systems for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 183 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Elbit Systems can leave the picture feeling blurred, so pull up the data, stress test the assumptions, and weigh the 2 key rewards.
Looking for more ideas beyond Elbit Systems?
Do not stop with a single defense stock when the screener can surface fresh opportunities across quality, income, and resilience that might fit your portfolio even better.
- Target undervalued opportunities that pair solid fundamentals with a possible margin of safety by scanning the 183 high quality undervalued stocks.
- Build a steadier income stream by hunting for reliable payers through the 161 dividend fortresses.
- Protect your downside by focusing on balance sheet strength with the list of solid balance sheet and fundamentals (194 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com