
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Marriott International (MAR), What Is Behind The Fresh Attention?
Marriott International (MAR) is back in focus after Spotnana launched a direct integration with the hotel operator’s central reservation system, giving corporate clients real-time access to rates, inventory, and Marriott Bonvoy loyalty linking.
Recent price action hints at a pause in momentum for Marriott International, with a 30-day share price return down 6.18% and a 90-day share price return down 16.46%, even as the 1-year total shareholder return of 26.63% and 5-year total shareholder return of 142.61% reflect a materially stronger longer-term story that this new Spotnana integration now feeds into on the corporate and small business side.
Scan what Marriott International’s tech partnerships could be hinting at for travel and hospitality more broadly by comparing it with 15 high quality undiscovered gems in the same space.
Marriott International now trades at a discount to analyst targets even after a double digit pullback. Is that price gap compensating you for fresh risk, or reflecting market caution that still makes sense?
Most Popular Narrative: 12.1% Undervalued
Marriott International closed at $334.69, while the most followed narrative pegs fair value at $380.83, using an 8.78% discount rate and long-run earnings assumptions to bridge that gap.
Global expansion continues to accelerate, with net rooms growth approaching 5% and a record pipeline (over 590,000 rooms, 40% under construction), reflecting strong demand for Marriott's brands in international markets, particularly APAC and EMEA, where a rising middle class is driving double-digit RevPAR increases; this provides a foundation for multi-year revenue growth.
Read the complete narrative. Read the complete narrative.
Curious what justifies that higher fair value on Marriott International? The narrative leans heavily on aggressive revenue compounding, slimmer margins, and a richer future earnings multiple than the broader hospitality sector. The exact mix of those three ingredients is where the valuation story gets interesting.
Result: Fair Value of $380.83 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Marriott International narrative can crack if heavy technology spending fails to pay off or if regional RevPAR softness, especially in Greater China, lingers longer than analysts expect.
Find out about the key risks to this Marriott International narrative.
Another View: Marriott International Through The P/E Lens
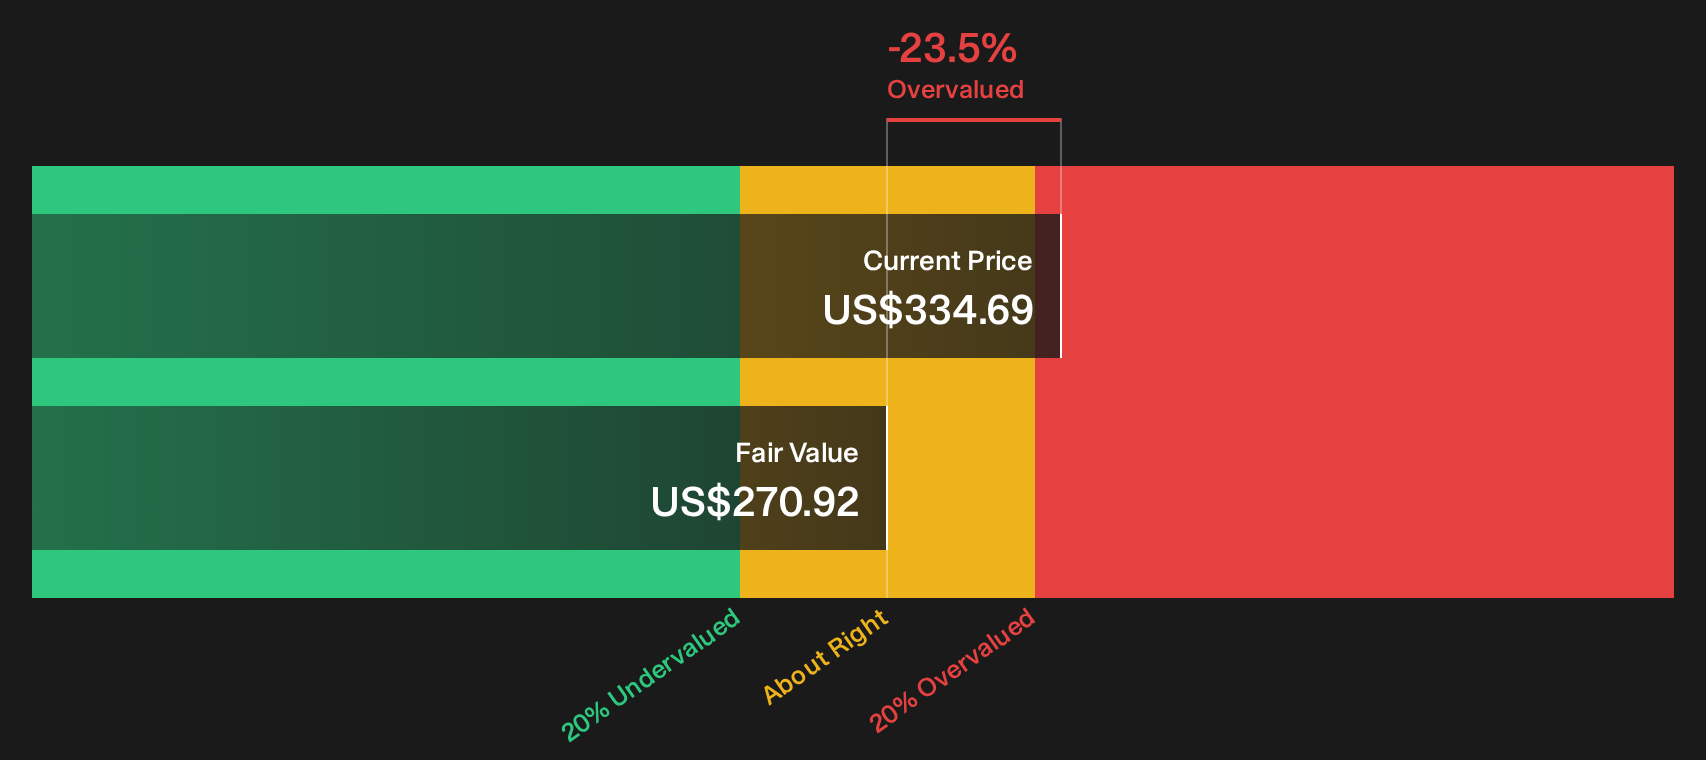
The SWS DCF model suggests Marriott International is overvalued at $334.69 compared with an estimated future cash flow value of $270.92. Within that framework, the earlier 12.1% undervalued narrative looks generous and raises a blunt question for you: Which story about $MAR$ feels more realistic?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on Marriott International so far. Use that tension as a prompt to move quickly, review the underlying data, and weigh the 2 key rewards and 1 important warning sign.
Ready for more investment ideas beyond Marriott International?
Do not stop with one opportunity. Broader context across sectors and styles can sharpen how you judge Marriott International and any future additions to your portfolio.
- Chase potential upside in smaller companies by reviewing the 21 elite penny stocks with strong financials that meet disciplined financial filters and clear quality checks.
- Target value oriented opportunities by screening for companies trading below estimated worth through the 32 high quality undervalued stocks tailored to robust fundamentals.
- Prioritize resilience and balance sheet strength by working through the list of solid balance sheet and fundamentals (23 results) so cash rich, lower risk profiles are on your radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com