
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
International Seaways (INSW) Stock Looks Strong On Cash Flow Yet Fair On Earnings
International Seaways has produced very strong long term returns, yet a fresh Discounted Cash Flow (DCF) estimate still points to the stock trading at a sizeable discount to its calculated intrinsic value while more traditional market multiples look roughly in line with peers. That mix leaves investors weighing a price that already reflects a big track record against models that still see room between the current quote and underlying cash flow estimates.
- Over the past 5 years, International Seaways has delivered a very large total return. This means anyone buying today is coming in after a powerful run.
- The company’s ability to keep converting shipping capacity into steady cash generation can support the DCF case. At the same time, exposure to tanker rates and potential swings in operating costs may limit how confidently investors can rely on those projected cash flows.
- The broader valuation checks paint a mixed picture rather than a clear bargain or clear overvaluation, with the stock scoring 4 out of 6 on value tests.
The issue now is whether International Seaways’ current share price already reflects that very strong track record or still leaves meaningful room versus the intrinsic value estimate implied by its projected cash flows.
Scan beyond International Seaways and evaluate other potential value plays with strong cash generation profiles inside 32 high quality undervalued stocks
Is International Seaways Still Cheap on Cash Flow?
The Discounted Cash Flow valuation looks at the cash International Seaways can generate for shareholders and then discounts it back to today. On this model, the business is producing latest twelve month free cash flow of about $320.9 million in $ and the forecast assumes a broadly steady to modestly growing cash generation profile rather than a surge or collapse.
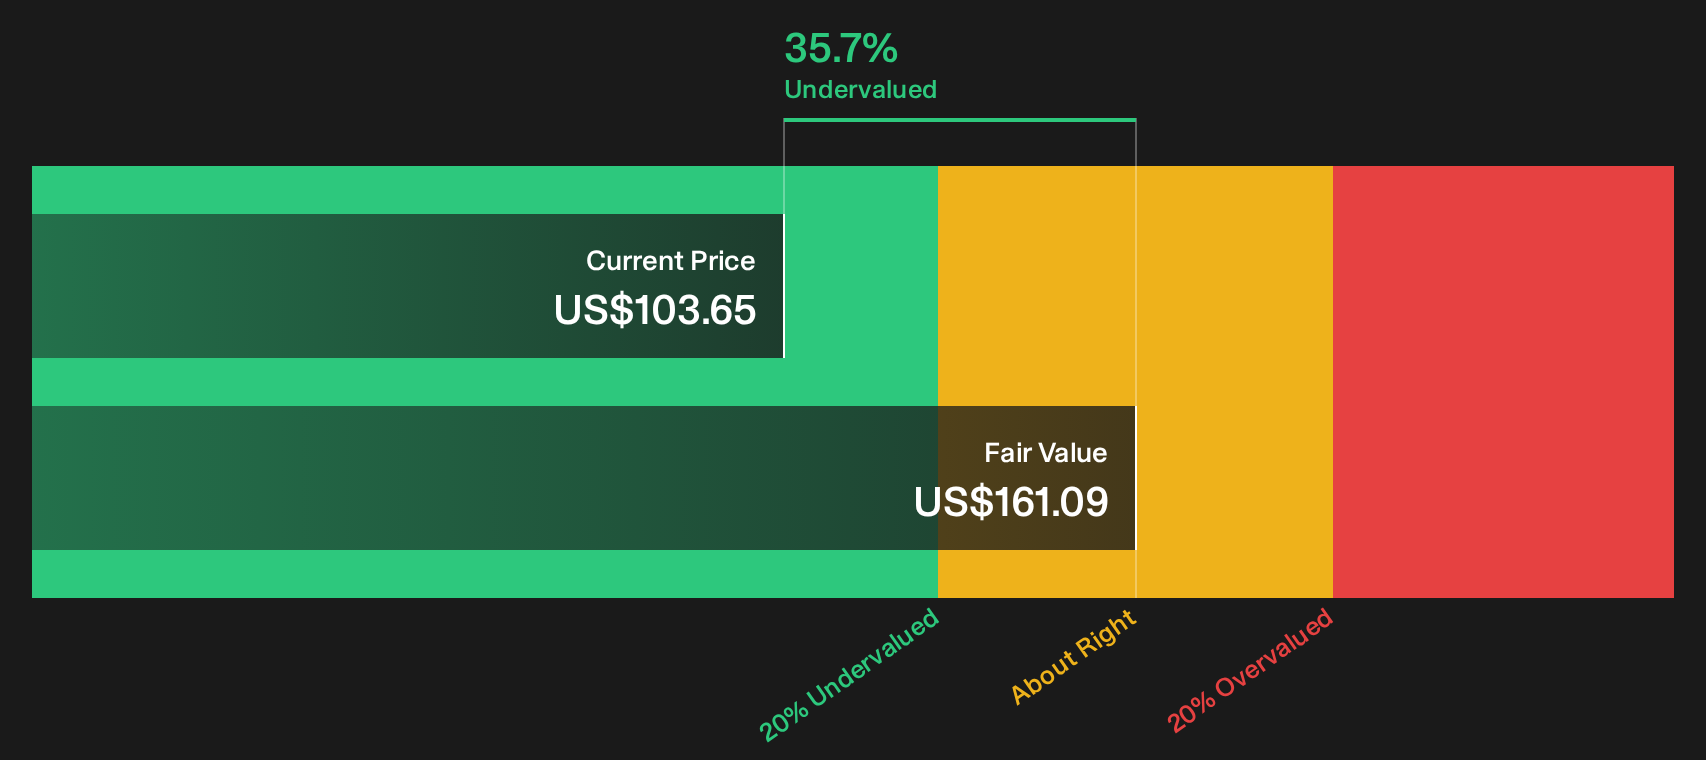
Feeding those projections into the 2 Stage Free Cash Flow to Equity model produces an estimated intrinsic value of about $161 per share. Compared with the current share price, that implies an intrinsic discount of roughly 35.7%, so the stock screens as undervalued on this cash flow view even after its strong historical run.
On this Discounted Cash Flow view, International Seaways appears undervalued relative to the cash the business is expected to generate.
Our Discounted Cash Flow (DCF) analysis suggests International Seaways is undervalued by 35.7%. Track this in your watchlist or portfolio, or discover 32 more high quality undervalued stocks.
Does International Seaways Look Fairly Valued on Earnings?
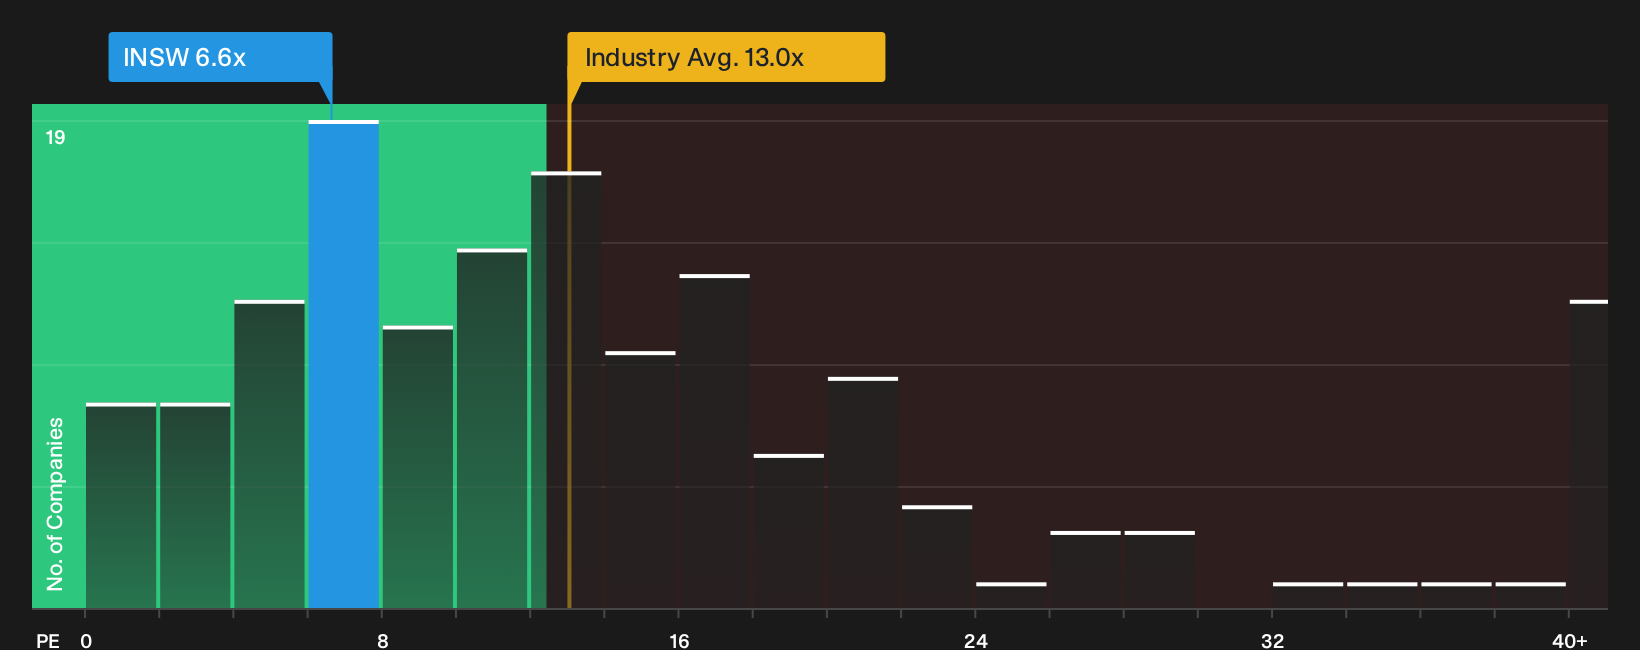
The P/E ratio fits International Seaways well because earnings capture how effectively the fleet turns day rates into bottom line profit. On this measure, the shares trade on about 6.6x earnings compared with an oil and gas sector average of roughly 13.0x and a broader peer group closer to 14.3x. That headline discount can look appealing, especially after the strong run already in the rear-view mirror.
A more tailored check uses a fair P/E of about 6.4x that blends the company’s risk profile, profitability and sector context. Against that lens, International Seaways only trades slightly above the implied level, so the gap is small enough that it does not appear clearly cheap or clearly expensive. For investors, the message is that the current P/E leaves the stock looking broadly in line with what the fundamentals and sector backdrop would justify.
On the P/E yardstick, International Seaways comes across as roughly fairly valued rather than clearly cheap or clearly expensive.
See what the numbers say about this price — find out in our valuation breakdown.
The International Seaways Narrative: What Would Justify Today's Price?
Narratives for International Seaways pick up where the valuation puzzle leaves off and explain what assumptions on future growth, profitability and earnings would need to come true for the shares to be worth materially more or materially less than today’s price on Simply Wall St’s Community page. Each scenario links its number to a clear stance on how International Seaways' revenue potential, margins and key risks might change, which you can revisit as fresh information becomes available.
Community views on International Seaways are split between a margin focused upside story and a caution that expectations are already baking in a lot.
Bull case: 14% undervalued
"International Seaways is rapidly establishing a first-mover advantage in the transport of alternative and lower-carbon fuels by investing in dual-fuel-ready and flexible vessel designs..."
Read the full Bull Case to see why International Seaways could be undervalued
Bear case: roughly fairly valued
"Heavy reliance on spot market exposure in a secularly volatile and potentially declining tanker market could lead to significant fluctuations and eventual declines in revenues and cash flows..."
Read the full Bear Case to see why International Seaways could be overvalued
Do you think there's more to the story for International Seaways? Head over to our Community to see what others are saying!
The Bottom Line
International Seaways screens as undervalued on a Discounted Cash Flow (DCF) view, while the P/E work suggests the share price is roughly in line with sector expectations. That split partly reflects an extreme recent move that can pull market multiples away from what long term cash generation implies. For you, the real question is whether tanker earnings and cash flows stay resilient enough for that intrinsic value gap to matter, or whether rate volatility and cost swings keep the equity trading closer to its current multiple. The crux of the bull versus bear debate is how durable the company’s cash engine proves through the next shipping cycle.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com