
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
California Water Service Group (CWT) Stock Looks Fully Priced With Fair Earnings But Rich Dividends
California Water Service Group has delivered a solid 12.3% gain year to date, yet the stock screens as expensive on broader valuation checks, with an intrinsic value estimate from a Dividend Discount Model suggesting a premium to what the underlying dividends may justify. At the same time, traditional multiples look roughly in line with peers, which puts more weight on how reliably the utility can grow and secure future cash flows.
- Year to date, California Water Service Group is up 12.3%, which means investors are already paying more today for every dollar of regulated water earnings than they were at the start of the year.
- Recent rate case activity in Washington and Hawaii can support future revenue, while the timing and outcome of these regulatory decisions may limit how quickly the business can translate investment into higher cash flows.
- On an aggregate view, California Water Service Group scores 1 out of 6 on value checks, which points to a stock that leans expensive rather than a clear bargain.
The issue now is whether California Water Service Group’s current share price already reflects the value of its regulated rate decisions and dividend stream, or if there is still room for a more attractive entry point.
Scan beyond California Water Service Group and compare its premium valuation with 32 high quality undervalued stocks, which the broader market may be pricing more conservatively.
Is California Water Service Group Getting Expensive on Dividends?
The Dividend Discount Model looks at what California Water Service Group might be worth based on today’s dividend and how steadily that payout can grow. For this utility, the model leans heavily on a measured growth path rather than aggressive expansion.
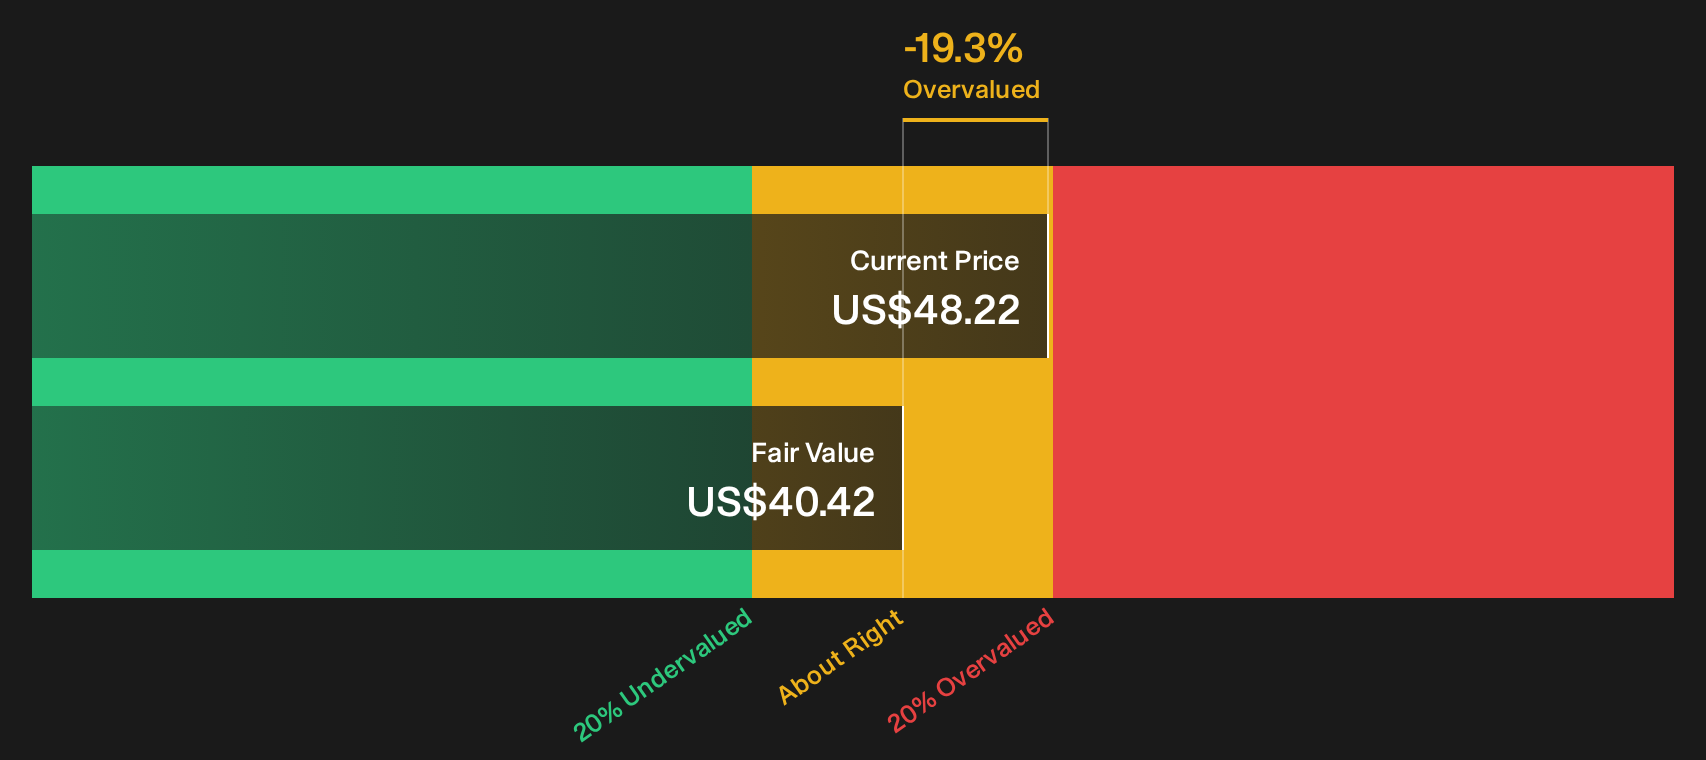
California Water Service Group currently pays an annual dividend of about $1.43 per share, backed by a return on equity near 8.1% and a payout ratio around 53%. The DDM uses a capped dividend growth rate of roughly 3.7%, which implies modest, ongoing increases without stretching the balance sheet. On these assumptions, the model arrives at an intrinsic value of about $40 per share, which is below the current market price and indicates the stock screens as overvalued by roughly 19.3%. The recent Washington rate decision that lifts future regulated revenue helps support the dividend story, yet the share price already reflects much of that benefit.
On this dividend-based view, California Water Service Group currently appears overvalued relative to what its projected payouts support.
Our Dividend Discount Model (DDM) analysis suggests California Water Service Group may be overvalued by 19.3%. Discover 32 high quality undervalued stocks or create your own screener to find better value opportunities.
Does California Water Service Group Look Fairly Valued on Earnings?
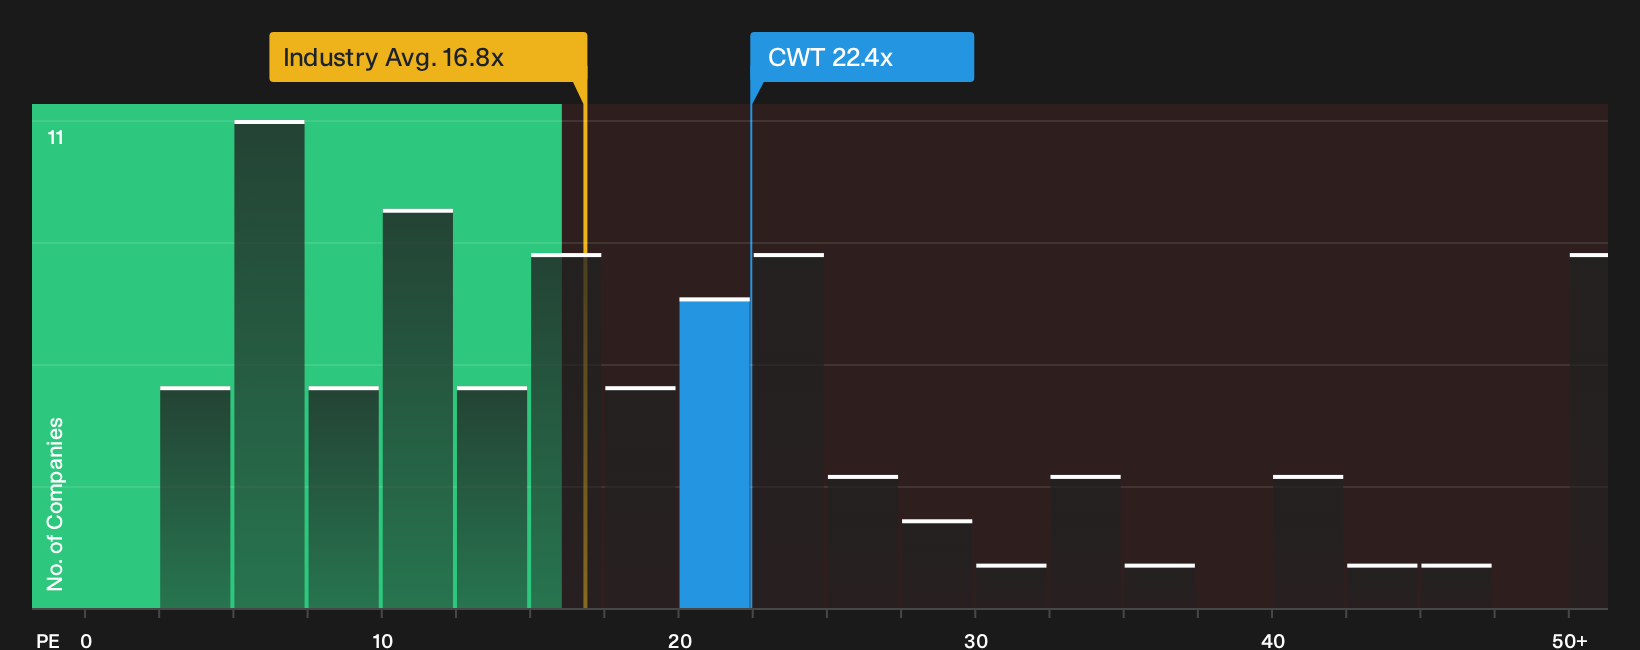
P/E works well for California Water Service Group because earnings are driven by regulated returns that tend to be relatively steady for a utility. On this basis, the stock trades at about 22.4x earnings, which is very close to the peer average of 23.0x and well above the wider water utilities group on roughly 16.8x. That premium to the broader industry suggests investors are treating California Water Service Group more like its direct peers than the sector as a whole.
The fair multiple implied by Simply Wall St’s model is about 21.7x. That sits only slightly below the current P/E, so the gap is small and does not indicate a clear discount or overvaluation. In this context, the present valuation on earnings appears broadly aligned with what the company’s profile and risk level might justify.
On the P/E metric, California Water Service Group stock appears roughly fairly valued compared with its tailored fair multiple and close peer group.
See what the numbers say about this price — find out in our valuation breakdown.
The California Water Service Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for California Water Service Group pick up where the valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to unfold for the shares to be worth materially more or less than today’s price, and how those paths compare with what is currently implied. Each scenario links a grounded fair value to a specific mix of potential catalysts and risks, so you can track over time which version of California Water Service Group's story is actually taking shape.
Share a narrative on California Water Service Group that puts real numbers around whether decisions like the Washington revenue approval or the Hawaii rate request truly support today’s valuation. Add your view, connect it to a clear case, and track how it holds up as new rulings and results arrive.
Do you think there's more to the story for California Water Service Group? Head over to our Community to see what others are saying!
The Bottom Line
California Water Service Group screens as overvalued on the Dividend Discount Model (DDM), while the P/E view points to a stock that is priced about right relative to similar utilities. That split largely comes down to how much trust you put in longer term dividend growth versus what the market is currently willing to pay for steady, regulated earnings. The key judgment from here is whether future rate decisions and cash flow timing justify paying up for that reliability or whether patience for a better entry price is more sensible for your own risk tolerance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com