
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Carter's (CRI) Monster Sleepwear Launch
- Carter's recently launched the Not-So-Scary Monsters sleepwear and playwear collection for babies through big kids, priced from $7 to $28, supported by an interactive Monster Room Scanner in the Carter's app.
- The collection ties product design directly to bedtime routines, which could influence repeat purchases and deepen engagement across Carter's direct-to-consumer channels.
- This analysis reviews how Carter's investment narrative is shaped by this character-led sleepwear launch and the new app feature.
Scan Carter's Not-So-Scary Monsters launch alongside other kid focused apparel plays by sizing up a curated list of 15 high quality undiscovered gems that may still be flying under the radar.
Carter's Investment Narrative Recap
To own Carter's, you need to believe the childrenswear specialist can keep translating its brand reach and baby strength into steady cash generation even as birth rates soften and earnings are forecast to decline 17.4% a year over the next 3 years. The key near term swing factor is execution on product and channel, not headline growth.
The Not So Scary Monsters launch fits cleanly into that story but does not look like a material catalyst on its own. It supports the existing push into direct digital engagement via the app. The bigger near term risk remains margin and earnings pressure from tariffs, competition, and slower end demand.
The most relevant backdrop for this sleepwear drop is Carter's broader push into brand innovation and digital expansion. The Monster Room Scanner inside the Carter's app leans into that same direction, using content and characters to keep families inside the company’s own ecosystem instead of relying solely on wholesale partners.
For catalysts, the question is whether launches like Not So Scary Monsters actually move the needle on direct to consumer sales, loyalty usage, and merchandising productivity. If these character led collections drive better mix and higher repeat purchases, they could help offset slower category growth and support the firm’s efforts to manage cost and sourcing pressures.
Carter's Medium Term Expectations Behind The Monsters Push
Carter's narrative projects US$3.1b revenue and US$134.4m earnings by 2029. This is based on analysts assuming 1.9% yearly revenue growth and about a US$46.2m earnings increase from US$88.2m today.
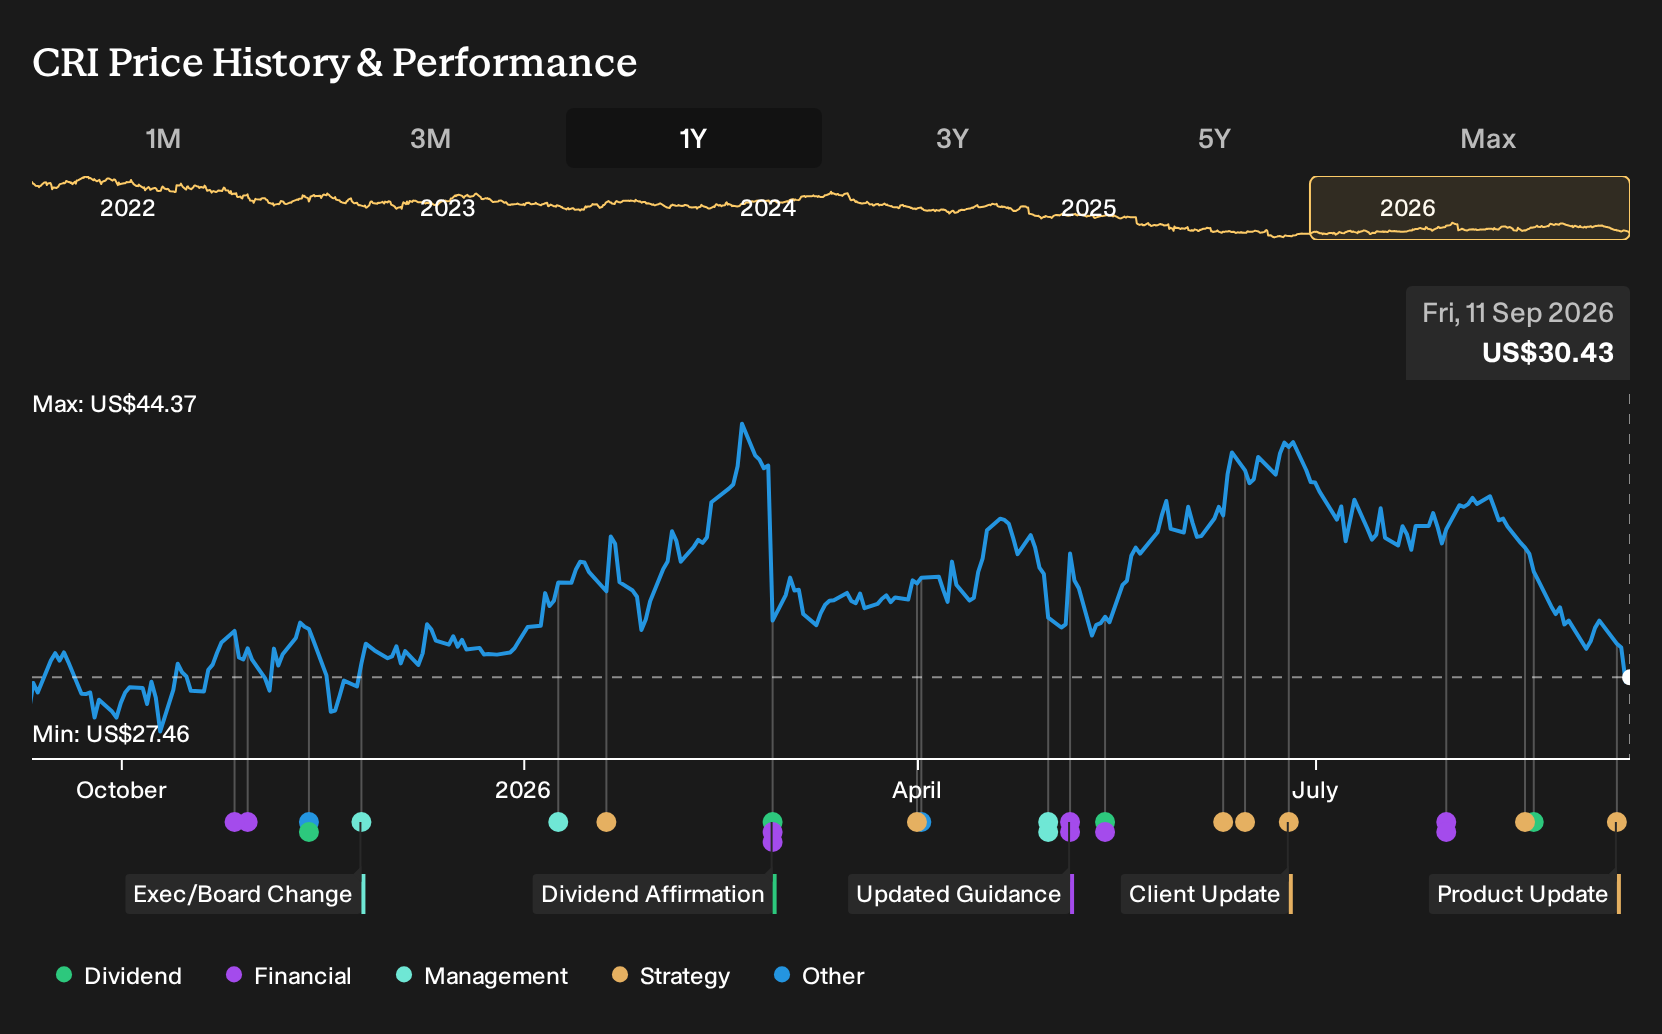
Uncover why Carter's fair value indicates a 40% potential upside to its current price that could narrow quickly as sentiment around Carter's shifts.
Exploring Other Perspectives
Some of the most optimistic Carter's analysts already penciled in about US$3.2b in revenue and US$127.8m in earnings by 2029, before this Monsters launch even surfaced. Those forecasts lean on stronger digital traction and productivity gains. If you see this character led push differently, consider how far your own view sits from theirs.
Explore 2 other Carter's fair value estimates, including one that suggests as much as 45% potential increase from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Carter's research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Carter's. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Carter's overall financial health at a glance.
Looking For More Investment Ideas Beyond Carter's?
Once you have a view on Carter's, it can help to widen the lens and see how other businesses with different drivers stack up side by side using the Simply Wall St Screener.
- If capital preservation sits high on your list, weigh up companies flagged in our 11 resilient stocks with low risk scores that focus on more resilient profiles.
- For investors who want quality at a sensible entry point, sort through the 32 high quality undervalued stocks and see which stocks line up with your own valuation work.
- If balance sheet strength matters most to you, review the list of solid balance sheet and fundamentals (23 results) and compare how those businesses manage debt and liquidity.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com