
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
SolarEdge Technologies (SEDG) Reaffirms Guidance, Is The Stock Still Cheap?
SolarEdge guidance and AI data center push put recent move in focus
SolarEdge Technologies (SEDG) just reiterated its third quarter 2026 revenue outlook at US$310 million to US$340 million, while also flagging fresh progress on its 800 VDC powertrain for AI data centers.
That guidance lands after a sharp reset in sentiment. SolarEdge Technologies shares fell 5.63% in the latest session, yet the 30-day share price return of 6.97% contrasts with a much steeper 90-day share price decline of 42.38% and a 3-year total shareholder return that is down 75.28%. This points to a stock where short-term momentum has picked up slightly even as the longer-term record remains weak and investors continue to reassess both risk and the potential impact of the AI data center push.
Spot under-the-radar peers moving on the same AI infrastructure theme by scanning our 89 AI infrastructure stocks alongside SolarEdge Technologies.The recent bounce in SolarEdge Technologies leaves the stock trading below both analyst targets and one intrinsic estimate. Is that a sensible margin of safety, or a value trap given the still-weak long-term track record?
Most Popular Narrative: 9.8% Undervalued
On the latest close, SolarEdge Technologies at $34.68 sits below the widely followed narrative fair value of $38.45. This frames how analysts are weighing policy shifts, storage adoption, and the AI data center angle.
The rally in SolarEdge's stock appears to be pricing in robust future revenue growth driven by U.S. policy support (extension of manufacturing and storage credits), but risks are rising as the elimination of the 25D residential solar tax credit is expected to cause a substantial drop in U.S. residential demand in 2026, only partially offset by third-party owned (TPO) shifts, potentially constraining topline growth.
If that tug of war between policy support, shifting residential demand, and ambitious long term earnings targets is driving a nearly 10% valuation gap, it is worth seeing which revenue path, margin profile, and future P/E assumptions sit under the hood of this SolarEdge Technologies narrative.
Result: Fair Value of $38.45 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the narrative can be knocked off course if U.S. residential demand falls sharply after the 25D credit ends, or if intense pricing pressure squeezes SolarEdge Technologies margins.
Find out about the key risks to this SolarEdge Technologies narrative.
Another View on SolarEdge Technologies Valuation
The story looks different when using the SWS DCF model instead of narrative fair value. On that measure, SolarEdge Technologies at $34.68 trades above an estimated future cash flow value of $28.45, which frames the stock as overvalued and raises a simple question: Which yardstick do you trust when the signals disagree?
Look into how the SWS DCF model arrives at its fair value.
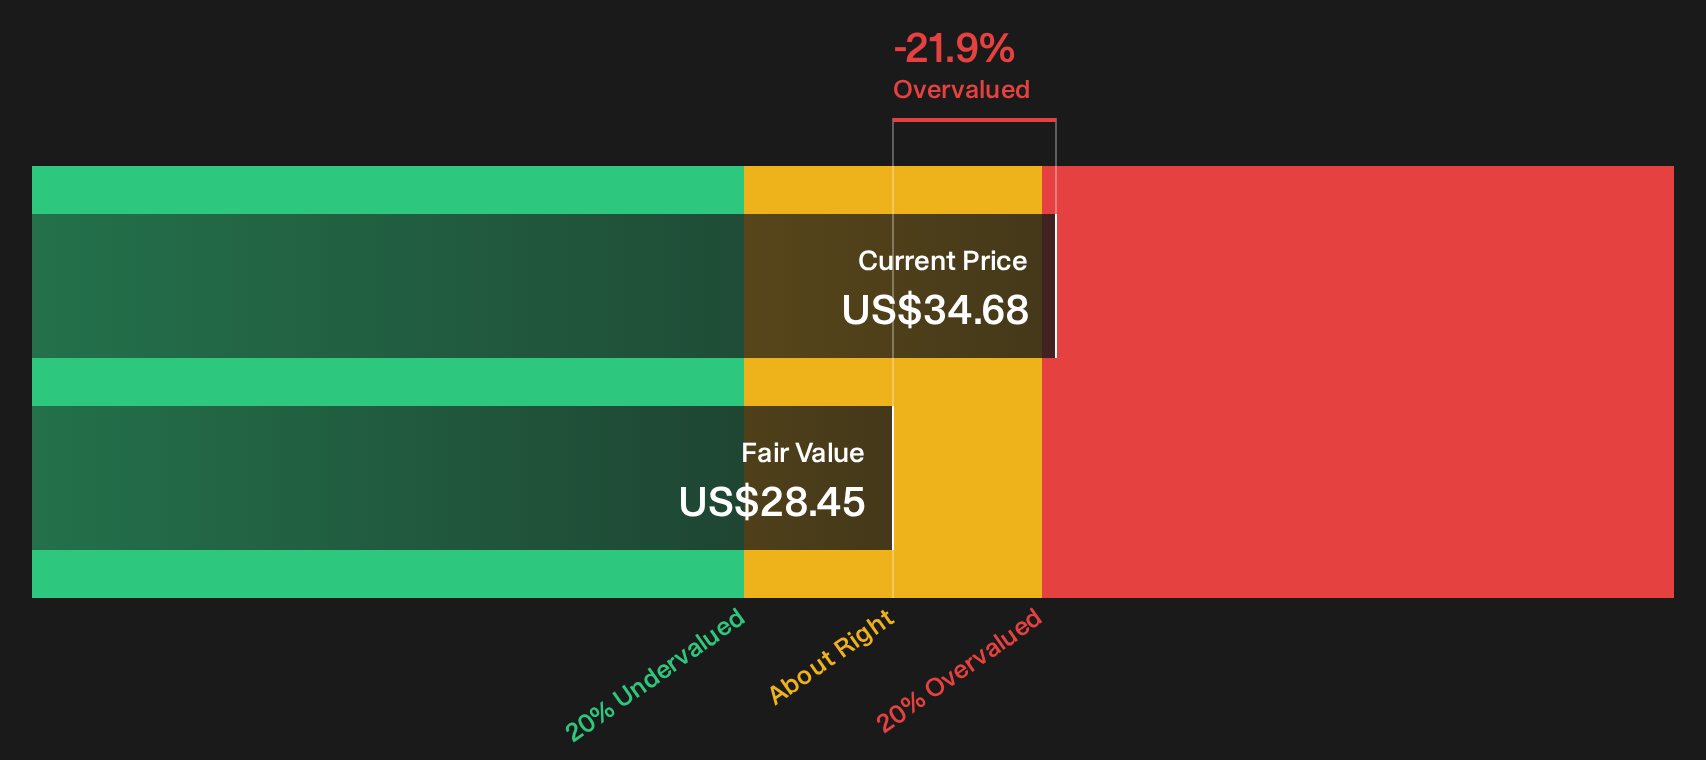
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SolarEdge Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by SolarEdge Technologies looking slightly cheap on one model and expensive on another? Move quickly, review the same inputs, and weigh up the 2 key rewards and 1 important warning sign.
Looking for more SolarEdge ideas and beyond?
If SolarEdge Technologies has you rethinking where the real opportunities are, broaden your watchlist now or risk missing the next move in related themes.
- Target potential mispricings by scanning companies that screen as quality yet underappreciated through our 32 high quality undervalued stocks.
- Prioritize resilience and sleep-at-night holdings by checking out a 11 resilient stocks with low risk scores that filters for sturdier business profiles.
- Spot potential future leaders early by exploring a 15 high quality undiscovered gems that surfaces strong fundamentals before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com