
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
NetApp Stock In Focus After Earnings Beat And Higher Guidance
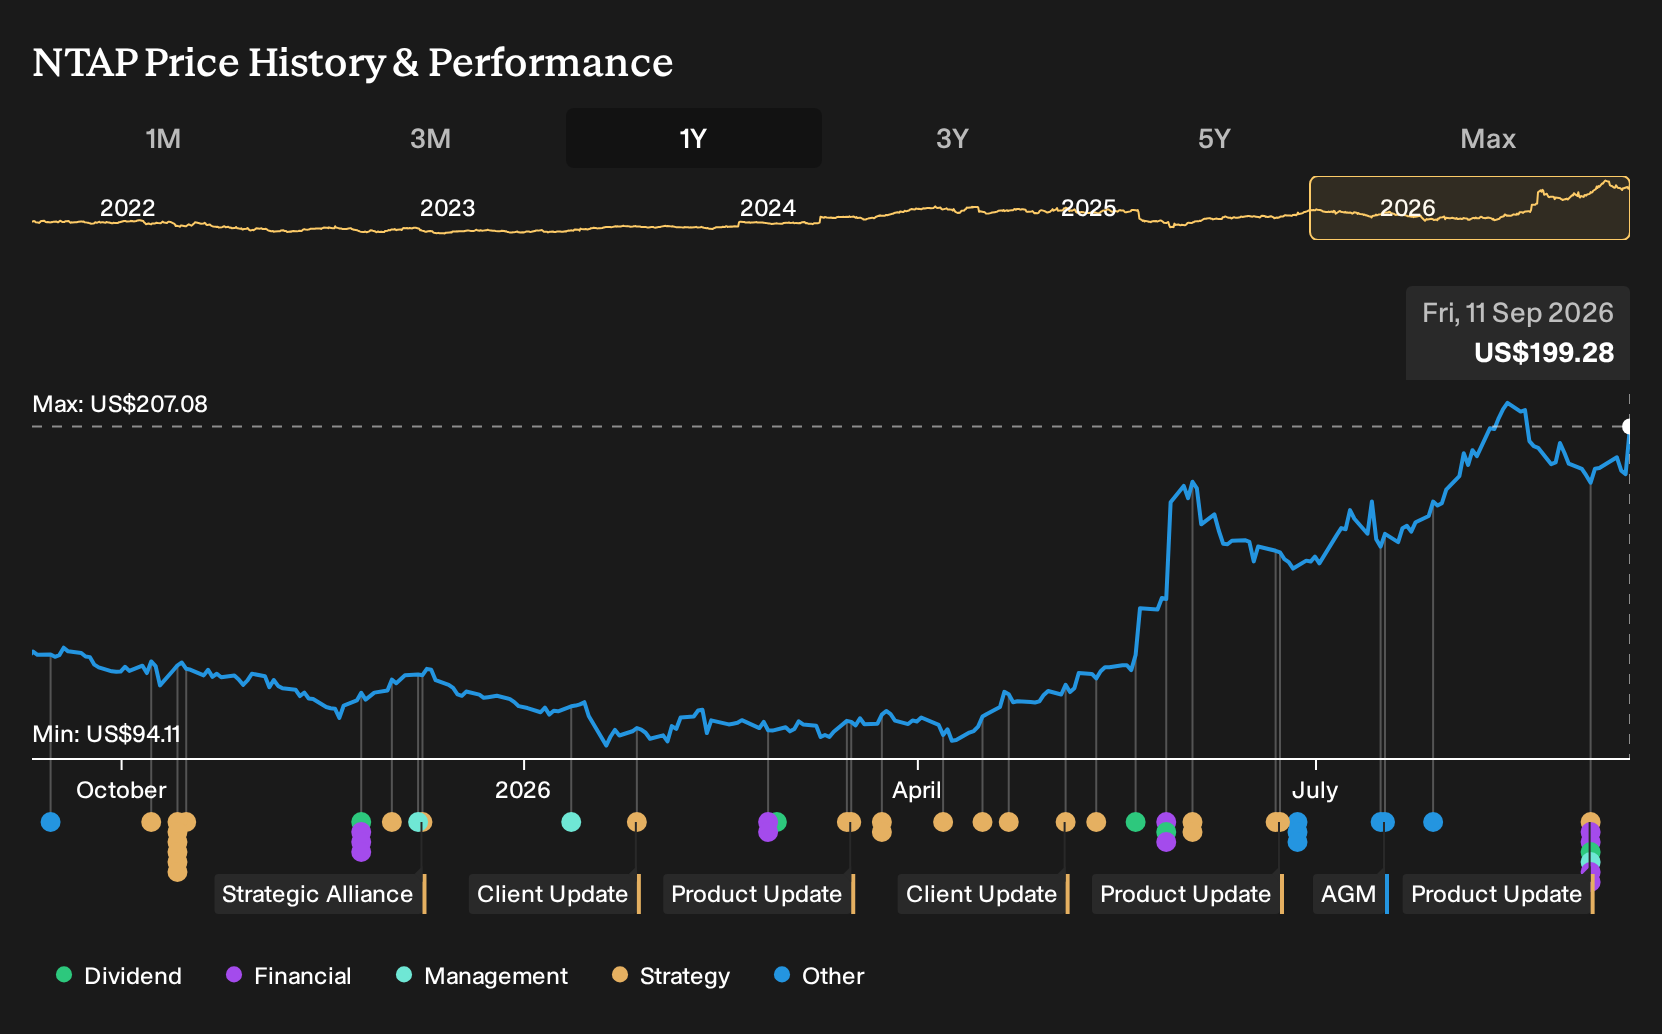
- NetApp reported first quarter revenue of US$2,025 million and net income of US$375 million, raised full year 2027 guidance, confirmed its cash dividend, and rolled out new ONTAP capabilities validated for VMware Cloud Foundation 9.1.
- The combination of higher earnings guidance, expanded VMware Cloud Foundation support, and ongoing share repurchases highlights how NetApp is leaning into AI, hybrid cloud demand, and capital returns while updating its governance framework.
- Next, the focus shifts to how NetApp's stronger full year 2027 guidance could reshape the broader investment narrative around its cloud transition.
Scan how NetApp's AI and hybrid cloud momentum compares with peers by exploring our hand-picked list of 89 AI infrastructure stocks today.
NetApp Investment Narrative Recap
To stay on board with NetApp, you need to believe the business can keep shifting its center of gravity toward AI driven, hybrid and public cloud storage while managing pressure on older on premises hardware. The raised fiscal 2027 guidance reflects management confidence in that mix shift, as well as in execution on cost discipline and cloud partnerships.
At present, the key short term swing factor is whether demand for AI and hybrid cloud workloads supports the higher revenue and EPS guidance through fiscal 2027. A major risk is continued margin and growth pressure if hyperscalers, subscription models and regional softness dilute returns from traditional storage more quickly than NetApp’s cloud and services business can offset.
The governance updates around the amended and restated charter and bylaws matter because they sit behind all of those operating choices. Officer exculpation, clarified indemnification limits, and the explicit link between the meeting chair’s authority and board oversight may affect how NetApp handles future disputes, disclosure decisions and high stakes product or capital allocation decisions.
For an investor watching catalysts, this framework, together with the stronger 2027 guidance and ongoing buybacks, helps shape the overall risk reward profile. The withdrawn written consent proposal also keeps the current avenue for shareholder action unchanged. As a result, near term focus remains on how NetApp executes on AI, VMware Cloud Foundation 9.1 support and public cloud growth, rather than on a change in shareholder rights.
NetApp's current earnings are about US$1.4b and analysts on average expect earnings to reach US$1.9b by 2029. This implies an increase of roughly US$0.5b, while their models assume revenue expands at about 8.1% a year and reaches US$9.3b in 2029.
Uncover why NetApp's fair value indicates a 3% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
Some of the most optimistic analysts focus on NetApp's AI and cloud pipeline as a possible upside catalyst. Before this news, the bullish camp was already modeling revenue of about US$8.6b and earnings near US$1.7b by 2029. You can compare that more upbeat story with the consensus view to see how these governance changes might shift both.
Explore 3 other NetApp fair value estimates, including one that suggests as much as 20% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your NetApp research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for NetApp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NetApp's overall financial health at a glance.
Looking for More Ideas Beyond NetApp?
After forming a view on NetApp, it can help to widen the lens and compare it with other opportunities that match your risk profile, income needs, or preference for balance sheet strength. The Simply Wall St Screener lets you filter for exactly those traits instead of sifting through stocks one by one.
- If you want to focus on resilience first, filter for companies with stronger financial footing by scanning our list of solid balance sheet and fundamentals (23 results).
- For investors who care most about capital preservation and smoother ride potential, start with a 11 resilient stocks with low risk scores that scores well on stability metrics.
- If you prefer to hunt for under-followed opportunities with robust fundamentals, cast a wider net using our 15 high quality undiscovered gems that might not yet be on everyone's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com