
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Novo Nordisk (NVO) Stock Looks Like A Bargain At Current Prices
Novo Nordisk stock has gone through a harsh reset over the past few years, yet the current valuation checks still lean cheap on a broad set of metrics. For investors, the puzzle is whether a share price that has fallen hard is now out of sync with what the underlying business may be worth.
- The share price has declined 51.9% over the past three years, which points to a major reset in expectations that may be out of step with fundamentals if the underlying cash generation holds up.
- Ongoing demand for Novo Nordisk’s treatments can support revenue and profit resilience. At the same time, any sustained pressure on pricing or reimbursement may cap how much value the market is willing to assign to those cash flows.
- The broader checks lean cheap, with Novo Nordisk screening as undervalued on 5 out of 6 valuation measures. You can see this in the value score of 5.
The issue now is whether the current share price already reflects the recent drawdown in Novo Nordisk, or if investors are still paying less than the underlying business is likely to justify over time.
Scan beyond Novo Nordisk and line up other beaten down yet financially solid opportunities with the hand picked 32 high quality undervalued stocks screener.
Does Novo Nordisk Look Undervalued on Earnings?
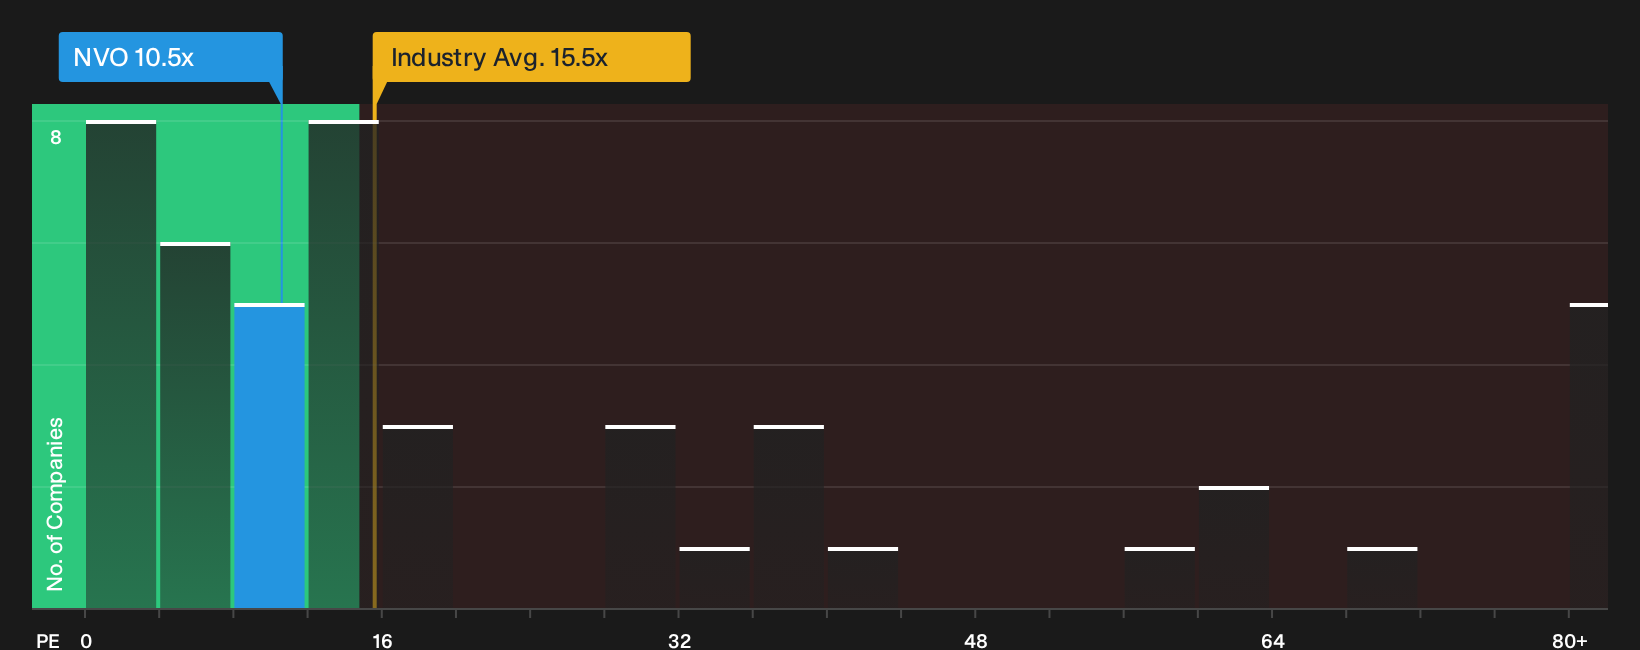
The P/E ratio is a useful shorthand for what investors are willing to pay today for Novo Nordisk’s current earnings power. On that yardstick, Novo Nordisk trades on about 10.5x earnings, which is well below the pharmaceuticals industry average of 15.5x and far under the broad peer group on roughly 48.2x. That is a wide gap for a large, profitable drug maker that still generates substantial free cash flow.
A fair P/E multiple that blends the company’s profitability profile, sector, size and risk comes out closer to 28.8x. Compared with the current 10.5x, the market is assigning Novo Nordisk a sizeable discount to what this framework suggests might be reasonable. For investors, that raises the question of whether concerns already embedded in the share price are overshooting the earnings reality.
On a pure P/E basis, Novo Nordisk stock appears undervalued relative to both its tailored fair multiple and wider pharmaceutical peers.
See what the numbers say about this price — find out in our valuation breakdown.
The Novo Nordisk Narrative: What Would Justify Today's Price?
Novo Nordisk’s share price reset leaves a clear question hanging in the air. What has to be true about Novo Nordisk’s future earnings, growth and margins for today’s valuation gap to close in either direction? Simply Wall St Narratives on the Community page tackle that puzzle by tying each potential outcome to its own fair value, so you can track which mix of catalysts and risks is gradually lining up with reality.
One of the top community narratives on Novo Nordisk: 55% undervalued
"Current sentiment has swung deeply negative, but expectations are now low, and the market appears to assign little to no value to Novo’s development-stage pipeline beyond Wegovy…"
Read one of the top narratives on Novo Nordisk
Do you think there's more to the story for Novo Nordisk? Head over to our Community to see what others are saying!
The Bottom Line
The valuation work on Novo Nordisk points to a stock that still prices in a lot of caution, even though it screens as undervalued on most market multiples. The key question is whether current earnings power and margins can be defended if pricing and reimbursement pressures on its key therapies intensify. If cash generation remains resilient, that discount could eventually look excessive. If pressure on treatment economics proves more persistent, the current gap may simply reflect a business that earns less credit for its future cash flows than in the past.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com