
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Following The Lawsuit Is VeriSign (VRSN) A Bargain Or Fully Priced?
Why the new VeriSign lawsuit matters for investors
A fresh class-action complaint targeting VeriSign (VRSN) and ICANN over .com pricing and alleged monopoly power has put the registry operator’s business model, fee structure, and legal exposure under much closer investor scrutiny.
The lawsuit challenges long standing contracts around .com domains, questions how much VeriSign collects per registration, and raises antitrust claims that could influence future pricing, profitability and regulatory attention if courts or agencies act.
Recent trading suggests investors are still pricing in steady progress at VeriSign rather than a sharp reset, with a 90 day share price return of 7.24% contributing to a 21.69% share price gain year to date and a 3.80% total shareholder return over twelve months.
Spot emerging alternatives to VeriSign’s model by scanning our curated list of 15 high quality undiscovered gems that may be flying under the radar.VeriSign has climbed strongly this year while carrying fresh legal and regulatory questions. Is it worth paying today’s price, or does the risk profile argue for waiting on a lower entry before committing more capital?
Most Popular VeriSign Narrative: 8.9% Undervalued
The most followed narrative pegs VeriSign’s fair value at $321.40, above the last close of $292.71, which frames the lawsuit against a backdrop of still-supportive fundamentals.
VeriSign's financial stability and strategic initiatives, including dividends, buybacks, and effective refinancing, position it for positive revenue growth and investor confidence.
Read the complete narrative. Read the complete narrative.
Want to see what is sitting behind that confidence in VeriSign? The narrative focuses on steady top line progress, higher profit margins, and a richer earnings multiple associated with future cash generation.
Result: Fair Value of $321.40 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the VeriSign story can break if legal challenges on .com pricing or future regulatory shifts around domain fees change how reliably that cash engine runs.
Find out about the key risks to this VeriSign narrative.
Another View: VeriSign on Earnings Multiples
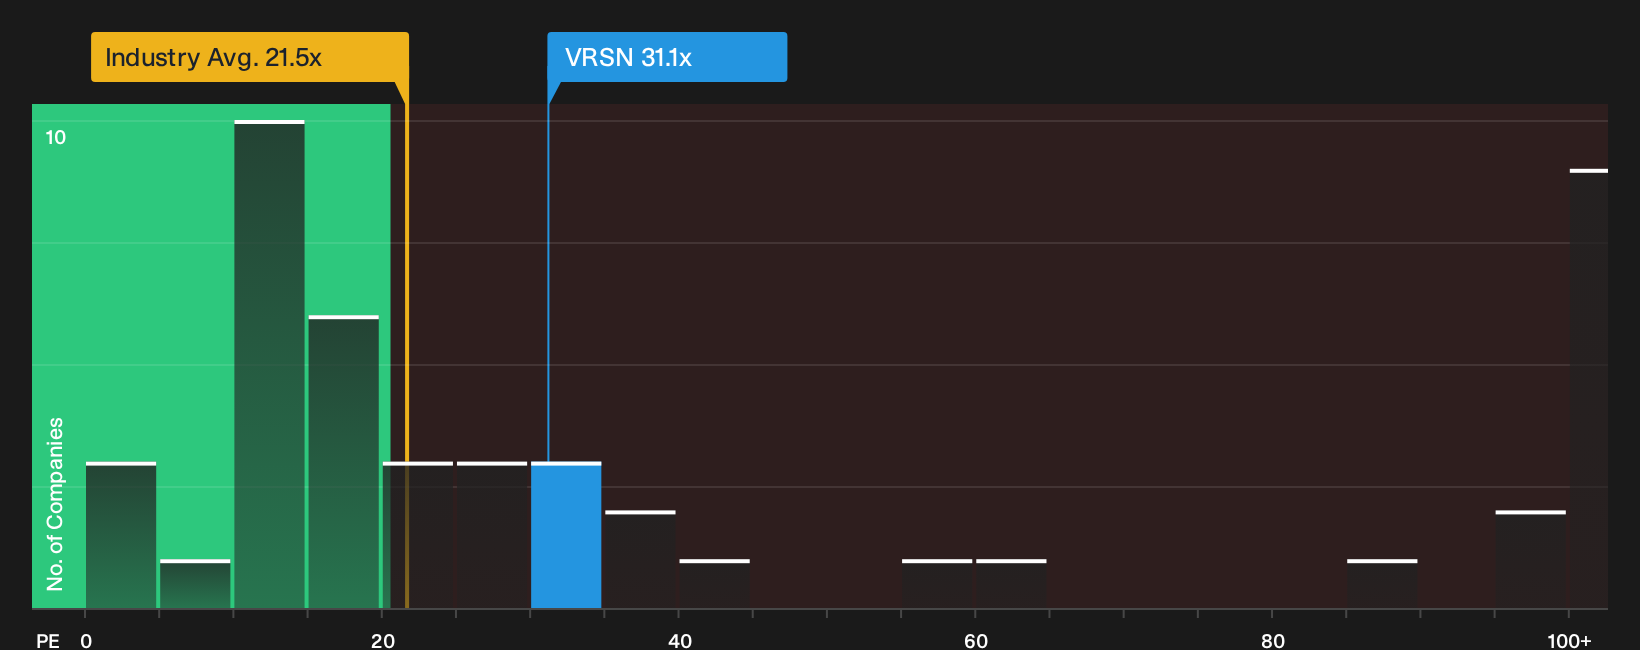
VeriSign may look appealing against the $321.40 fair value line, but the current P/E of 31.1x tells a tougher story. That level sits above the US IT industry at 21.5x and above its own fair ratio of 26.2x, while still below peer averages at 44.9x. This mix of premium pricing and relative peer value leads to a simple question: How comfortable are you paying up today for a business with mid single digit earnings growth expectations?
For investors comparing price tags across the sector, our valuation breakdown helps put these P/E gaps in practical context. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Unsure whether VeriSign’s potential upside offsets the current legal and pricing risks? Move quickly from headline takeaways to the underlying data and weigh both sides for yourself by reviewing the 2 key rewards and 3 important warning signs.
Looking for more VeriSign investment ideas?
If VeriSign is on your radar, broaden your watchlist with a few focused screeners that surface different types of opportunities so you are not relying on one story.
- Target resilient compounders by checking companies that combine strong cash positions with solid fundamentals through the list of solid balance sheet and fundamentals (23 results).
- Look for potential value opportunities by scanning the 31 high quality undervalued stocks that pair quality fundamentals with prices that still look reasonable.
- Prioritise sleep-at-night holdings by reviewing the 11 resilient stocks with low risk scores built around businesses with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com