
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AI Hardware Bet Could Be A Game Changer For Liberty Global (LBTY.A)
- Liberty Global Tech Ventures recently invested in Positron AI, joining an oversubscribed round that values the AI hardware specialist at US$5b and supports development of its Asimov custom silicon for memory intensive inference systems, which are expected to enter production after 2027.
- This move gives Liberty Global exposure to specialized AI infrastructure that could inform future network design, data center strategy, and advanced analytics across its connectivity platforms.
- We will look at how Liberty Global's investment story is influenced by its Tech Ventures backing of Positron AI's memory first silicon platform.
Scan beyond Liberty Global and see how other AI infrastructure plays are setting up for potential breakouts with our curated list of 89 AI infrastructure stocks.
Liberty Global Investment Narrative Recap
To own Liberty Global, you need to believe that its heavy investment in broadband networks, bundles and asset reorganizations can eventually translate a US$3.0b net loss into a more sustainable earnings profile, even as analysts currently expect revenue to drift slightly lower. The key near term swing factor is execution on upgrades and fixed mobile convergence while keeping churn in check as competition bites.
The biggest risk today remains an unprofitable structure sitting on high borrowing, in markets facing price pressure and regulatory scrutiny. The Positron AI stake does not materially change that near term equation. It is more of a long dated option than a fix for current leverage and earnings pressure.
The Positron AI investment aligns most closely with Liberty Global's push to improve network capability and use more advanced analytics across its broadband and mobile platforms. Asimov silicon is targeted at memory heavy AI inference from 2027. This ties back to how efficiently Liberty Global can process customer data, power smarter retention tools and optimize traffic in its European footprint over time.
Without fresh operational announcements around major asset sales, refinancing or a new capital allocation plan linked directly to this AI move, the near term catalysts remain the same. Investors are still watching for evidence that gigabit upgrades, network sharing deals and cost programs can offset falling revenue expectations and ongoing losses before high leverage and regulatory pressure squeeze flexibility further.
Liberty Global's current loss of US$3.0b is set against analyst assumptions that revenue will fall by 3.3% per year, with forecasts pointing to US$4.4b in revenue and US$390.2m in earnings by 2029. This implies an earnings swing of about US$3.4b if that margin shift plays out.
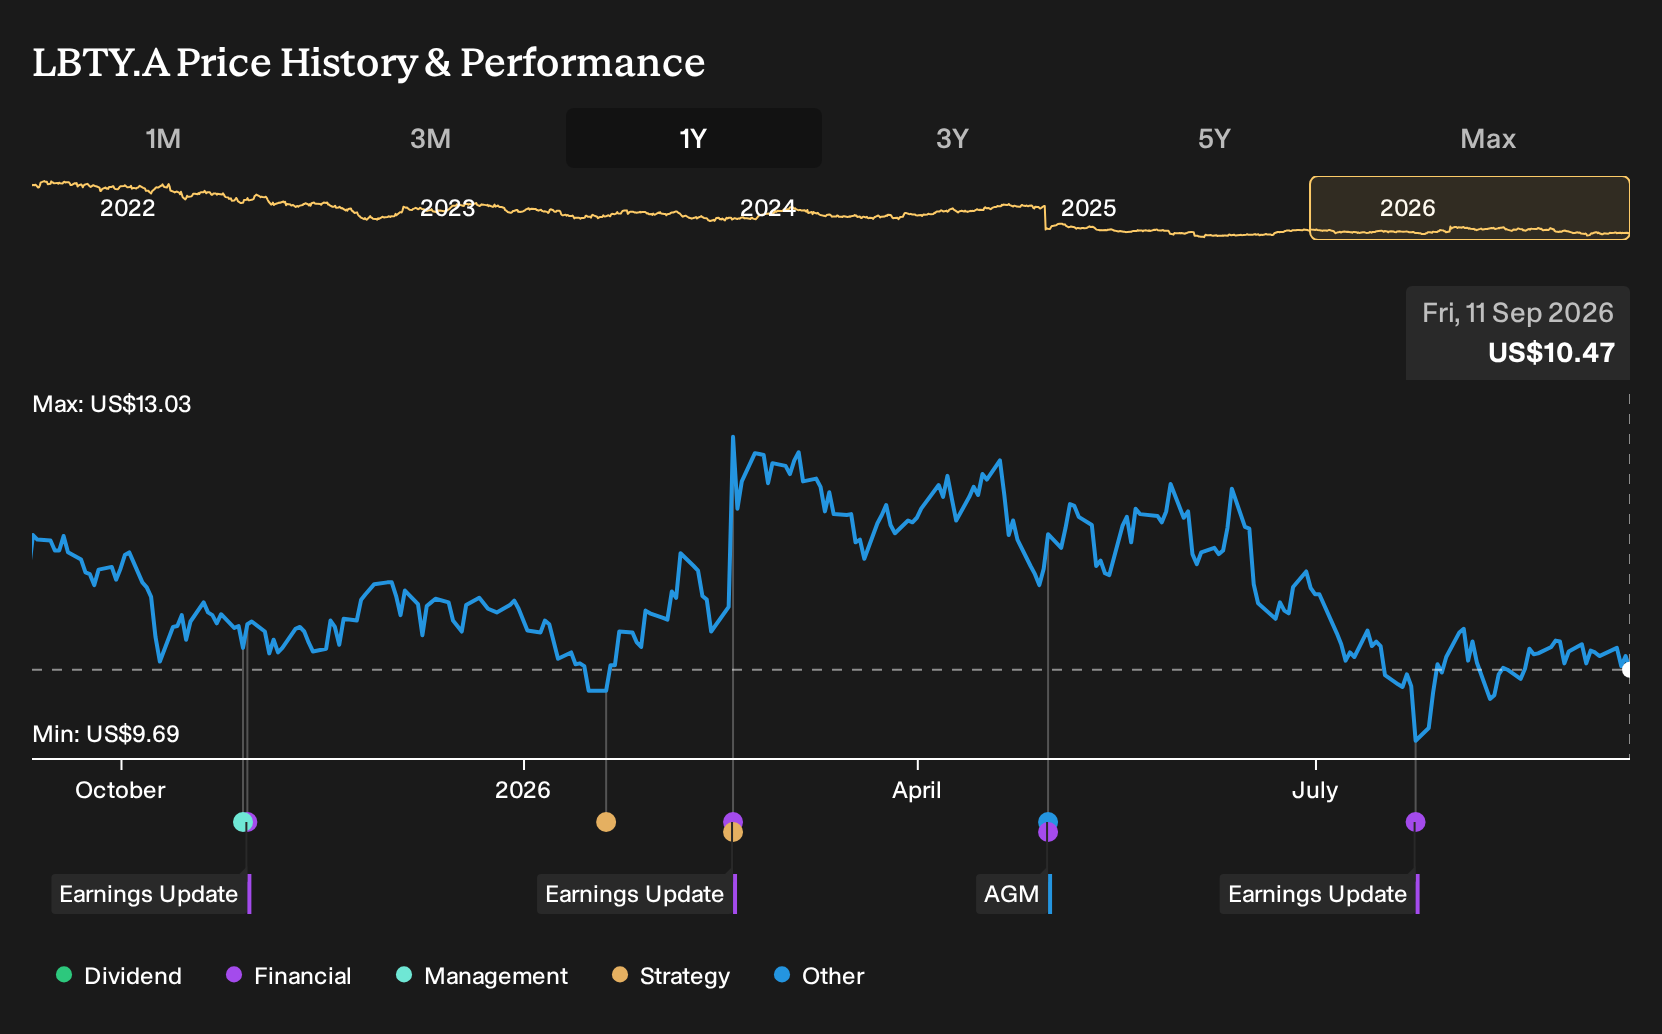
Uncover why Liberty Global's fair value indicates a 39% potential upside to its current price, which could narrow quickly if sentiment turns.
Exploring Other Perspectives
Some of the most optimistic analysts frame the real catalyst as Liberty Global’s asset spins and buyback potential rather than AI exposure. Before this Positron AI news, they were modeling revenue of about US$5.2b and earnings of roughly US$548.0m by 2029. That is far above consensus, so treat it as one of several viewpoints to stress test.
Explore another Liberty Global fair value estimate, including one that suggests up to 269% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Liberty Global research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Liberty Global. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Liberty Global's overall financial health at a glance.
Looking For More Ideas Beyond Liberty Global?
If Liberty Global has sharpened your thinking on risk, balance sheets and future cash flows, it can be useful to line that up against other opportunities side by side using the Simply Wall St Screener.
- For investors who want quality and value in the same place, scan through a curated set of 31 high quality undervalued stocks that combine solid fundamentals with compressed valuations.
- If capital preservation is front of mind, focus on companies that score well on financial strength and stability using a 11 resilient stocks with low risk scores tailored to lower volatility profiles.
- When you are hunting for financially sound businesses that may still be flying under the radar, filter the market with a 15 high quality undiscovered gems and see which stories deserve a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com