
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Digital Realty Trust (DLR) Stock Trades At A Cash Flow Discount But An Earnings Premium
Digital Realty Trust has delivered a strong 59.2% return over the past three years, yet investors now face a split verdict on value as a Discounted Cash Flow (DCF) estimate points to meaningful upside while market multiples lean the other way.
- A 59.2% gain over three years suggests Digital Realty Trust has already rewarded patient shareholders, so fresh buyers need to think carefully about what is priced in.
- New capacity such as the Nairobi Two data center and expansion plans in Iberia can support expectations for future cash flows, while execution risk on large capital projects may weigh on how much investors are willing to pay today.
- A low value score of 2 out of 6 means the broader checks lean expensive even though the intrinsic value estimate screens the stock as undervalued.
The issue now is whether Digital Realty Trust’s current share price already reflects its expansion plans, or if the intrinsic value estimate still points to a meaningful margin of safety.
Compare Digital Realty Trust’s mixed valuation signals with a curated list of AI infrastructure peers by reviewing 89 AI infrastructure stocks that could be positioned for their next potential move.
Does Digital Realty Trust Look Undervalued on Cash Flow?
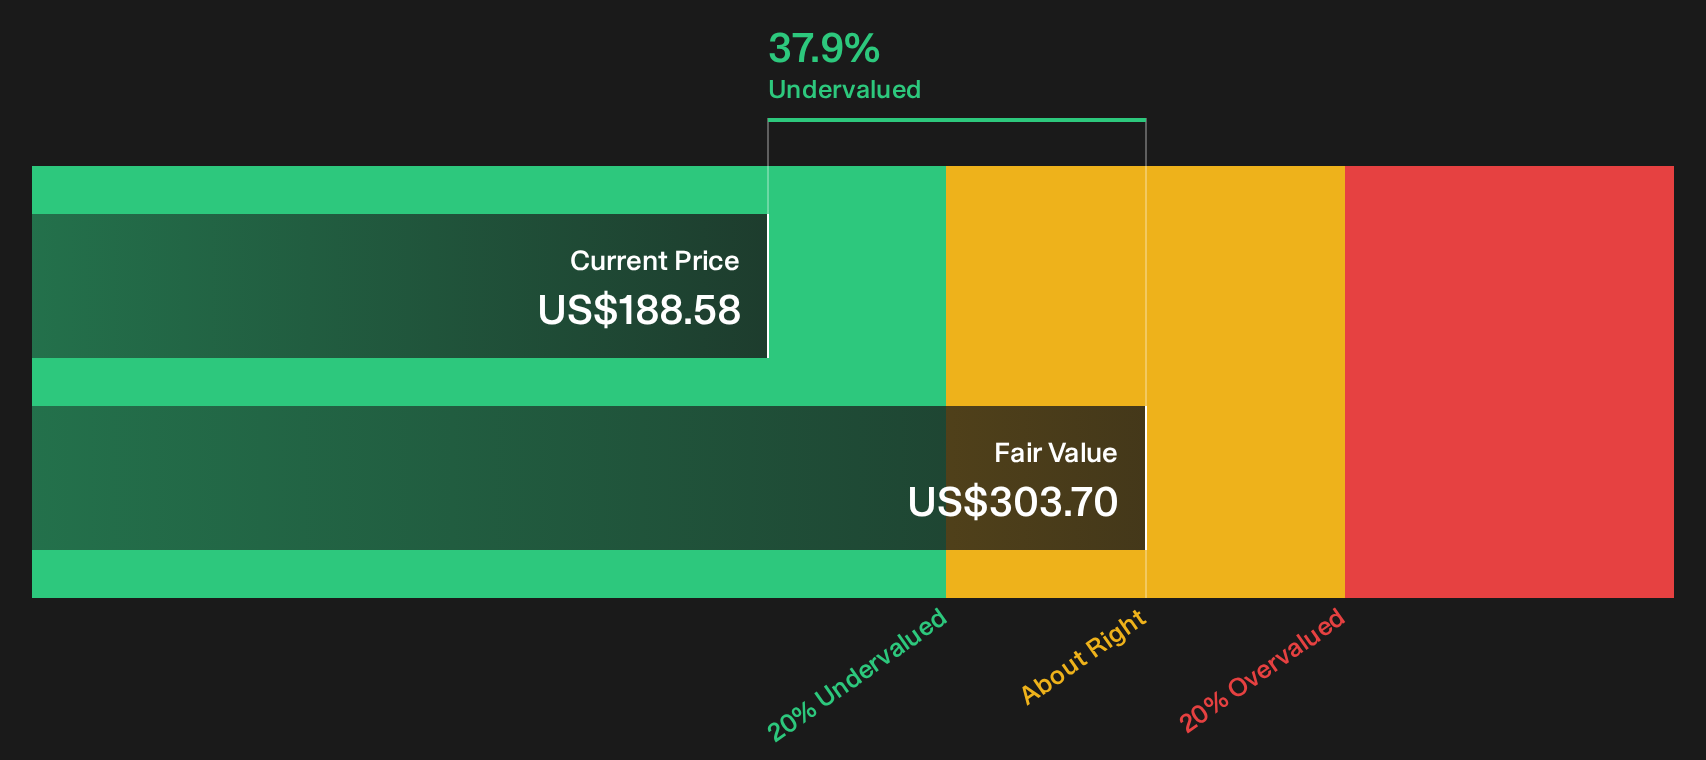
The Discounted Cash Flow model projects the value of Digital Realty Trust by linking today’s price to the cash it is expected to generate for shareholders. Over the latest twelve months, the business produced about $2.27b in free cash flow, and the model assumes that this cash flow continues to grow rather than shrink. On those inputs, the intrinsic value comes out at an estimated $304 per share in $ terms.
Compared with the current market price, that output implies the stock trades at roughly a 37.9% discount and appears undervalued on this cash flow view. The recent opening of the Nairobi Two data center illustrates why the model incorporates ongoing growth in future cash generation, even if the share price has not fully reflected that pattern. For investors comparing Digital Realty Trust with higher headline P/E ratios and complex data center build cycles, the key point is that the DCF relies heavily on existing cash generation already measured in billions of dollars, rather than on a distant blue-sky narrative.
On this Discounted Cash Flow view, Digital Realty Trust currently looks undervalued relative to the cash the business is expected to generate for shareholders.
Our Discounted Cash Flow (DCF) analysis suggests Digital Realty Trust is undervalued by 37.9%. Track this in your watchlist or portfolio, or discover 31 more high quality undervalued stocks.
Has Digital Realty Trust Run Too Far on Earnings?
P/E is a useful lens for Digital Realty Trust because investors in data center REITs often anchor on earnings power per share when comparing across the sector.
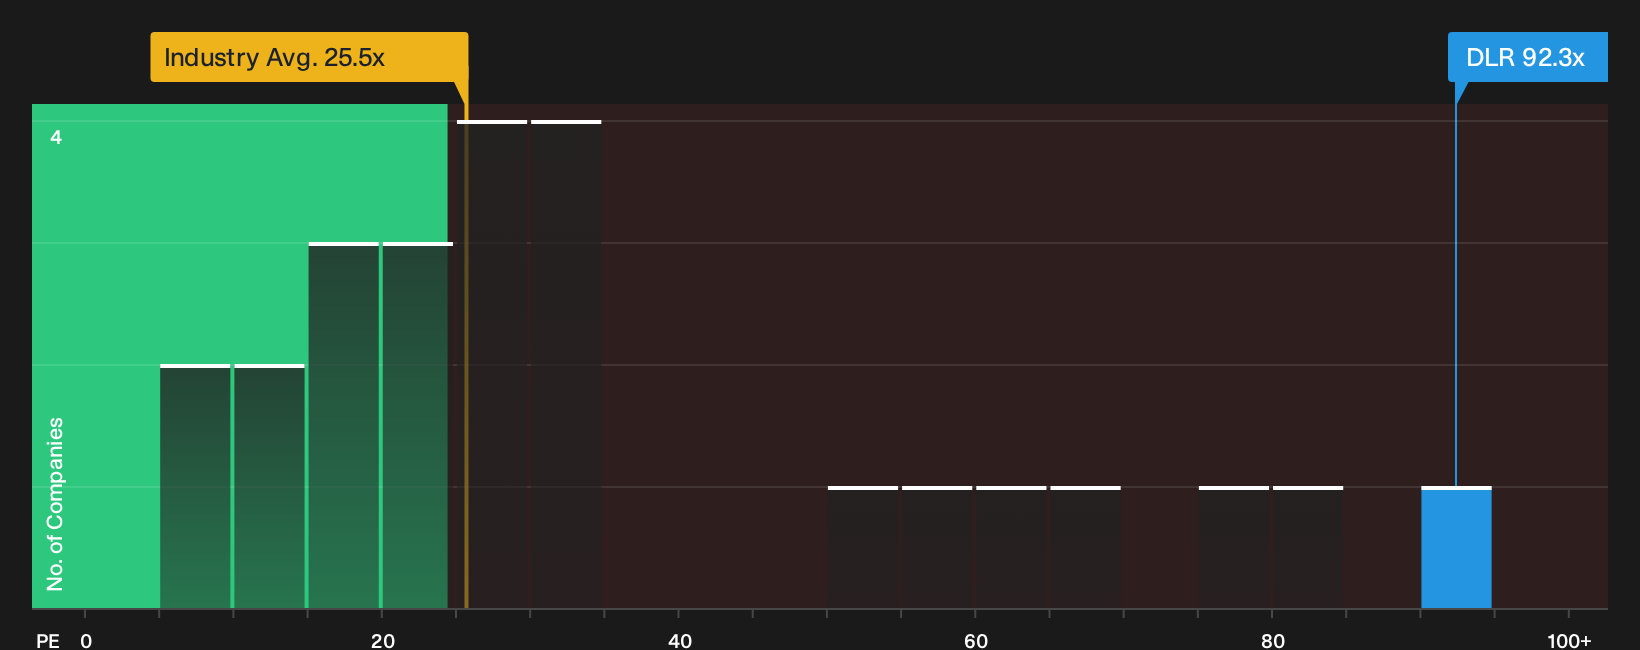
The stock trades on a P/E of 92.3x, which is high compared with both the specialized REIT industry average of 17.2x and the peer group average of 50.8x. A tailored fair P/E ratio that adjusts for Digital Realty Trust’s size, sector, and risk profile sits at 41.1x. That is less than half of where the shares currently change hands, so the market is assigning a sizeable premium to the company’s earnings relative to these benchmarks.
This gap indicates that investors are already paying a higher price for Digital Realty Trust’s role in data infrastructure, even compared with other data center focused stocks. For anyone cross-checking against the cash flow model, the P/E yardstick instead highlights a full valuation on reported earnings.
On the P/E multiple, Digital Realty Trust appears overvalued compared with both its tailored fair ratio and sector benchmarks.
See what the numbers say about this price — find out in our valuation breakdown.
The Digital Realty Trust Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Digital Realty Trust’s valuation puzzle leaves off by explaining which future paths for growth, margins, and earnings would need to hold for the stock to justify a meaningfully higher or lower price than today. These narratives are available on the company’s Community page. Each scenario ties a fair-value anchor to a particular combination of potential catalysts and risks, allowing you to observe over time which version of the story gains traction.
Add your own narrative on Digital Realty Trust to present a number-focused view on whether developments like the Nairobi Two data center and the Iberia expansion ultimately justify today’s valuation. Put your case on record in the Simply Wall St community and see how it holds up as fresh results and project updates arrive.
Do you think there's more to the story for Digital Realty Trust? Head over to our Community to see what others are saying!
The Bottom Line
Digital Realty Trust screens as undervalued on a Discounted Cash Flow (DCF) view, while the P/E comparison flags the shares as overvalued relative to peers and a tailored fair ratio. That split comes from the intrinsic value model leaning on current cash generation and long term project cash flows, while the multiples lens reflects how much investors already pay for growth expectations and sector enthusiasm. Broader valuation checks remain weak. The key question is whether future projects like Nairobi and Iberia convert into durable cash returns, rather than just supporting a rich earnings multiple.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com