
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Legrand (ENXTPA:LR) Stock Looks Fully Priced With Rich Cash Flow And Earnings
Legrand stock has put in a strong run over the past few years, yet both the Discounted Cash Flow (DCF) intrinsic value estimate and standard market multiples currently point to an expensive entry point relative to that history. Investors looking at Legrand today are weighing those stretched valuation signals against a share price that has already rewarded patience over the medium term.
- Over the past 3 years, Legrand has delivered a 70.0% return, which sets a high bar for any new upside case from here.
- Expectations for steady cash generation from Legrand's electrical and digital infrastructure portfolio can support the current share price. However, any pressure on margins or slower cash flow growth may quickly challenge a valuation that already prices in a lot of good news.
- On Simply Wall St's broader checks, Legrand scores 1 out of 6 on value, which leans expensive rather than a clear bargain on most measures.
The issue now is whether Legrand's current market price leaves enough potential reward relative to the intrinsic value estimate and the premium signalled by earnings multiples.
Broaden your watchlist beyond Legrand by scanning 184 high quality undervalued stocks that our process surfaces as potential alternatives when a stock screens as expensive on both DCF and earnings multiples.
Is Legrand Getting Expensive on Cash Flow?
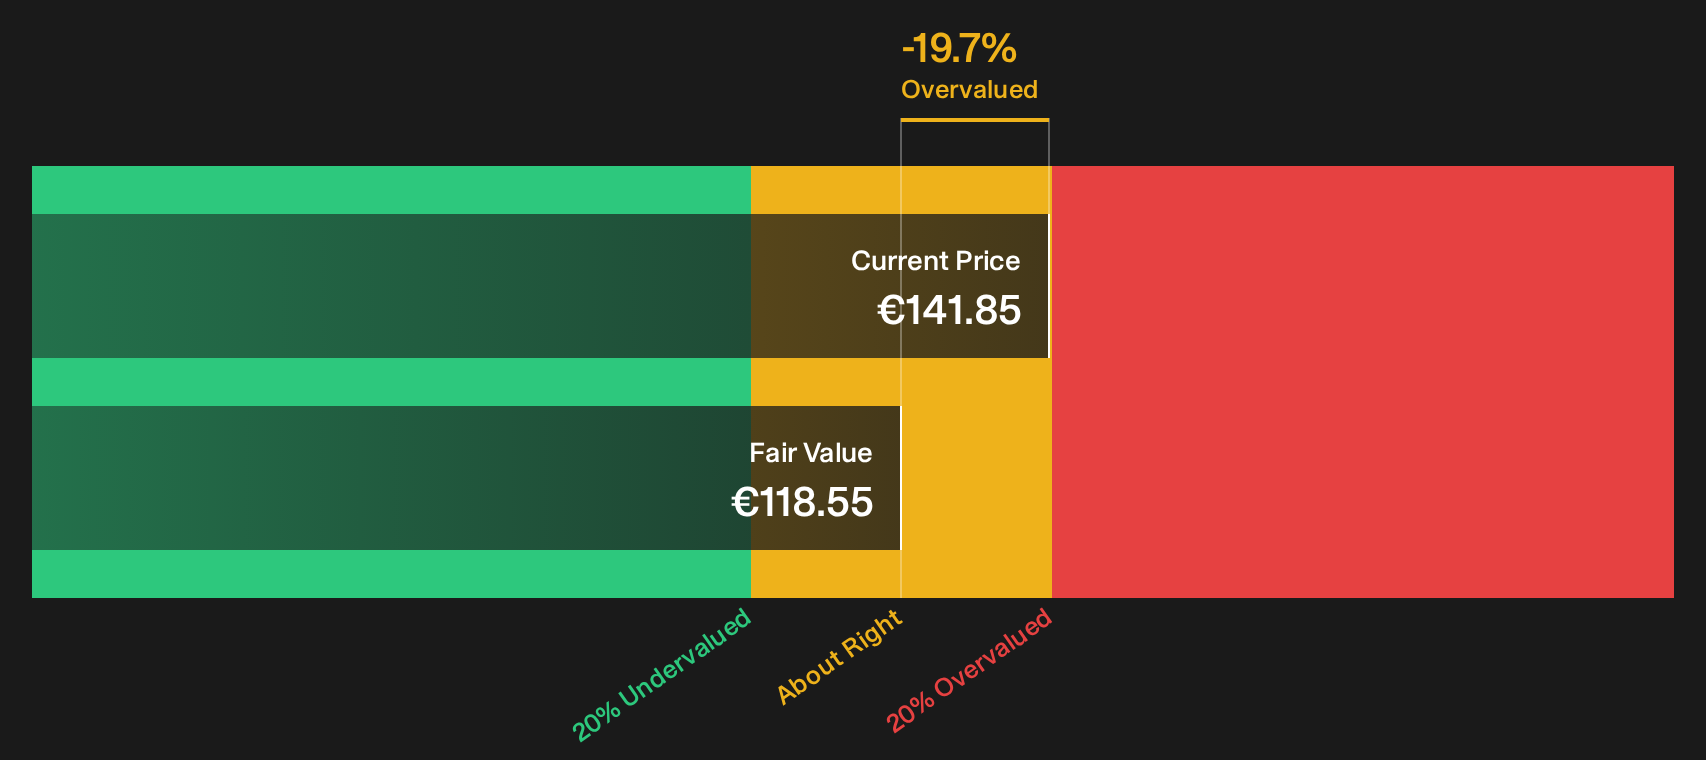
The Discounted Cash Flow (DCF) model used here values Legrand based on the cash it is expected to generate for shareholders over time. Latest twelve month free cash flow is about €1.29b, and the projections behind the model assume that this cash stream grows rather than contracts over the coming decade.
On those inputs, the DCF indicates an intrinsic value of about €118.55 per share. The current market price implies a premium of roughly 19.7% to that estimate. For an investor studying Legrand, that gap suggests the market is already paying a higher price for the quality and consistency of its cash generation, with limited cushion in the model if free cash flow comes in lower than forecast.
On this cash flow view, Legrand currently appears overvalued relative to its DCF-based intrinsic value estimate.
Our Discounted Cash Flow (DCF) analysis suggests Legrand may be overvalued by 19.7%. Discover 184 high quality undervalued stocks or create your own screener to find better value opportunities.
Is Legrand Getting Expensive on Earnings?
P/E works well for Legrand because earnings are a key lens for investors judging how much they are paying for each euro of profit today.
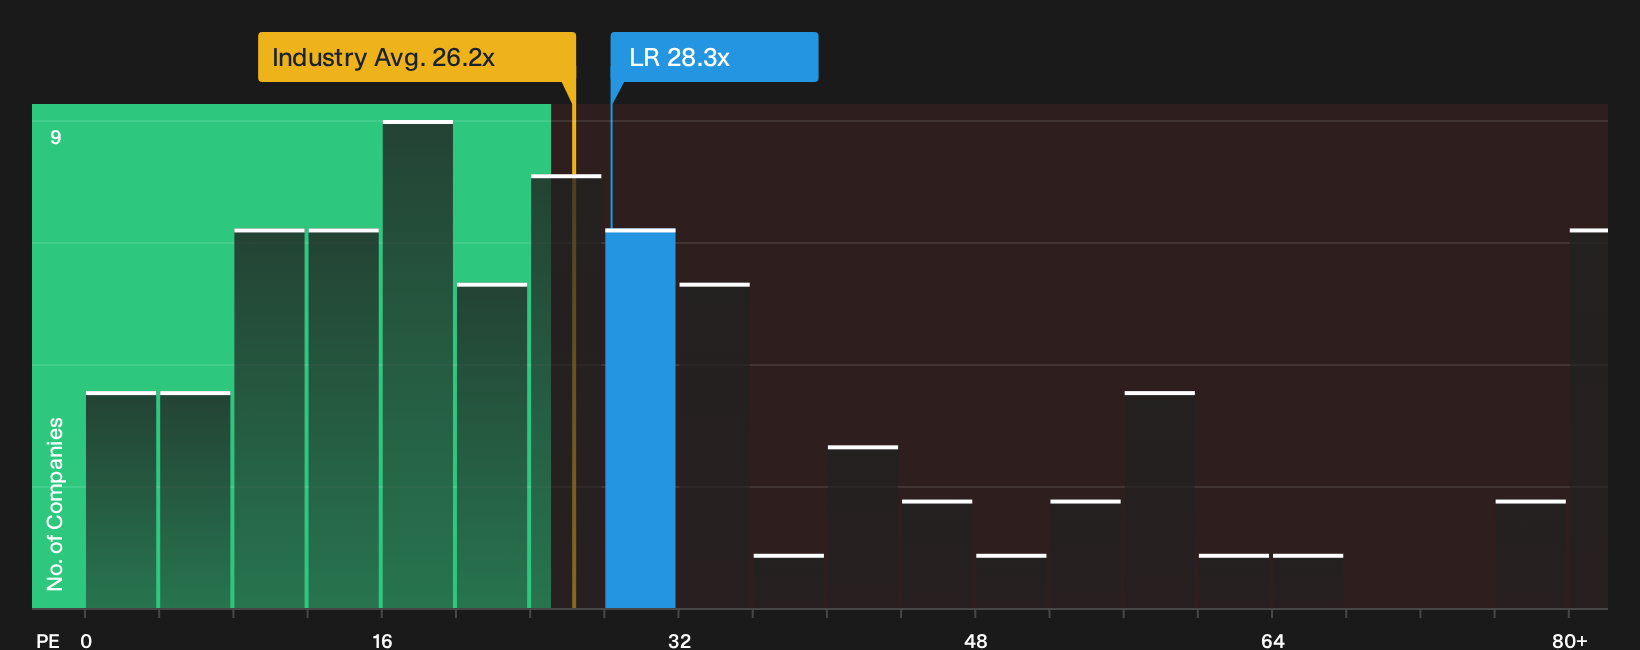
The stock currently trades on about 28.3x earnings. That sits very close to the wider electrical sector average of roughly 28.0x, yet it is below the peer group average near 34.9x. On Simply Wall St’s fair multiple, which adjusts for factors such as growth profile, margins, size and risk, Legrand screens closer to 25.2x. The gap between this tailored yardstick and the actual P/E suggests the market is willing to pay a premium for the business compared with what the model implies.
For investors weighing an entry point into Legrand, this means the share price already embeds relatively full expectations when judged against its earnings power.
On the P/E yardstick, Legrand appears overvalued because the current multiple sits above the fair ratio implied by its fundamentals.
See what the numbers say about this price — find out in our valuation breakdown.
The Legrand Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Legrand pick up where the valuation puzzle leaves off and explain which paths for growth, profitability and earnings would need to occur for the stock to be worth materially more or materially less than today’s price, all hosted on the Community page. Each scenario links its implied number to a clear view on how Legrand's revenue trajectory, margin profile and key risks might shift, giving you a reference point to revisit as fresh information becomes available.
Community views on Legrand are sharply split, with one camp leaning into the data center upcycle and another worried that reliance on that same engine is a weak spot.
Bull case: 29% undervalued
"Legrand's positioning in accelerating global electrification and urbanization, especially in emerging markets, is set to drive structurally higher demand beyond current expectations..."
Read the full Bull Case to see why Legrand could be undervalued
Bear case: 22% overvalued
"Legrand's exceptional recent growth is almost entirely driven by the data center segment, leaving the rest of its business largely stagnant..."
Read the full Bear Case to see why Legrand could be overvalued
Do you think there's more to the story for Legrand? Head over to our Community to see what others are saying!
The Bottom Line
Put simply, both the Discounted Cash Flow (DCF) intrinsic value estimate and the earnings multiple view point to Legrand looking overvalued right now. The market is asking you to pay a premium for the quality of its cash generation and profit profile, with limited room in those models for disappointment. What really decides the outcome from here is whether Legrand can sustain the cash flow and margin strength implied by that premium, especially in areas like data center exposure that split opinion. If that assumption holds, the rich pricing may feel justified. If it does not, the valuation leaves little buffer.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com