
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Chervon Holdings (SEHK:2285) Gets A New CEO As Valuation Questions Grow
Chervon Holdings (SEHK:2285) is back in focus after the board appointed industry veteran Joseph Galli Jr. as chief executive officer, replacing founder Longquan Pan, who remains executive director and chairman.
That leadership announcement lands on a strong run for Chervon Holdings, with the share price at HK$24.6 after a 23% 1 day share price return and a 46.43% 90 day share price return. The 1 year total shareholder return of 20.59% points to momentum already building before this CEO change.
Scan how this CEO shake-up at Chervon Holdings compares with other potential breakouts in tools, equipment, and manufacturing by reviewing our hand-picked 618 high quality undiscovered gems.
After that 1 day jump and with Chervon Holdings now trading close to a HK$25 analyst target yet showing a different intrinsic value estimate, the real puzzle is where fair value actually lines up in that spread.
Price-to-Earnings of 14.7x: Is it justified?
On simple earnings math, Chervon Holdings trades on a P/E of 14.7x, which makes the recent HK$24.6 share price look expensive against several benchmarks.
The P/E ratio compares what investors are willing to pay today for each unit of current earnings. For a tools and equipment manufacturer like Chervon Holdings, this measure gives a quick read on how the market is weighing its profit profile against listed peers.
Chervon Holdings is described as good value when stacked up against a peer group average P/E of 38.5x. Yet the same 14.7x multiple screens as expensive when compared both to the Hong Kong Consumer Durables sector on 11.3x and to an estimated fair P/E of 10x that our regression based fair ratio points to as a level the market could move towards.
That mix of signals, cheaper than some peers but richer than the sector and the fair ratio, indicates that the P/E is sending a firm message that the stock is already pricing in a healthier earnings path than its own recent history of declining profits and lower net margins would suggest over the past five years.
Explore the SWS fair ratio for Chervon Holdings
Result: Price-to-Earnings of 14.7x (OVERVALUED)
Still, the bullish read on Chervon Holdings can quickly crack if earnings momentum stalls or if the premium to sector P/E multiples starts to unwind.
Find out about the key risks to this Chervon Holdings narrative.
Another view on Chervon Holdings valuation
The SWS DCF model points in a very different direction for Chervon Holdings. At HK$24.6, the stock trades well above an estimated future cash flow value of HK$9.69, which leans toward an overvalued read and raises questions about how much optimism is already in the price.
Look into how the SWS DCF model arrives at its fair value.
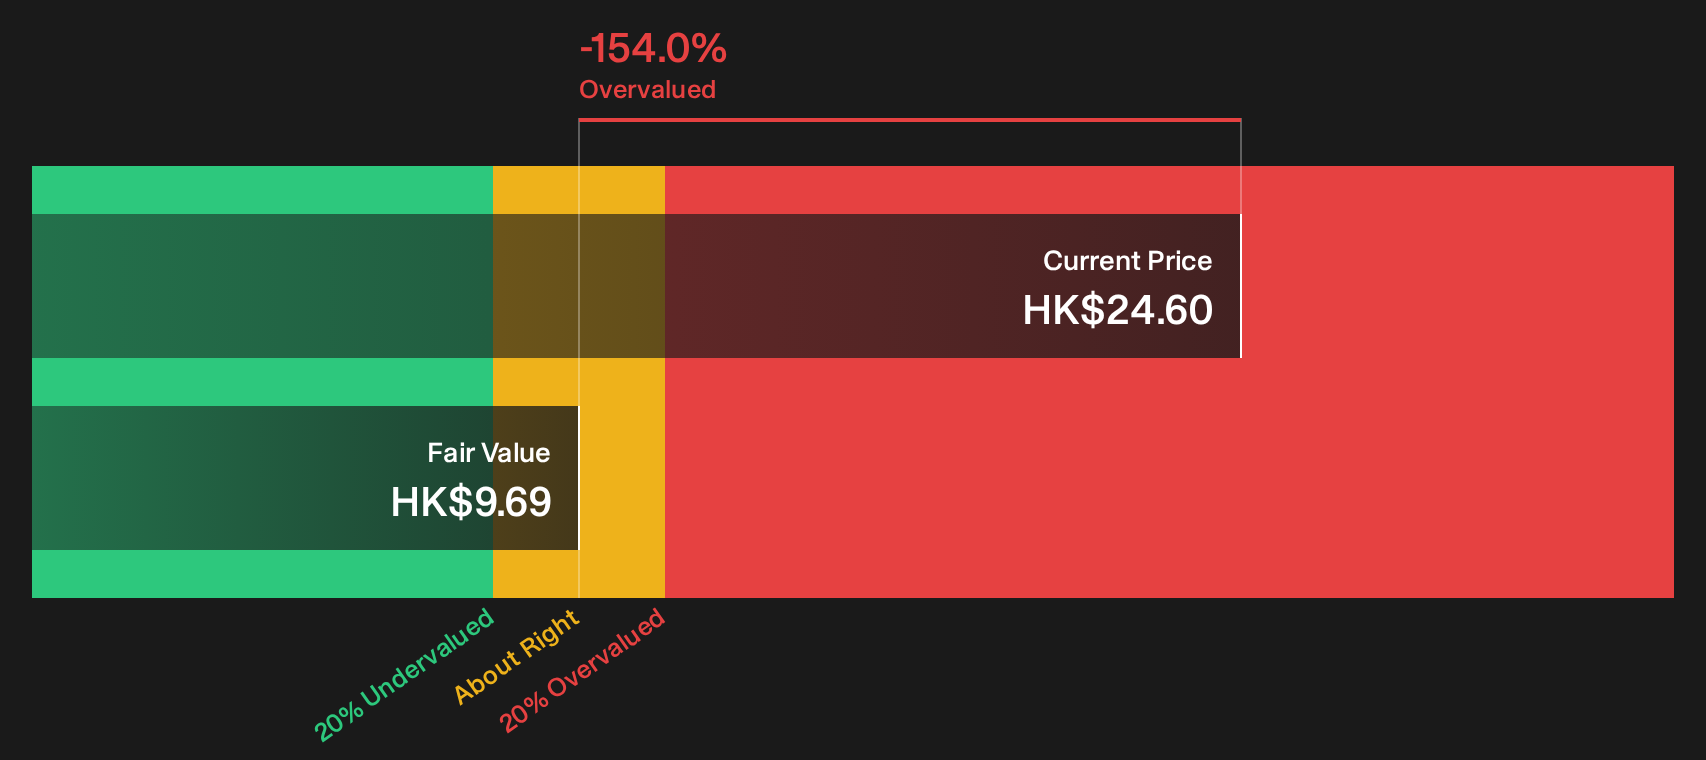
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Chervon Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 184 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Chervon Holdings is clearly heated, and fast moves often split opinions. Move quickly, stress test the numbers, and weigh the 1 key reward.
Looking for more ideas beyond Chervon Holdings?
If Chervon Holdings has your attention right now, do not stop there. Use the screeners below to pressure test this move and uncover alternatives.
- Target potential bargains that pair quality with attractive pricing by running your filters through 184 high quality undervalued stocks.
- Prioritise durability by scanning companies with strong finances and cleaner balance sheets using the list of solid balance sheet and fundamentals (194 results).
- Tilt your watchlist toward resilience focused opportunities by assessing candidates in the 99 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com