
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AMC (AMC) Stock Looks Like A Bargain On Cash Flow And Sales
AMC Entertainment Holdings has a share price that has fallen sharply over five years, yet current valuation checks suggest the stock now screens cheap on several measures. The Discounted Cash Flow (DCF) intrinsic value estimate and market based multiples both point to undervaluation at recent prices.
- Over the past five years, AMC Entertainment Holdings has declined about 99%, which means long term holders have absorbed very heavy losses that shape how new buyers may think about risk.
- New initiatives such as the Leawood Films distribution arm can support revenue and cash flow over time, while ongoing legal and regulatory friction around products like tokenized AMC securities may add uncertainty to how the equity is perceived.
- The broader checks lean cheap, with AMC Entertainment Holdings scoring a high 5 out of 6 on value metrics, which signals more indicators pointing to undervaluation than to an expensive stock.
For investors, the debate is whether the current discount to intrinsic value is enough to compensate for the company specific risks that recent history has highlighted.
Seize the reset in AMC Entertainment Holdings and scan for other beaten down valuations that still screen strong on fundamentals with 31 high quality undervalued stocks.Is AMC Entertainment Holdings a Bargain on Cash Flow?
The Discounted Cash Flow model for AMC Entertainment Holdings values the stock by projecting future free cash flows and then discounting them back to today. Recent numbers show the latest twelve month free cash flow at a loss of about $37.4 million, and the model assumes a recovering cash flow profile with projections moving into positive territory over the next decade.
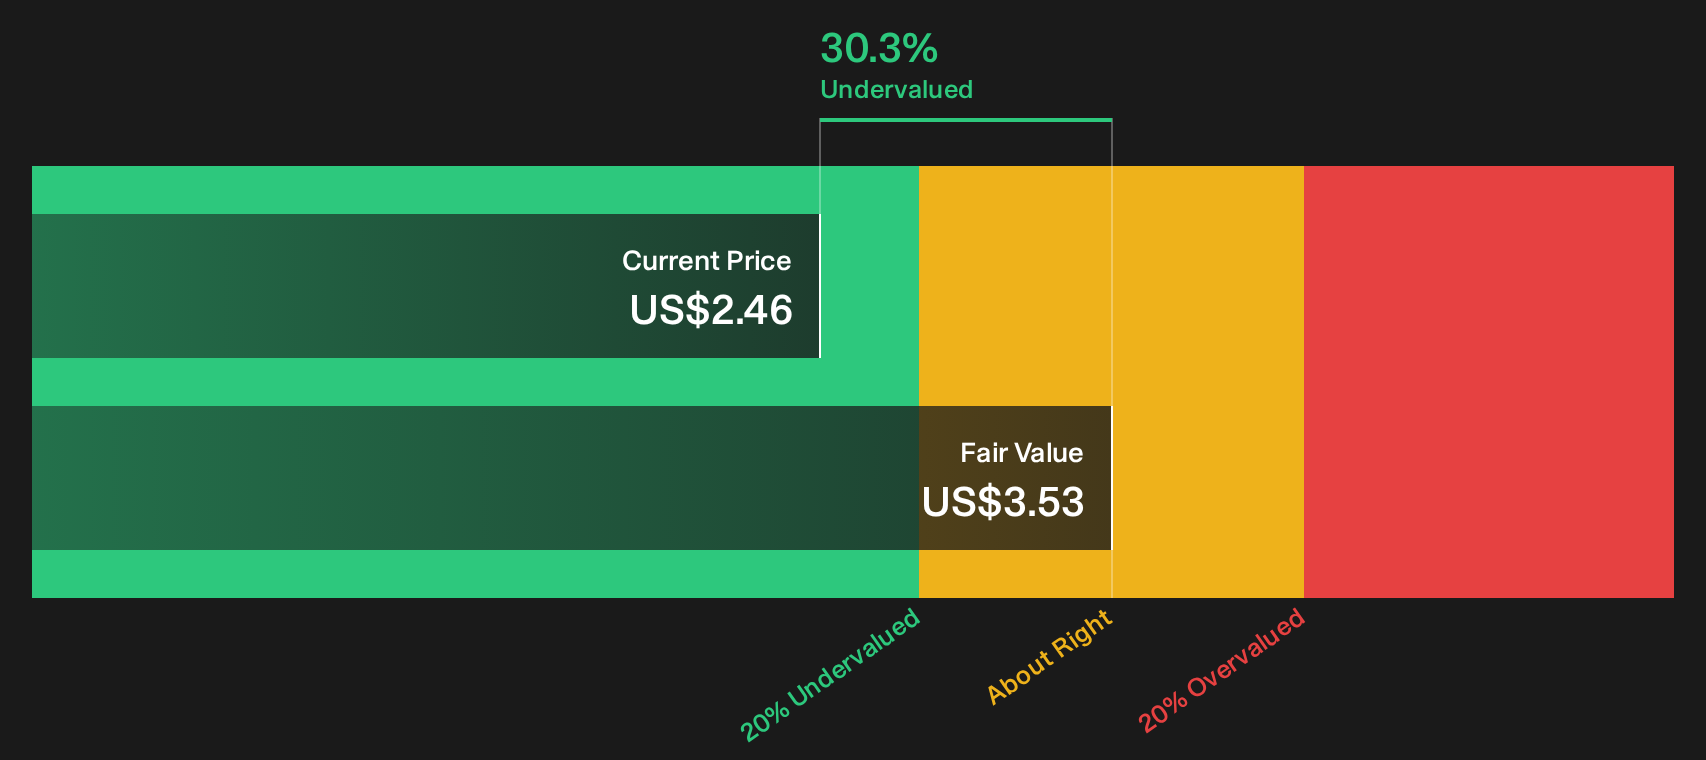
Based on those assumptions, the 2 Stage Free Cash Flow to Equity approach results in an intrinsic value of about $3.53 per share. This implies roughly a 30.3% discount to the recent trading price and presents AMC Entertainment Holdings as undervalued according to this method. The clash over Robinhood’s tokenized AMC securities helps explain why the share price may stay below the cash flow based estimate, since legal and regulatory questions can influence how durable any recovery appears to traders.
Taken together, the Discounted Cash Flow analysis indicates that AMC Entertainment Holdings currently appears undervalued relative to the cash flows analysts expect it to produce.
Our Discounted Cash Flow (DCF) analysis suggests AMC Entertainment Holdings is undervalued by 30.3%. Track this in your watchlist or portfolio, or discover 31 more high quality undervalued stocks.
Is AMC Entertainment Holdings Still Cheap on Sales?
P/S is a useful lens for AMC Entertainment Holdings because revenue is still the clearest anchor for a business working through losses and capital structure noise.
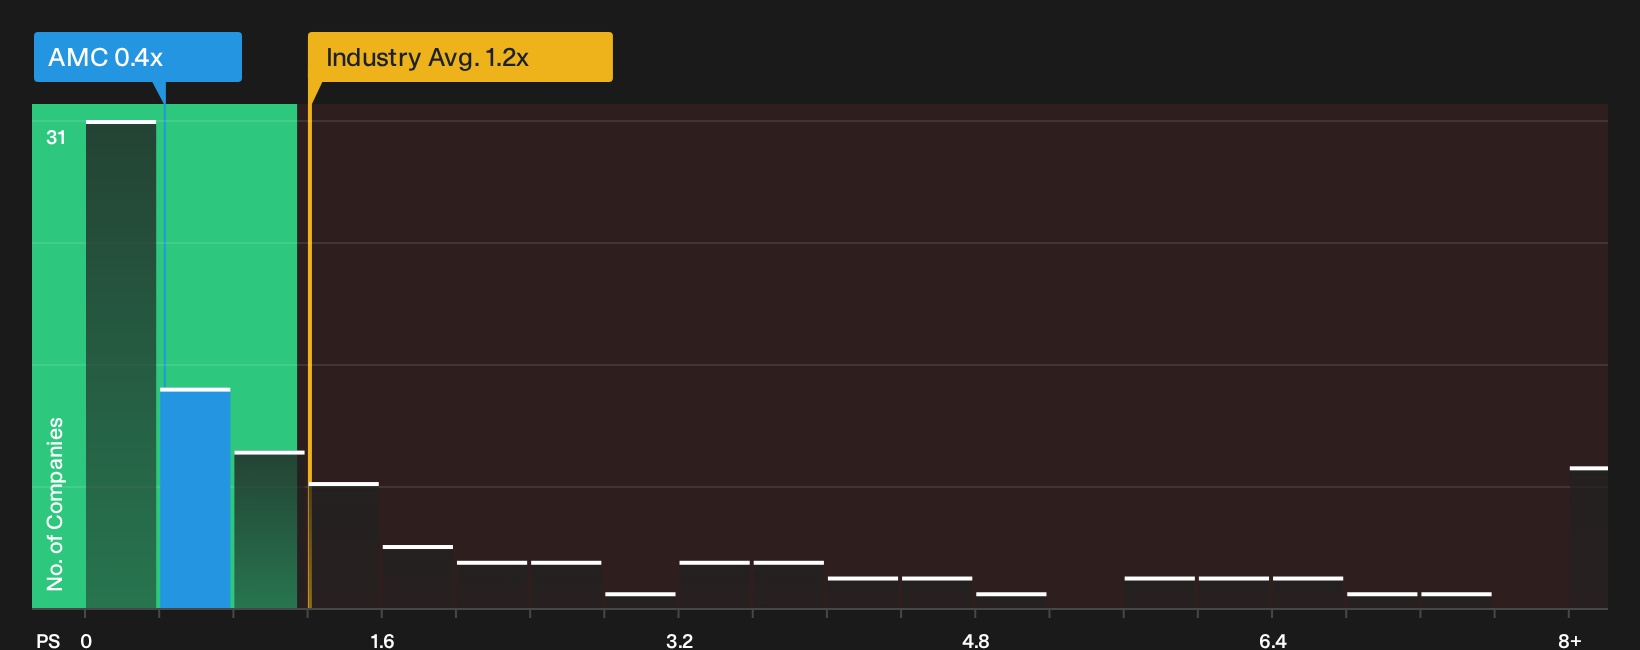
On this measure, AMC trades around 0.4x P/S, compared with roughly 1.2x for the wider Entertainment industry and about 3.9x for closer peers. The implied fair P/S multiple from the model sits higher at about 0.8x, which indicates the present valuation is well below what the company might command once its revenue profile and risk factors are considered together.
That gap indicates the share price reflects a steep discount to AMC Entertainment Holdings relative to both sector benchmarks and the tailored fair ratio, even after recent headlines and legal debate around tokenized AMC products have kept attention high.
On the P/S multiple, AMC Entertainment Holdings appears undervalued compared with both its industry and the model’s own fair benchmark.
See what the numbers say about this price — find out in our valuation breakdown.
The AMC Entertainment Holdings Narrative: What Would Justify Today's Price?
AMC Entertainment Holdings' valuation puzzle raises a simple follow up question for anyone reading those DCF and P/S signals. Narratives on Simply Wall St's Community page spell out which combinations of future revenue, profitability and earnings paths would need to hold for AMC Entertainment Holdings to be worth meaningfully more or less than today. Each one ties a specific mix of potential catalysts and risks to its own fair value anchor, allowing readers to track over time which story aligns with reality.
Community views on AMC Entertainment Holdings are pulled in opposite directions, with one camp focused on premium cinema economics and the other on structural headwinds and debt.
Bull case: 15% undervalued
"Ongoing success in diversifying content such as direct distribution of concerts, niche film events, and alternative content reduces dependence on studio box office releases..."
Read the full Bull Case to see why AMC Entertainment Holdings could be undervalued
Bear case: 37% overvalued
"AMC faces intensifying competition from streaming platforms and at home entertainment, which continues to shift consumer behavior away from physical movie theaters..."
Read the full Bear Case to see why AMC Entertainment Holdings could be overvalued
Do you think there's more to the story for AMC Entertainment Holdings? Head over to our Community to see what others are saying!
The Bottom Line
AMC Entertainment Holdings screens as undervalued on both the Discounted Cash Flow (DCF) intrinsic value estimate and market based multiples, which line up rather than conflict. That combination suggests the current market price already bakes in a heavy dose of caution around the business model, balance sheet and legal noise. What really decides the outcome from here is whether cash flows and revenue eventually track closer to the intrinsic value assumptions, or whether concerns around debt, competition and regulatory uncertainty prove sticky enough that the discount simply reflects a value trap.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com