
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
UroGen Pharma (URGN) Stock May Still Trade At A Discount To Sales
UroGen Pharma has logged a strong three year return, and today the share price around US$42 still lines up with valuation checks that mostly suggest the stock leans cheap rather than stretched.
- The stock has gained about 165.9% over three years, which puts recent pullbacks in a very different light for anyone thinking in multi year terms.
- Future cash generation from UroGen Pharma's urologic therapies can support the current price, while execution risk around clinical results and commercialization may still weigh on what investors are willing to pay.
- The broader valuation work points to a high value score, and UroGen Pharma screens as attractively priced on 5 of 6 checks even after the strong multi year run.
The issue now is whether UroGen Pharma's recent share gains have already absorbed most of that apparent discount or if the current level still leaves meaningful valuation room for long term investors.
Scan for other UroGen Pharma style reratings by jumping into our hand picked list of 32 high quality undervalued stocks that still trade on what looks like a discount today.
Where Does UroGen Pharma Sit on Sales?
P/S fits UroGen Pharma well because the company is still building toward consistent free cash flow and earnings, so revenue is the cleanest anchor for a market check.
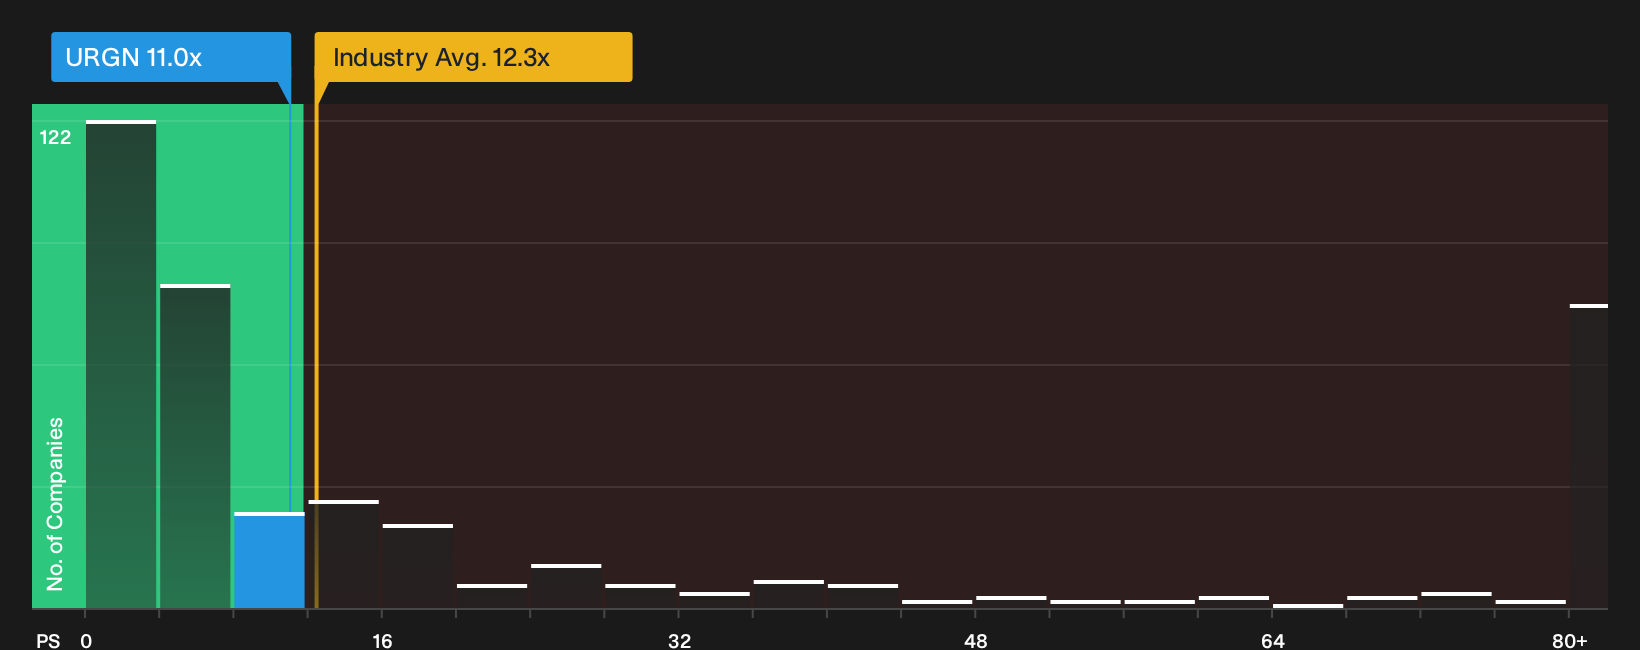
On this lens, UroGen Pharma trades at a P/S of about 11.0x, compared with roughly 12.3x for the broader biotechs sector and about 4.0x for closer peers. A tailored fair P/S ratio for the stock, which blends its growth profile, margins, size and risk into one yardstick, sits at about 11.3x. That puts the current multiple very close to where this framework would expect it to land.
The gap to peers shows investors are already paying a premium to more comparable companies, while the discount to the wider industry tempers that signal. Taken together, the market seems to be pricing UroGen Pharma as neither a clear bargain nor an obvious outlier on sales.
On the P/S multiple, UroGen Pharma appears roughly fairly valued based on its revenue profile and risk mix.
See what the numbers say about this price — find out in our valuation breakdown.
The UroGen Pharma Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for UroGen Pharma pick up where the valuation work above leaves off by spelling out the specific growth, margin and earnings paths that would need to play out for the stock to be worth materially more or less than today’s price on the Community page. Instead of a single output from a ratio or model, these storylines lay out the future that figure assumes, so you can watch in real time whether UroGen Pharma's actual progress lines up with it.
One of the top community narratives on UroGen Pharma: 12% undervalued
"With the bulk of future growth dependent on successful commercialization of a small number of products, even minor clinical or commercial stumbling blocks for Jelmyto or ZUSDURI could create significant revenue volatility."
Read one of the top narratives on UroGen Pharma
Do you think there's more to the story for UroGen Pharma? Head over to our Community to see what others are saying!
The Bottom Line
On the current P/S framework, UroGen Pharma screens as about fairly valued, not obviously cheap after its strong multi year reset. The broader checks still lean constructive, which suggests the market is already giving the company some credit for its pipeline and commercial potential while stopping short of paying up for flawless execution. What really decides the outcome from here is whether UroGen Pharma can turn its urologic therapies into durable, less lumpy revenue without major clinical or launch setbacks that would challenge the current multiple.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com