
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Banco Bilbao Vizcaya Argentaria (BME:BBVA) Could Be 11% Overvalued After Its Strong Run
Banco Bilbao Vizcaya Argentaria (BME:BBVA) has drawn attention after recent share-price moves, with the stock last closing at €25.41 on 10 September 2026. Investors are weighing this level against the bank’s multi-year return profile.
Recent moves at Banco Bilbao Vizcaya Argentaria fit into a strong run, with a 90 day share price return of 26.48% and a year to date share price gain of 24.68%, while the 1 year total shareholder return of 63.26% and 5 year total shareholder return of 474.82% point to powerful, sustained momentum.
Scan how Banco Bilbao Vizcaya Argentaria’s powerful run compares with other potential breakout opportunities in our curated list of 185 high quality undervalued stocks
After such a strong run in Banco Bilbao Vizcaya Argentaria, the real issue now is simple. Does the current price still offer a rewarding trade off between upside potential and the risks you are taking on?
Most Popular Narrative: 10.5% Overvalued
The most followed narrative on Banco Bilbao Vizcaya Argentaria puts fair value at €22.99, which sits below the recent €25.41 close. The story therefore leans toward a rich valuation that still depends heavily on future execution and capital returns.
Regulatory-approved simplification of risk models (notably IRB model changes) and capital management innovations are set to release significant CET1 capital and optimize RWA density, enabling increased capital returns to shareholders and supporting return on equity growth.
Want a closer look at why this fair value still prices in a premium for Banco Bilbao Vizcaya Argentaria? The narrative leans on ambitious revenue expansion, a step down in profitability, and a higher future earnings multiple to keep the story intact. The full breakdown links those moving parts into one valuation storyline.
Result: Fair Value of €22.99 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the whole Banco Bilbao Vizcaya Argentaria narrative can be knocked off course if Turkey’s macro backdrop worsens or regulators tighten capital rules more than expected.
Find out about the key risks to this Banco Bilbao Vizcaya Argentaria narrative.
Another View: BBVA Through The Cash Flow Lens
The analyst narrative frames Banco Bilbao Vizcaya Argentaria as 10.5% overvalued at €25.41 versus a fair value of €22.99. A different tool tells a very different story. The SWS DCF model puts BBVA’s future cash flows at €38.63 per share, which points to a wide undervaluation instead.
That gap between a €22.99 fair value based on earnings assumptions and €38.63 from the cash flow model raises a simple question for you: Which set of inputs feels closer to how BBVA will actually run its balance sheet and generate cash?
Look into how the SWS DCF model arrives at its fair value.
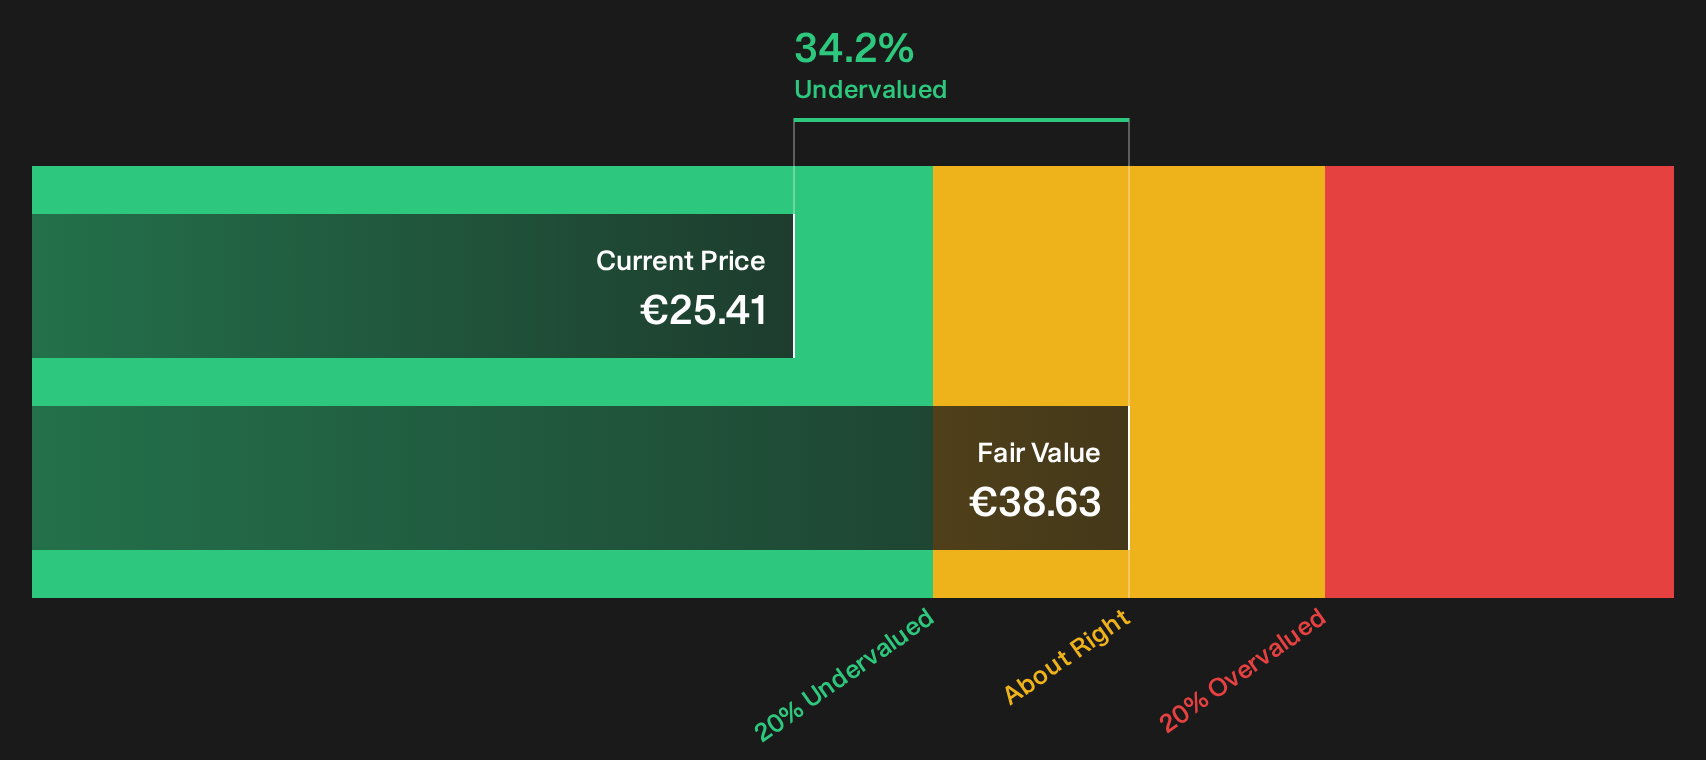
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Banco Bilbao Vizcaya Argentaria for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 185 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or a clear tilt in sentiment around Banco Bilbao Vizcaya Argentaria. Either way, the window to stress test the thesis is open right now, so weigh the upside against the concerns by digging into the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Banco Bilbao Vizcaya Argentaria?
Do not stop your research with Banco Bilbao Vizcaya Argentaria. Fresh ideas from different corners of the market can sharpen your judgement and highlight better risk trade offs.
- Target higher income potential by reviewing 164 dividend fortresses to support a portfolio focused on payouts and resilience.
- Spot sturdier balance sheets early by scanning the list of solid balance sheet and fundamentals (195 results) to find businesses with financial cushioning already in place.
- Get ahead of the crowd by tracking 620 high quality undiscovered gems that may not yet be heavily followed but already show strong fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com