
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Is Behind The Fresh Attention On PDF Solutions (PDFS)?
PDF Solutions launches Exensio Aurora and puts data scale in focus
PDF Solutions (PDFS) has launched Exensio Aurora, a new analytics architecture built to handle semiconductor manufacturing data at petabyte scale and support AI-driven workflows across factories and supply chains.
Recent trading paints a mixed picture for PDF Solutions. The share price is up 61.66% year to date and the 1-year total shareholder return is 146.49%. However, momentum has cooled, with a 30-day share price return down 7.73% and a 90-day move down 25.52% as investors reassess how new products like Exensio Aurora reshape the growth and risk profile.
Scan beyond PDF Solutions and compare this AI manufacturing story with a hand-picked group of 89 AI infrastructure stocks that are also building the data and compute backbone for next-generation fabs.
PDF Solutions has climbed significantly over the past 12 months but has pulled back sharply in recent months. Is this a reset that makes the current price reasonable, or does it make more sense to wait for a cheaper entry before Exensio Aurora ramps?
Most Popular Narrative: 20% Undervalued
PDF Solutions closed at $47.77, while the most followed valuation narrative pegs fair value at $59.38, creating a meaningful gap that hinges on future earnings power.
Strategic integration of AI, guided analytics, and MLOps capabilities into the Exensio platform is driving both module renewals and upsells across a growing customer base, supporting margin expansion through high-value, differentiated offerings.
Read the complete narrative. Read the complete narrative.
Want to understand why this story points to a higher fair value for PDF Solutions? The crux is aggressive earnings expansion built on faster revenue compounding and sharply higher profitability. The narrative leans on richer margins, recurring software mix and a future valuation multiple that must compress yet still justify today’s gap.
Result: Fair Value of $59.38 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the PDF Solutions story can break if heavy R&D spending fails to translate into higher profitability or if geopolitical shocks affect its China exposure.
Find out about the key risks to this PDF Solutions narrative.
Another View: PDF Solutions Looks Expensive On Sales
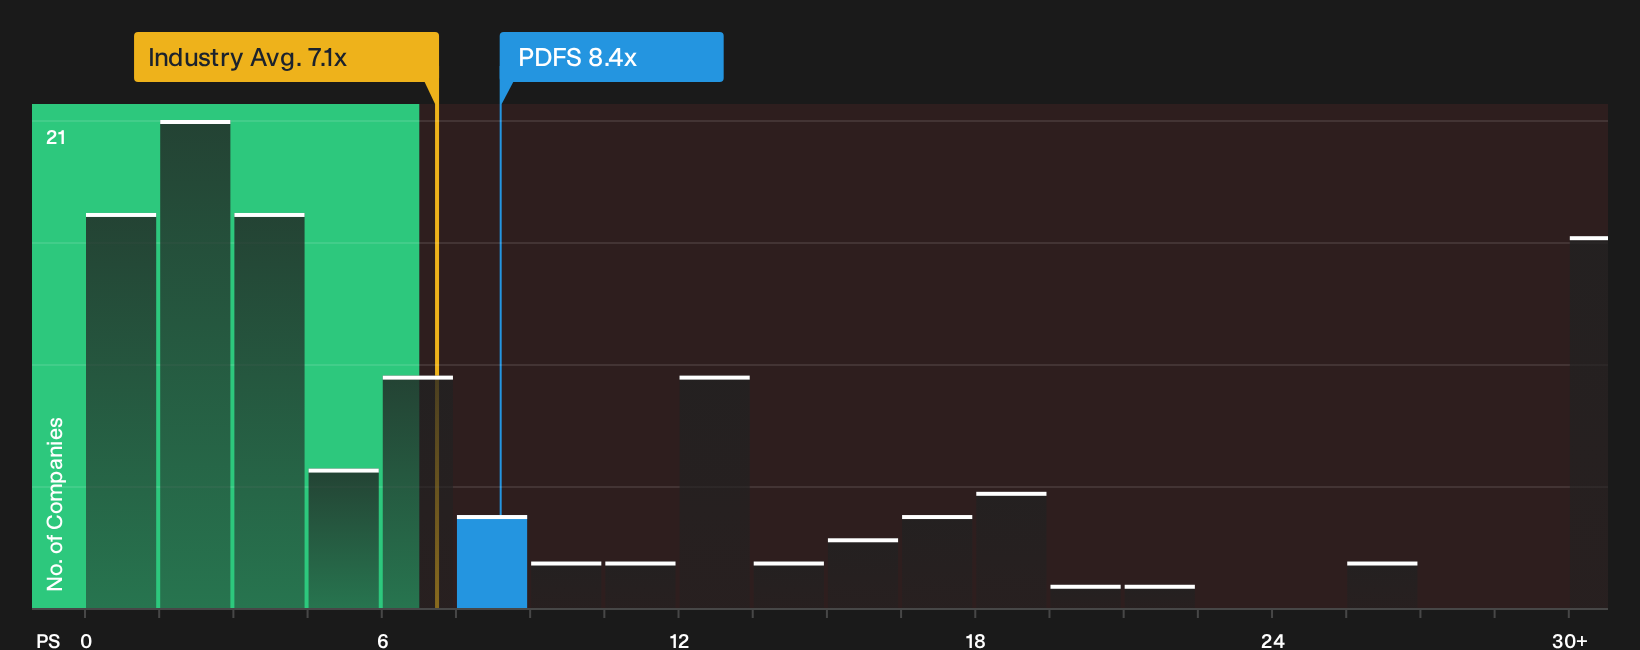
The fair value narrative paints PDF Solutions as undervalued, yet the price tag tells a different story. The P/S ratio sits at 8.4x, above the US Semiconductor group on 6.8x and well ahead of a 7.2x fair ratio. Is that extra premium really the safety margin you want?
For a closer look at how that sales multiple stacks up against both peers and the fair ratio the market could move toward, take a few minutes to go through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on PDF Solutions can feel confusing, so consider reviewing the underlying data yourself, starting with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond PDF Solutions?
If the PDF Solutions story has your attention, do not stop here. Broader context from other opportunities can sharpen your next move and keep your watchlist focused.
- Target potential mispricings by scanning a curated set of companies that screen as value opportunities using the 31 high quality undervalued stocks.
- Strengthen your defensive side by reviewing a list of solid balance sheet and fundamentals (23 results) that can help you focus on financially robust businesses when sentiment turns.
- Get ahead of the crowd by tracking a 16 high quality undiscovered gems that highlight quality enterprises the wider market may not be watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com