
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Horace Mann Educators (HMN) Below Fair Value As Its Dividend Holds Steady?
Horace Mann Educators (HMN) recently affirmed its regular shareholder payout, with the board declaring a quarterly cash dividend of US$0.36 per share. The dividend is payable on September 30, 2026, to investors on record as of September 16.
Recent trading has been softer, with Horace Mann Educators’ 1-day share price return down 1.53% and the 30-day share price return lower by 5.37%. However, the year-to-date share price return is up 7.95% and the 3-year total shareholder return sits at 82.52%, which suggests longer term holders have seen much stronger momentum than the latest pullback implies.
Scan beyond Horace Mann Educators’ dividend story and review a handpicked 6 dividend fortresses that are also rewarding shareholders with meaningful regular cash payouts.
The recent pullback leaves Horace Mann Educators up solidly over three years but softer in the past month. Is most of the rerating already in the rearview mirror, or does the current price still leave clear upside on the table?
Most Popular Narrative: 13.7% Undervalued
Analysts tracking Horace Mann Educators see fair value at $56.50 versus the latest close of $48.77, which frames the stock as below their assessed worth and hinges on a detailed set of growth and earnings assumptions.
Rising focus on retirement preparedness and demographic trends within the educator community, particularly more educators nearing retirement, are associated with inflows into annuity and retirement products, supporting asset accumulation and long-term growth in recurring fee income and earnings.
Curious what kind of revenue trajectory and margin profile would need to materialise for Horace Mann Educators to line up with that higher fair value? The narrative focuses on faster top line expansion, a modest squeeze in profitability per dollar of sales, and a future earnings multiple that edges above the industry norm. To see how those moving parts interact, the full story is worth a closer read.
Result: Fair Value of $56.50 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Horace Mann Educators story leans heavily on an aging educator client base, as well as exposure to higher catastrophe losses that could pressure premiums and profitability.
Find out about the key risks to this Horace Mann Educators narrative.
Another View On Horace Mann Educators Valuation
The analyst narrative sees Horace Mann Educators trading below a fair value of $56.50, yet the SWS DCF model points the other way. On that cash flow view, the shares around $48.77 sit above an estimated value of $39.19, which frames the stock as overvalued instead. Which story do you think fits your expectations for future cash generation?
Look into how the SWS DCF model arrives at its fair value.
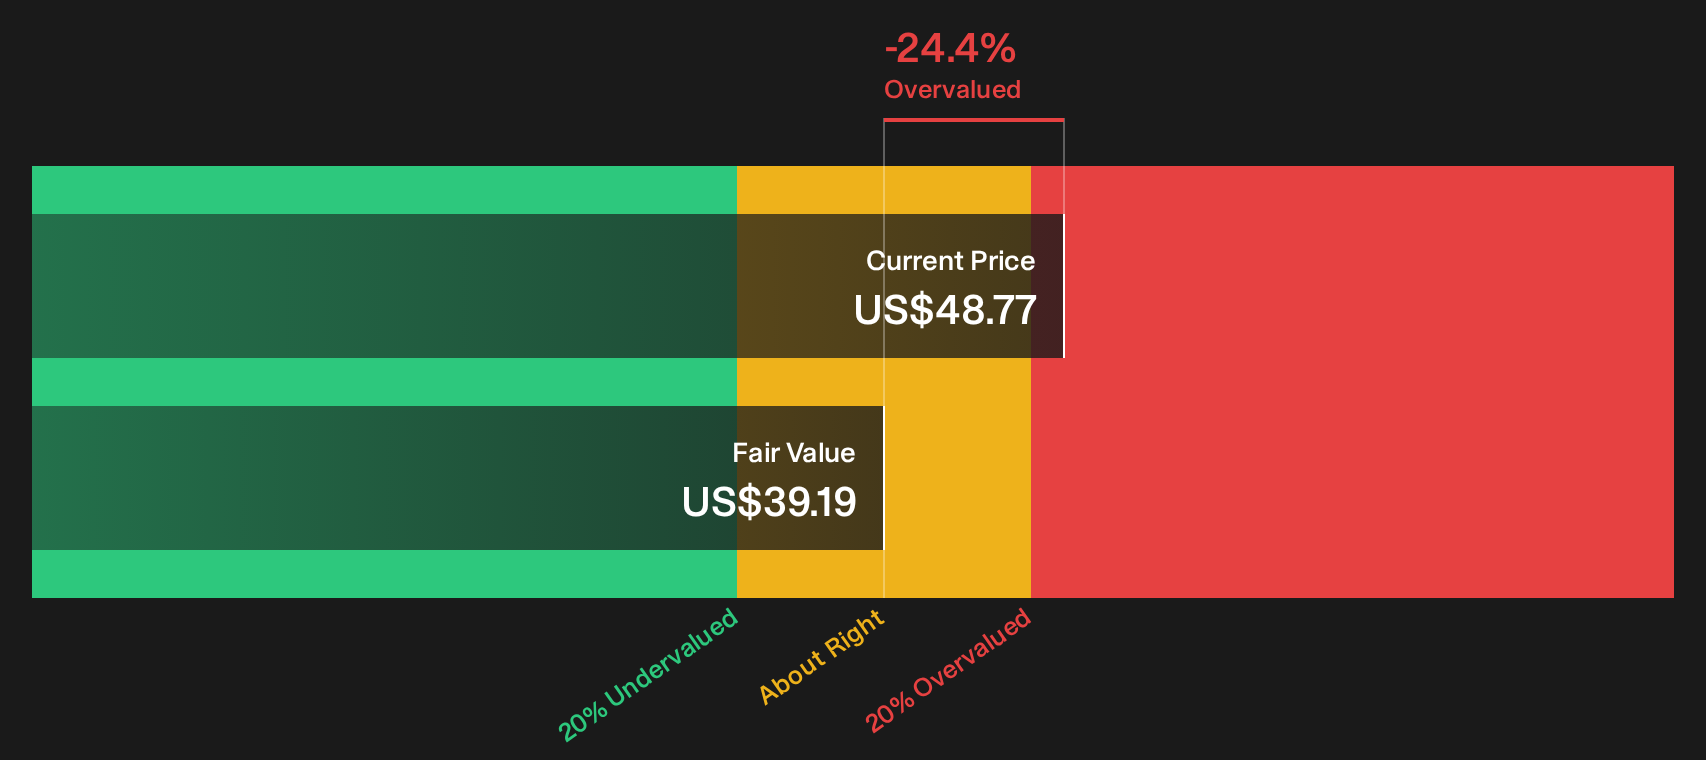
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Horace Mann Educators for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the Horace Mann Educators story can leave investors split. Move quickly, review the full picture and decide where you stand using the 5 key rewards and 1 important warning sign.
Looking for more Horace Mann Educators style investment ideas?
Do not stop with Horace Mann Educators. Use the screener to source fresh ideas that match your risk profile, return goals, and income needs before the next move.
- Target powerful upside potential by scanning a focused list of 21 elite penny stocks with strong financials that meet strict quality and financial strength checks.
- Zero in on pricing opportunities by reviewing 31 high quality undervalued stocks that pair solid fundamentals with share prices below analyst-assessed worth.
- Build a steadier portfolio foundation by filtering for a list of solid balance sheet and fundamentals (23 results) that can better support dividends and withstand tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com