
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Harley Davidson Stock Could Change Following Quarterly Results
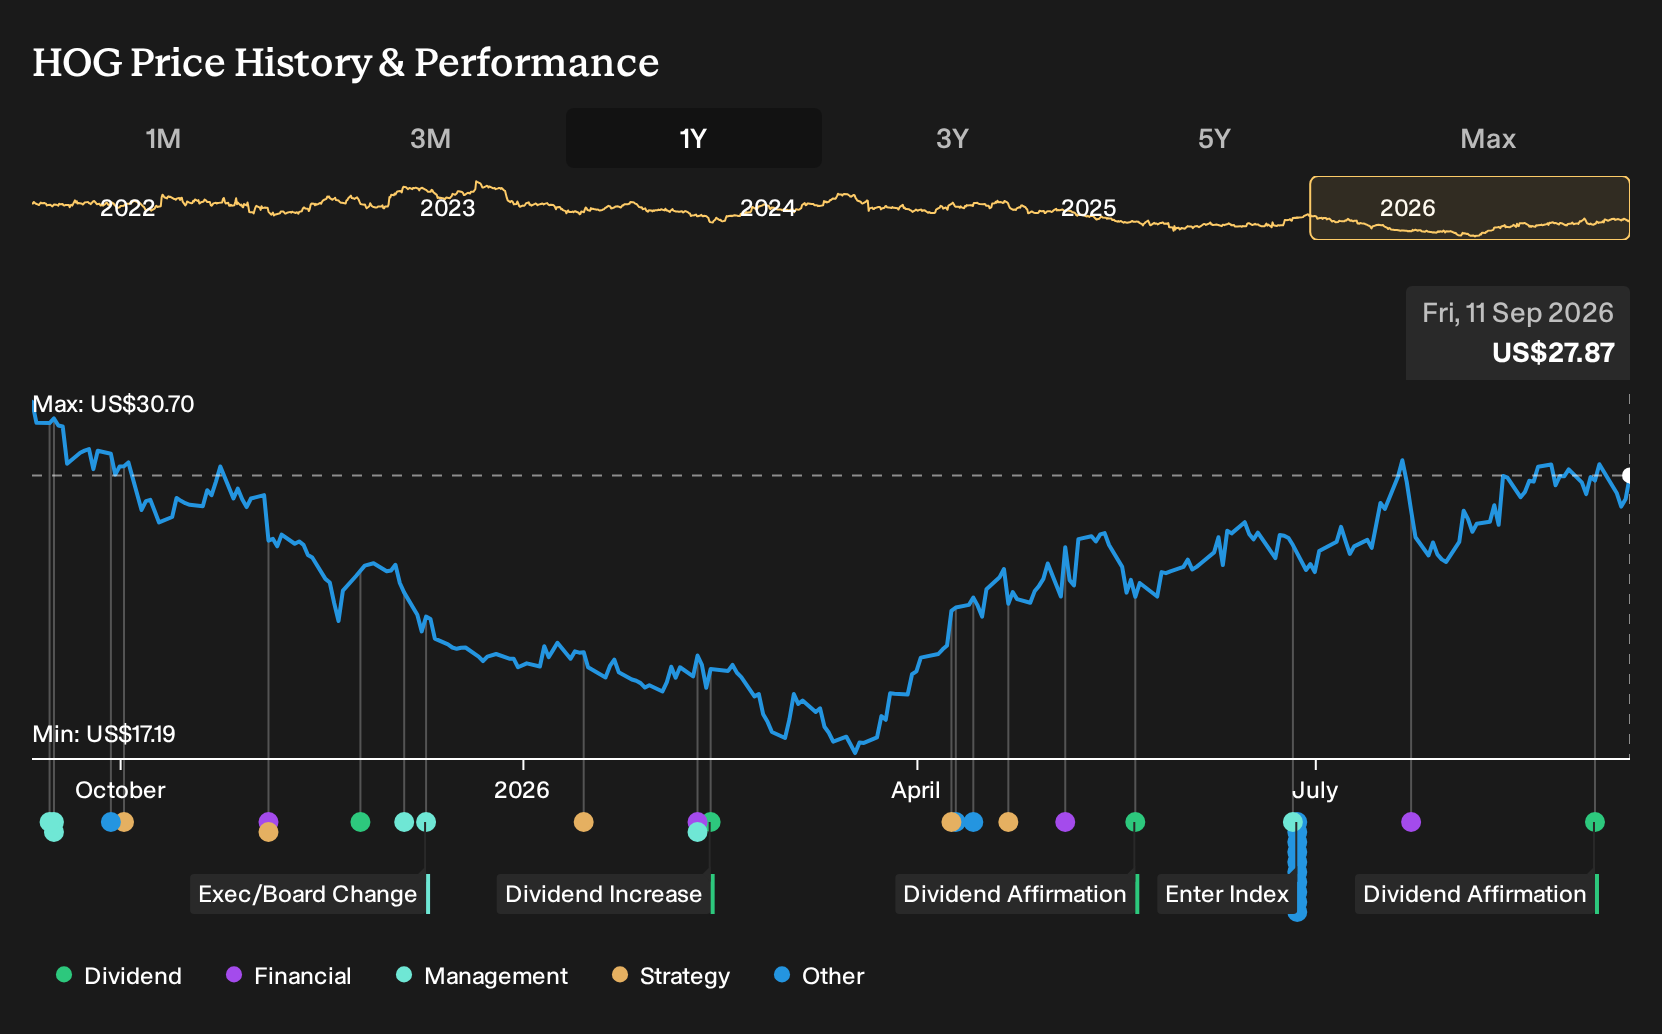
- Harley-Davidson's board previously approved a routine third quarter 2026 cash dividend of $0.1875 per share, paid on September 29 to shareholders of record as of September 15.
- Solid quarterly results came alongside falling motorcycle unit sales and pressure on free cash flow and return on invested capital. This highlights a tension between current payouts and future reinvestment capacity.
- We will explore how Harley-Davidson's investment narrative is affected by strong reported results alongside weaker motorcycle demand and financial efficiency.
Harley-Davidson Investment Narrative Recap
For Harley-Davidson to make sense in a portfolio, you need to be comfortable with a mature motorcycle business that is trying to offset weak unit demand with pricing, cost control, and a broader product mix. The short term story hinges on whether consumer appetite for big ticket bikes stabilises enough to support revenue, while Harley-Davidson works on attracting younger and more value conscious riders.
The biggest operational risk right now is that declining global motorcycle retail sales and soft demand in key regions linger, which would keep pressure on unit volumes and margins. The latest dividend affirmation does not materially change that near term risk and reward balance. It mainly reinforces that management still prioritises cash returns alongside reinvestment needs.
The most recent data point connected to this story is the third quarter 2026 dividend of US$0.1875 per share, payable on 29 September to investors of record on 15 September. That payout sits alongside commentary that free cash flow coverage of the dividend is not strong, which makes cash generation a key metric to track around each earnings release.
For you as a shareholder, the question is whether Harley-Davidson can keep funding both this recurring dividend and its efforts in areas such as lower priced models, LiveWire, and brand investment if motorcycle demand stays soft. The dividend decision keeps income-focused investors engaged, but it also puts a spotlight on execution, capital discipline, and how well the business can support shareholder distributions while managing tariff costs and broader macroeconomic headwinds.
Harley-Davidson's current analyst storyline points to US$4.0b in revenue and US$259.6 million in earnings by 2029, based on a forecast 1.9% yearly revenue decline and an earnings increase of about US$57 million from US$202.6 million today.
Uncover why Harley-Davidson's fair value indicates that Harley-Davidson is aligned with its current price.
Exploring Other Perspectives
Some of the most optimistic Harley-Davidson analysts focus on the HDFS shift as a key catalyst. They were assuming revenue of about US$3.9b and earnings of roughly US$338.5 million by 2028, with a higher 13.6x P/E. Those views and today’s dividend decision may eventually intersect, so treat them as moving pieces, not fixed truths.
Explore 3 other Harley-Davidson fair value estimates, including one that suggests up to 15% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Harley-Davidson research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Harley-Davidson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Harley-Davidson's overall financial health at a glance.
Looking For More Investment Ideas Beyond Harley-Davidson?
Once you have a view on Harley-Davidson, it can be useful to line it up against other opportunities that offer different mixes of income, quality, and risk. The Simply Wall St Screener lets you do that quickly by filtering for focused groups of businesses that match what you want from your next investment.
- If you want to tilt toward dependable balance sheets and solid fundamentals, start with this curated list of solid balance sheet and fundamentals (23 results) that can help you stress test your income holdings.
- For investors who care about getting paid while they wait, scan a focused 6 dividend fortresses and see which companies combine higher yields with resilience.
- If you prefer hunting for future market leaders before they are widely followed, work through a hand picked 16 high quality undiscovered gems that highlights smaller stocks with strong underlying business quality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com