
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Yokohama Rubber (TSE:5101) Stock May Trade At A Discount Despite A 288% Return
Yokohama Rubber Company has delivered a very strong 5 year share price run, yet the current valuation checks still lean toward the stock screening cheap rather than stretched. After recent pullbacks, investors are weighing whether that longer term climb is already reflected in today’s price or if the market is still underestimating the business.
- Over 5 years, Yokohama Rubber Company has returned about 288%, which puts a lot of past value creation on the table for anyone looking at the stock today.
- Future earnings power from its tyre and rubber operations can support current expectations, while any hit to margins or cash generation would quickly challenge the case for a low implied valuation.
- The broader valuation checks lean cheap, with the company passing 6 of 6 metrics on price versus fundamentals according to its value score of 6.
For investors, the debate is whether Yokohama Rubber Company’s strong multi year share price performance and recent weakness still leave enough potential to justify the current valuation multiples.
Compare Yokohama Rubber Company's valuation reset with hand-picked 17 high quality undervalued stocks that also combine strong fundamentals with prices that still look undemanding.
Is Yokohama Rubber Company a Bargain on Earnings?
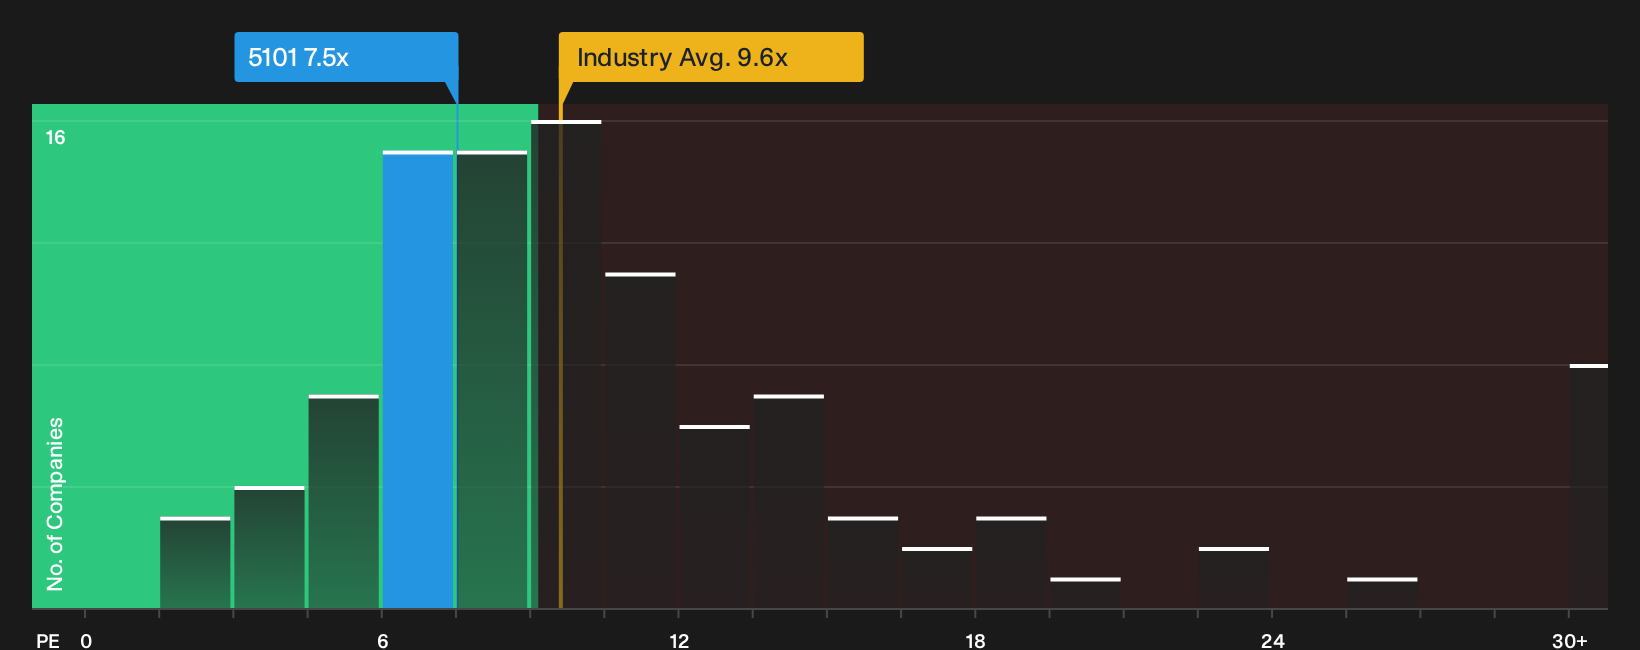
The P/E ratio is a useful lens for Yokohama Rubber Company because earnings remain a central yardstick for how the market values its tyre and rubber operations. On this measure, the stock trades on roughly 7.5x earnings, which is below the Auto Components industry average of about 9.6x. It also sits under the peer group average near 10.4x, so the market is pricing each yen of Yokohama Rubber Company profit more cautiously than many comparable businesses.
A more tailored yardstick, the fair P/E ratio, is estimated at about 14.1x based on the company’s profile, margins and risk characteristics. This is almost double the current multiple, which indicates investors are paying a relatively low price for each unit of earnings even after a strong multi year share price run. For anyone comparing options within the sector, Yokohama Rubber Company currently appears to be one of the cheaper earnings based ideas on this framework.
On the P/E yardstick, Yokohama Rubber Company stock appears inexpensive relative to both peers and its estimated fair multiple.
See what the numbers say about this price — find out in our valuation breakdown.
The Yokohama Rubber Company Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Yokohama Rubber Company's valuation puzzle leaves off by spelling out what would need to happen to future growth, profitability and earnings for the shares to be worth materially more or less than today’s level on the market. Rather than a single multiple or model output, each narrative lays out the assumptions that sit behind its view of fair value so you can compare those inputs with the actual results as they are reported.
Share a Simply Wall St narrative on Yokohama Rubber Company to present your own number-driven view on where its growth, margins and execution may go from here.
Use it to make your case now, and then observe how your thesis holds up as fresh financial results and valuation data become available.
Do you think there's more to the story for Yokohama Rubber Company? Head over to our Community to see what others are saying!
The Bottom Line
Yokohama Rubber Company screens as undervalued on earnings-based multiples, which suggests the current share price leaves room for differing interpretations of what the business is worth. The crux is whether profitability and cash generation from its tyre and rubber operations can support those low P/E signals over time. If margins and execution hold up, the discount could reflect caution rather than a clear flaw in the equity story. If they come under pressure, that same discount may reflect the market correctly pricing in the risk.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com