
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Northwest Natural Holding (NWN) Faces A Valuation Test After Recent Share Price Weakness
Northwest Natural Holding (NWN) has attracted fresh attention after recent share performance, with the stock down about 4% over the past month and roughly 3% over the past 3 months.
At the current share price of $48.44, Northwest Natural Holding has seen short term share price pressure, while the year to date share price return of 3.64% and 1 year total shareholder return of 19.33% point to momentum that has been building over a longer stretch.
Scan for other utilities that are showing similar price pressure but have stronger balance sheets by running the list of solid balance sheet and fundamentals (23 results) alongside your research on Northwest Natural Holding.
Bulls point to Northwest Natural Holding’s regulated footprint and recent 1 year total return, while bears focus on near term share price weakness and balance sheet questions. Which side does the current valuation favour next?
Most Popular Narrative: 15.8% Undervalued
Northwest Natural Holding’s most followed narrative pegs fair value at $57.50 per share, above the last close of $48.44. This puts a spotlight on what assumptions sit underneath that gap.
Ongoing investments in infrastructure modernization and system upgrades, combined with supportive regulatory outcomes (recent rate increase and higher allowed ROE), are likely to improve net margins, operating efficiency, and future earnings reliability.
Read the complete narrative. Read the complete narrative.
If you want to understand why this narrative sees more upside in Northwest Natural Holding, it leans heavily on steady meter additions, firmer profitability, and a richer future earnings multiple that investors usually reserve for faster growing utilities. It also raises the question of which specific revenue and earnings paths would have to play out for $57.50 to make sense.
Result: Fair Value of $57.50 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the bullish Northwest Natural Holding narrative can be knocked off course if regulators take a tougher line on cost recovery or if electrification meaningfully curbs long term gas demand.
Find out about the key risks to this Northwest Natural Holding narrative.
Another View: Multiples Point to a Richer Price
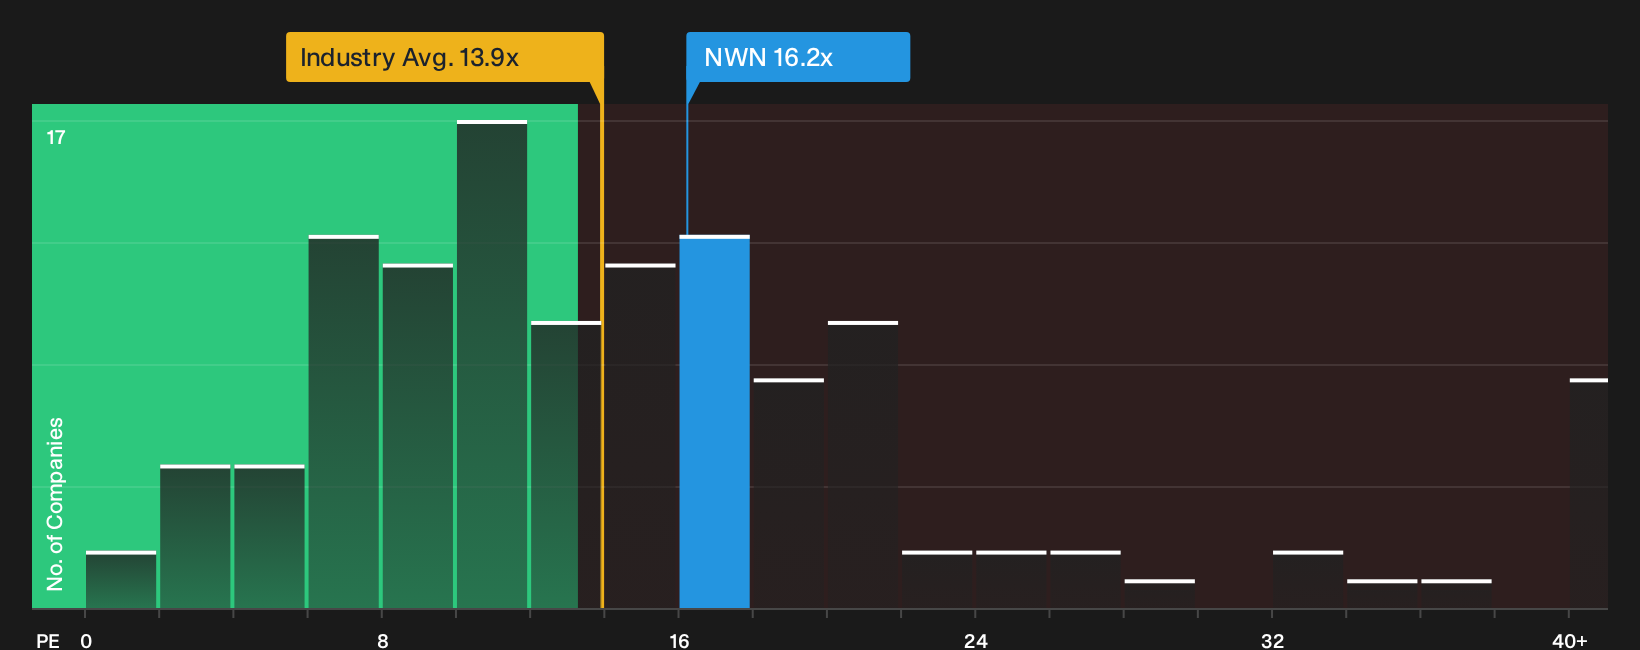
That 15.8% “undervalued” narrative for Northwest Natural Holding sits awkwardly beside what the market is already paying. The stock trades on a P/E of 16.2x, which is higher than both the global Gas Utilities average of 14.2x and a peer group at 15.5x, even though its own fair ratio is 18.6x.
So while the fair ratio suggests some room for the multiple to climb, paying above sector and peer levels today could still squeeze your margin of safety if sentiment cools or earnings progress slows.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Northwest Natural Holding’s outlook do not have to leave you stuck on the fence. Move quickly, review the latest numbers, and weigh both sides through the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Northwest Natural Holding?
Do not stop with Northwest Natural Holding. Use the Simply Wall Street Screener to surface fresh opportunities and keep your watchlist packed with ideas that actually fit your goals.
- Target dependable income streams by scanning for high-yield opportunities through the 6 dividend fortresses.
- Hunt for quality at a discount by checking the 31 high quality undervalued stocks before valuations move away from you.
- Focus on capital preservation and aim for peace of mind with the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com