
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Delta Air Lines Stock And 2 Travel Names Tied To Lower Oil Prices
Oil markets are swinging on every headline about Iran, Saudi infrastructure, and shipping lanes, and that volatility sits right on the fuel bill for global airlines and travel stocks exposed to this news. If crude prices ease after any de escalation, some carriers and online travel platforms could see breathing room on costs and demand. This article introduces 3 such stocks and explains how each might react if oil moves sharply from here.
The three stocks that follow are just a starting sample. The full screen surfaced 32 more airlines and travel platforms with equally detailed narratives that are not covered here. To identify and analyze potential beneficiaries of cheaper fuel directly, head straight into the Global Airlines and Travel Beneficiaries of Lower Oil Prices screener.
Delta Air Lines (DAL)
Delta Air Lines is a flagship example of how a large carrier in this screener can feel every move in jet fuel prices, with a huge global route network and loyalty engine that can turn lower oil into more breathing room on profits and cash flow.
Delta Air Lines runs a global passenger and cargo network and operates a refinery, with the Airline segment generating about US$61.7b and Refinery adding roughly US$8.2b in revenue, supporting a market value near US$51.2b.
"Delta Air Lines is focusing on protecting margins and free cash flow by maintaining flat capacity growth and aligning supply with demand, which is likely to positively impact net margins through cost management."
The areas where that discipline is applied most directly, and how fuel costs reset from here, will matter a lot for what happens to future earnings power.
That fuel reset is only one piece, and the full narrative for Delta Air Lines shows how Delta Air Lines’ refinery, network mix, and balance sheet decisions could be accelerating or masking the real upside.

Southwest Airlines (LUV)
Southwest Airlines is a pure play on lower fuel costs in this screener, operating a large low fare network where cheaper oil can quickly flow through to ticket pricing and potential demand, given its focus on price sensitive travelers across the U.S. and near international routes.
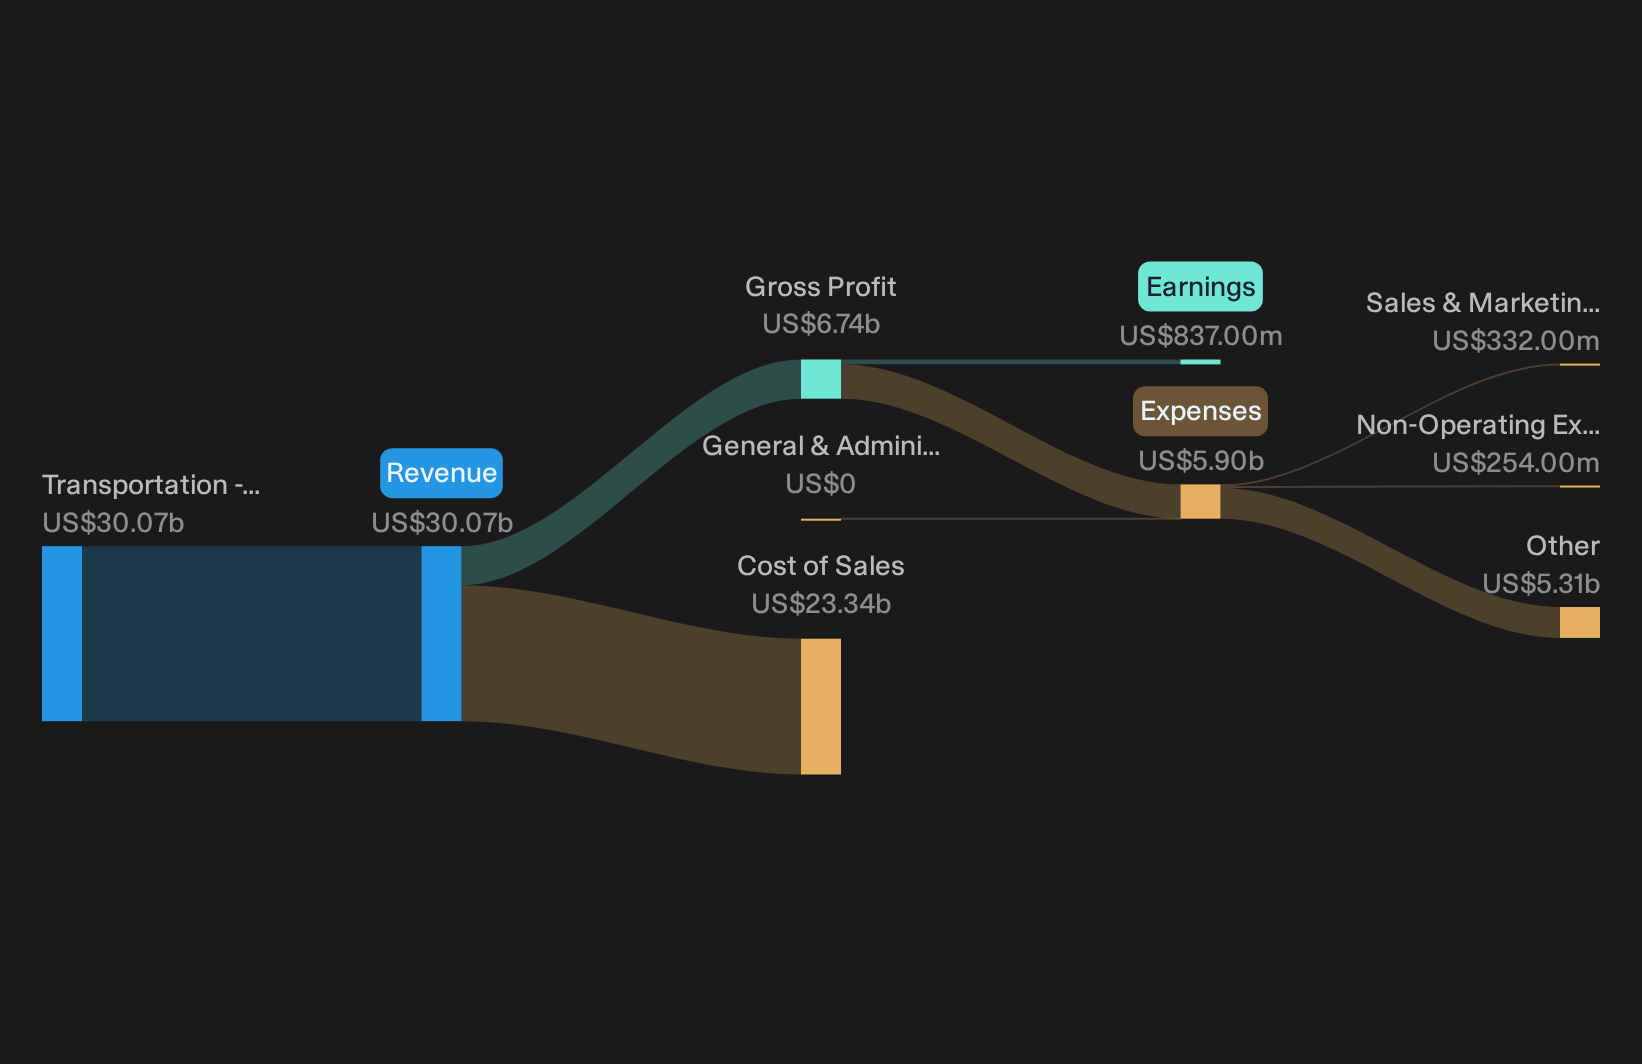
Southwest Airlines operates a large U.S. and near international passenger network, generating about US$30.1b from Transportation, Airlines and carrying a market value of roughly US$18.9b.
"Successful launch of the Expedia distribution channel and anticipated continuation of higher booking volumes from new customer bases could drive increased revenue and RASM as Southwest Airlines expands its customer reach and capitalizes on fresh demand channels."
What happens to margins if one key cost line moves in the right direction just as this broader revenue mix starts to mature?
If that inflection in costs and demand is what you are watching, the full narrative for Southwest Airlines shows where Southwest Airlines’ earnings power might be accelerating next.
LATAM Airlines Group (SNSE:LTM)
LATAM Airlines Group is one of the purest plays on the screener theme, with a vast passenger and cargo network across Latin America and long haul routes where fuel is a major cost line and any relief in oil prices can reshape profitability.
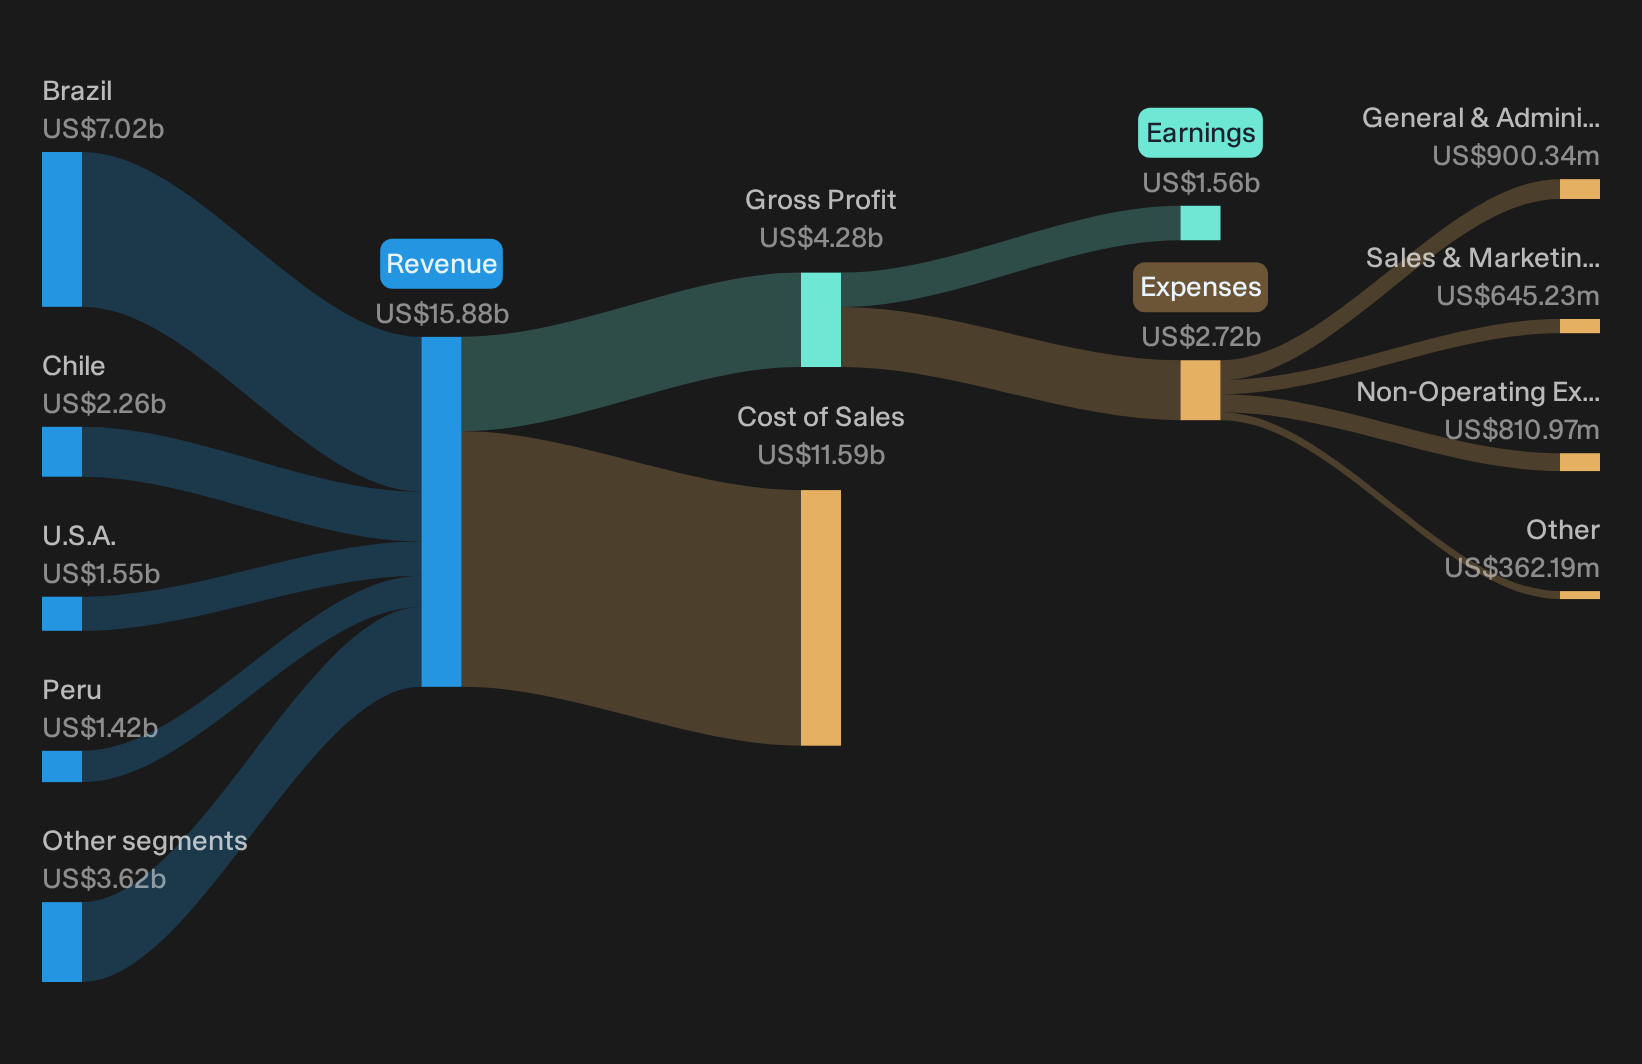
LATAM Airlines Group runs passenger and cargo air transport across 160 destinations, generating about US$15.9b from Air Transportation, and carries a sizeable market value in the tens of billions of US dollars when converted from roughly CLP13,746,730,649,993.
"LATAM's aggressive fleet modernization, with continued investment in next-gen fuel-efficient aircraft and strong digitalization initiatives in both operations and revenue management, is expected to support structural cost reductions and enhance its margin profile over time."
What matters next for LATAM Airlines Group is how one unresolved pressure on its cost base interacts with that push for higher quality margins.
If that cost pressure is the hinge, the full narrative for LATAM Airlines Group shows whether LATAM Airlines Group is quietly accelerating or still masking key risks and upside.
Seeking Alternatives Before Momentum Flips
Fresh opportunities move fast. Breakout stories gain momentum, then get caught by the crowd once prices start flying. Scan what is still under the radar for now and act now.
- Target sturdier payers with yields that do not rely on hype by scanning the 6 dividend fortresses while the income window still looks wide open.
- Hunt for future enablers of AI infrastructure using the 89 AI infrastructure stocks while these backbone providers remain under heavier traders' screens and before prices fully adjust.
- Track early movers in electrification and grid upgrades by working through the 39 power grid technology and infrastructure stocks before capital flows crowd into the same limited set of tickers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com