
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Molina Healthcare (MOH) Stock Looks Below Fair Value Despite Weaker Sales
Molina Healthcare comes into focus as a stock with solid gains over the past year but a sharp decline of about 38% over three years, while its valuation checks still flag it as cheap on the broader metrics. Recent revenue pressure and customer losses have unsettled sentiment, yet the current pricing screens as undervalued on core multiples.
- The share price has fallen roughly 38% over three years, which suggests longer term holders have absorbed a heavy drawdown that is not fully reflected in the recent 1 year recovery.
- Investor hopes now lean on Molina Healthcare stabilizing membership and revenue trends, while the key risk is that further customer losses or weaker top line momentum keep weighing on how much investors are willing to pay.
- On a composite of valuation checks, Molina Healthcare scores highly, and a 5 out of 6 rating signals that the broader checks lean cheap rather than expensive.
The issue now is whether Molina Healthcare's current price already reflects the membership and revenue challenges, or if the recent weakness still leaves room for value focused investors.
Compare Molina Healthcare's valuation reset with other potential ideas by scanning our hand picked list of 31 high quality undervalued stocks that also screen cheaply on core fundamentals.
Is Molina Healthcare Still Cheap on Sales?
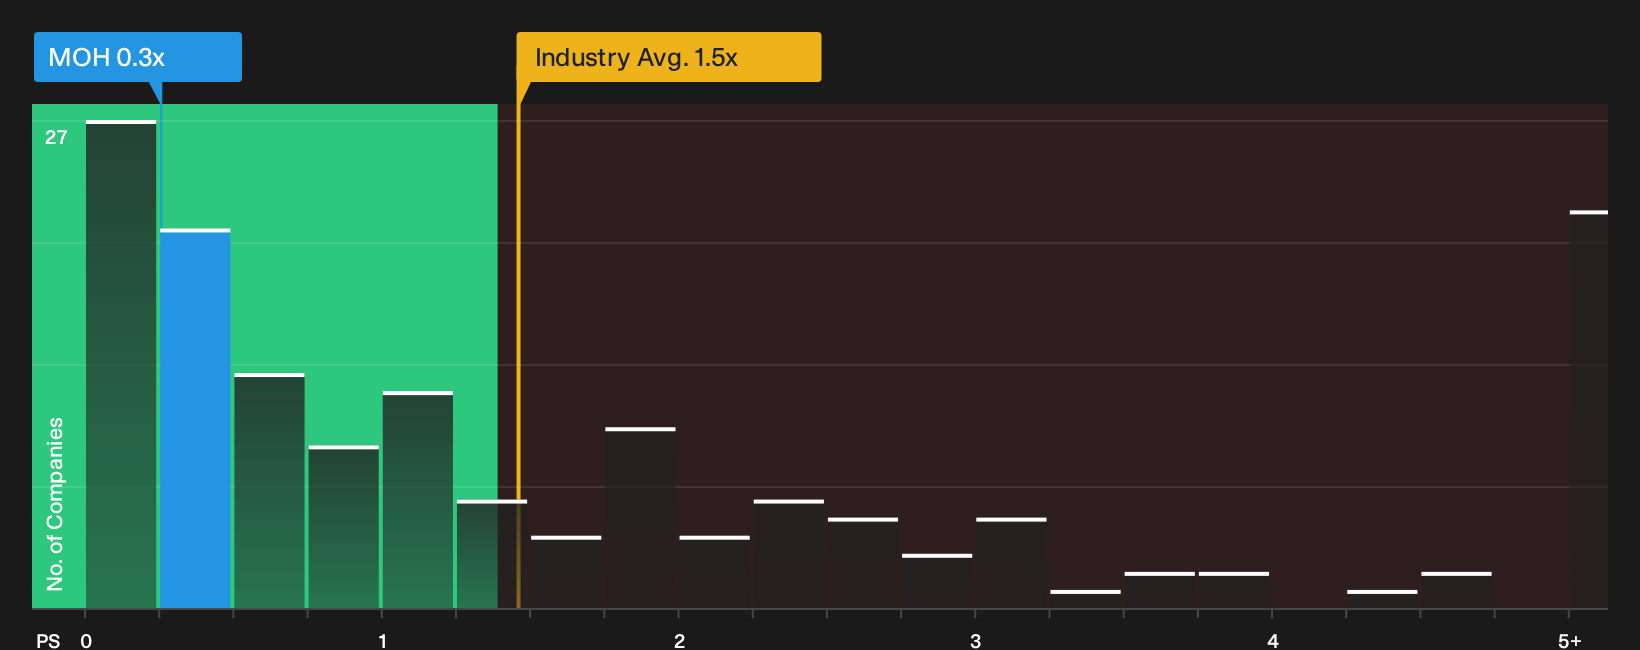
P/S works well for Molina Healthcare because the market often values health insurers on the revenue they generate from premiums rather than on headline earnings alone. On this metric, the stock trades on a P/S of about 0.3x, compared with a Healthcare industry average near 1.5x and a peer group closer to 1.9x. That is a steep gap in how each dollar of Molina Healthcare revenue is being priced compared with many other listed insurers.
The fair P/S ratio implied by the broader model is about 0.9x, which is still well above the current 0.3x level. Even after the recent Q2 update, where revenue slipped 4.8% and customer numbers declined by 108,000, the market multiple on sales remains compressed relative to both this tailored fair ratio and to sector norms.
On a pure P/S basis, Molina Healthcare stock appears undervalued, with the market pricing its revenue stream at a sizeable discount to both modelled fair value and Healthcare peers.
See what the numbers say about this price — find out in our valuation breakdown.
The Molina Healthcare Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Molina Healthcare's valuation gap leaves you by explaining which paths for growth, profitability and earnings would logically support a much higher or much lower price than today. Each narrative connects its number to a clear view on how Molina Healthcare's growth, margins and key risks might change, giving you a concrete reference point you can revisit as new data is added to the story on the Community page.
Community views on Molina Healthcare sit far apart, from stabilising Medicaid economics to prolonged pressure from rising medical costs and policy risk.
Bull case: roughly fairly valued
"Molina's successful track record of winning RFPs, including new contracts in Nevada and Illinois, is expected to drive significant revenue growth, with projected incremental annual premium revenue of approximately $800 million…"
Read the full Bull Case to see why Molina Healthcare could be undervalued
Bear case: 39% overvalued
"A persistent and unprecedented acceleration in medical cost trends, particularly for behavioral health, high-cost drugs, and increasing inpatient and outpatient utilization, is likely to keep outpacing rate adjustments in Medicaid and Medicare, resulting in sustained pressure on net margins and consolidated earnings in future years…"
Read the full Bear Case to see why Molina Healthcare could be overvalued
Do you think there's more to the story for Molina Healthcare? Head over to our Community to see what others are saying!
The Bottom Line
Molina Healthcare screens as undervalued on core multiples, with the market placing a relatively low price on each dollar of revenue compared with many peers. That discount only really closes if membership trends and premium income stabilize enough for investors to regain confidence in the earnings power behind those sales. The bear case hangs on medical costs and policy pressures keeping that re rating on hold. The key question from here is whether the current gap signals genuine mispricing or a fair cushion for the execution and reimbursement risks already on display.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com