
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Plains GP Holdings (PAGP) Stock Still Trades Below Fair Value Today
Plains GP Holdings has delivered a very strong run over the past few years, yet the broader valuation checks still suggest the stock screens as cheap on several measures. For anyone tracking the recent gains, the question is whether that combination of past returns and a strong value profile still leaves room for a reasonable entry point today.
- Over the past 5 years, Plains GP Holdings has returned about 297.0%, which puts recent enthusiasm squarely in focus for anyone weighing fresh capital.
- Future cash flow from its energy infrastructure assets can support the current pricing. However, exposure to commodity volumes and potential capital spending needs may pressure how much investors are willing to pay for that cash flow.
- The company carries a high value score of 5, which means the broader checks lean cheap rather than expensive.
The issue now is whether the current share price already reflects those strong historical returns in Plains GP Holdings, or if the valuation still leaves a sensible margin for new investors.
Scan beyond Plains GP Holdings by reviewing 31 high quality undervalued stocks, which share a similar mix of strong multi year returns and valuation support.
Is Plains GP Holdings Still Cheap on Sales?
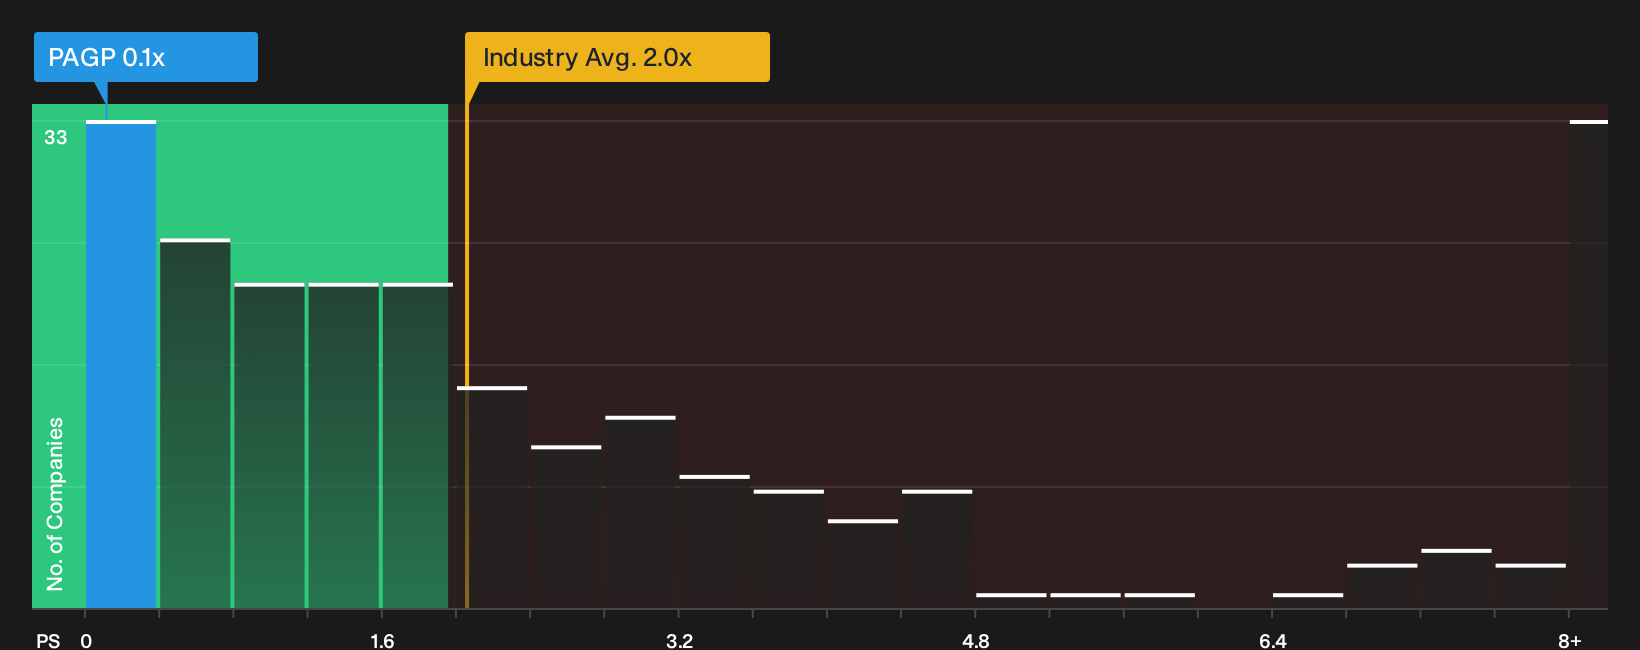
The P/S ratio fits Plains GP Holdings because the business is heavily tied to volume driven fee revenue, which makes sales a cleaner yardstick than earnings in some periods. The current P/S multiple is about 0.1x, compared with roughly 2.0x for the wider Oil and Gas industry and about 3.0x for direct peers. That is an extremely low revenue multiple for a listed energy infrastructure operator, especially given how capital intensive the sector tends to be.
A tailored fair P/S ratio for Plains GP Holdings, based on its size, margins, industry and risk profile, is estimated at around 0.6x. The difference between that level and the current 0.1x indicates that the market is applying a steep discount to the stock relative to what this framework implies for the revenue base. For investors who put weight on sales based metrics, the P/S screen highlights a wide valuation cushion.
On the P/S multiple alone, Plains GP Holdings appears undervalued relative to both its industry and a more tailored fair ratio estimate.
See what the numbers say about this price — find out in our valuation breakdown.
The Plains GP Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Plains GP Holdings leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than today’s quote. Each storyline links its number to a clear stance on how Plains GP Holdings' growth profile, margins and risk picture might evolve, giving you a reference point you can revisit as fresh information appears.
One of the top community narratives on Plains GP Holdings: 12% overvalued
"The planned divestiture of the NGL segment and redeployment of ~$3 billion in proceeds into core crude oil operations and bolt-on acquisitions are expected to streamline operations, reduce commodity price exposure, and enhance financial flexibility, supporting growth in core revenue and improved net margins via higher-return investments and potential buybacks…"
Read one of the top narratives on Plains GP Holdings
Do you think there's more to the story for Plains GP Holdings? Head over to our Community to see what others are saying!
The Bottom Line
Plains GP Holdings still screens as undervalued on market multiples, with the P/S gap to both peers and a tailored fair ratio implying investors are paying a low price for each dollar of revenue. That discount only becomes attractive if the cash flows behind those fees remain resilient against swings in commodity volumes and any future spending needs. The crux for you is simple: either the current markdown reflects excess caution and leaves room for a re rating, or it correctly prices the risk that capital intensity and volumes keep a lid on how far the valuation can stretch.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com