
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Fortive (FTV) Adds Audit Committee Veteran, Is The Stock 15% Undervalued?
Fortive (FTV) just added Susan L. Main to its board and Audit Committee, expanding the group to nine directors. Investors now have fresh governance and oversight credentials to factor into any view on the stock.
Recent trading tells a mixed story for Fortive. The share price is US$54.69 after declining 11.13% over the past 30 days, yet the 1-year total shareholder return of 12.5% suggests longer term holders have still seen gains as sentiment has shifted back and forth.
Scan other industrial and healthcare operators with similar governance and balance sheet focus by reviewing our curated list of list of solid balance sheet and fundamentals (23 results) alongside Fortive.
Fortive appears to be a solid operator, with steady revenue and net income growth and a seasoned finance voice now on the board. Yet the share price has slid recently, raising the question of whether that quality now comes at a reasonable valuation.
Most Popular Narrative: 15% Undervalued
Fortive’s most followed valuation storyline pegs fair value around $64.36, which sits above the recent $54.69 close and frames the recent pullback very differently.
Ongoing operational excellence via the Amplified Fortive Business System and disciplined capital allocation, including targeted bolt-on acquisitions in niche software and analytics, are expected to deliver further cost productivity, improved net margins, and robust free cash flow conversion.
Read the complete narrative. Read the complete narrative.
Want to see what kind of revenue mix, margin lift, and earnings path are built into that fair value gap? The narrative leans on recurring software exposure, richer profitability, and a future earnings multiple that assumes Fortive can keep compounding cash flows at a measured but consistent pace.
For a deeper breakdown that ties this valuation story into Fortive’s board refresh, debt load, and segment mix, use the Simply Wall St narrative as a starting point and then layer on your own assumptions about growth, return on equity, and risk tolerance. Result: Fair Value of $64.36 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Fortive’s heavier reliance on Intelligent Operating Solutions after the Precision Technologies spin, along with ongoing U.S.–China trade friction, could both challenge that fair value story.
Find out about the key risks to this Fortive narrative.
Another View: Fortive Through A P/E Lens
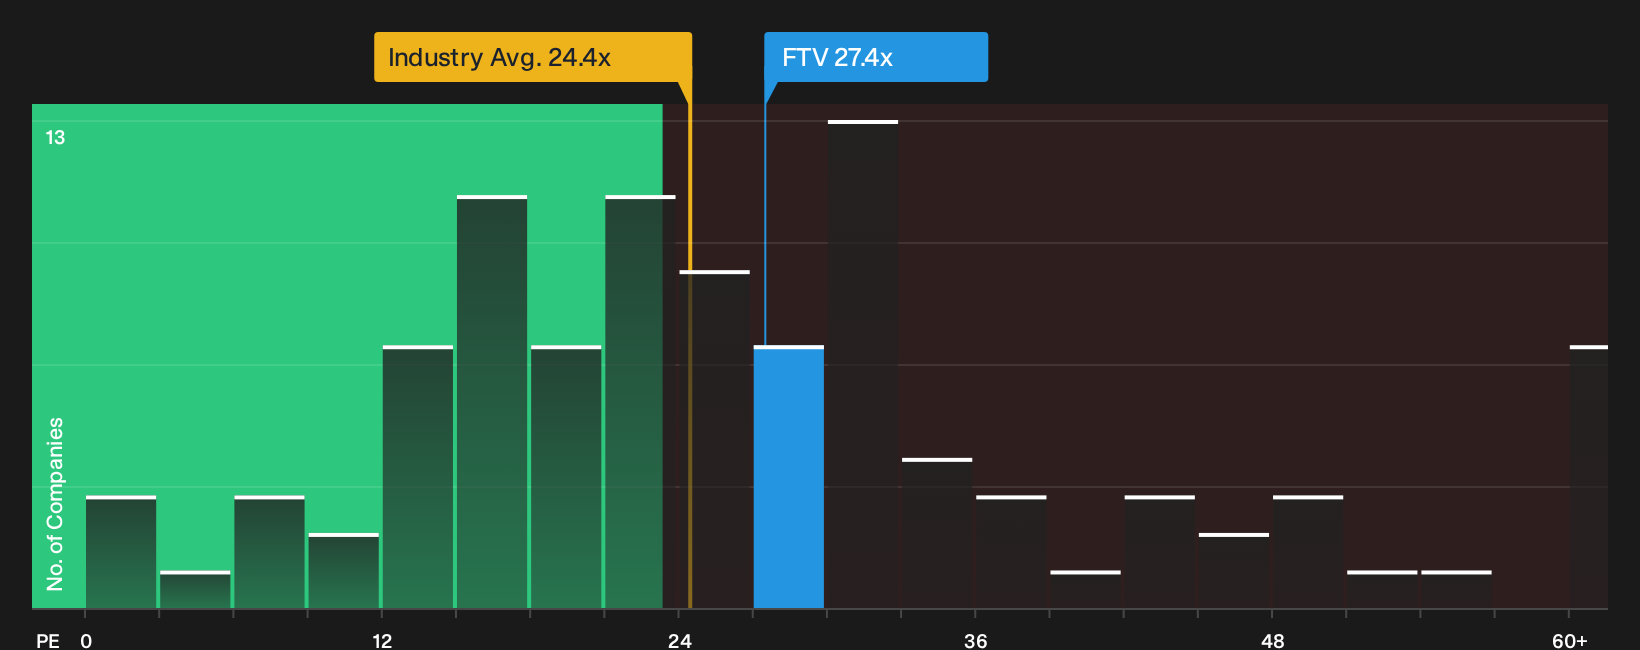
The DCF work suggests Fortive is trading below an estimate of fair value, but the earnings multiple tells a cooler story. The stock sits on a P/E of 27.4x versus about 24.4x for the US Machinery group and a fair ratio of 22.1x, which points to valuation risk if sentiment cools.
The gap between 27.4x and the 22.1x fair ratio implies investors are already paying up for Fortive compared with peers and where the market could migrate over time. If that premium narrows, would the DCF upside still feel as comfortable?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Reading mixed signals on Fortive and wondering what to make of them yourself? Move quickly, review both sides of the story, and weigh the 3 key rewards and 1 important warning sign.
Looking for more Fortive-like investment ideas?
If Fortive has your attention, do not stop here. Consider broadening your watchlist to avoid overlooking other opportunities that could suit your style.
- Target resilient potential by reviewing the 11 resilient stocks with low risk scores, which can help keep volatility in check while still offering meaningful exposure to listed businesses.
- Spot potentially mispriced opportunities early through the 16 high quality undiscovered gems, which combine healthy fundamentals with limited market attention.
- Focus on quality balance sheets using the list of solid balance sheet and fundamentals (23 results), which highlights companies with robust financial footing and cleaner debt profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com