
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Crown Castle (CCI) Stock Trades At A Discount To Fair Value After A 49% Fall
Crown Castle trades with a long stretch of weak share performance set against valuation checks that point to a discount, as both an intrinsic value estimate and market multiples suggest the stock may be priced below what the business fundamentals imply.
- The share price has fallen 49.4% over 5 years, which means long term holders have seen a significant drawdown that now frames any value discussion.
- Future cash flow from its tower and fiber assets can support the current price if it holds up, while any pressure on funding costs or required investment in its network may weigh on what investors are willing to pay.
- The broader checks lean cheap, with a high value score of 5 out of 6, which suggests Crown Castle screens as undervalued across several methods.
The issue now is whether the market discount to the intrinsic value estimate for Crown Castle is wide enough to compensate investors for the risks in the underlying cash flows.
Scan beyond Crown Castle and compare it with 31 high quality undervalued stocks that also combine weak recent share performance with valuation checks pointing to potential mispricing.
Is Crown Castle Still Cheap on Cash Flow?
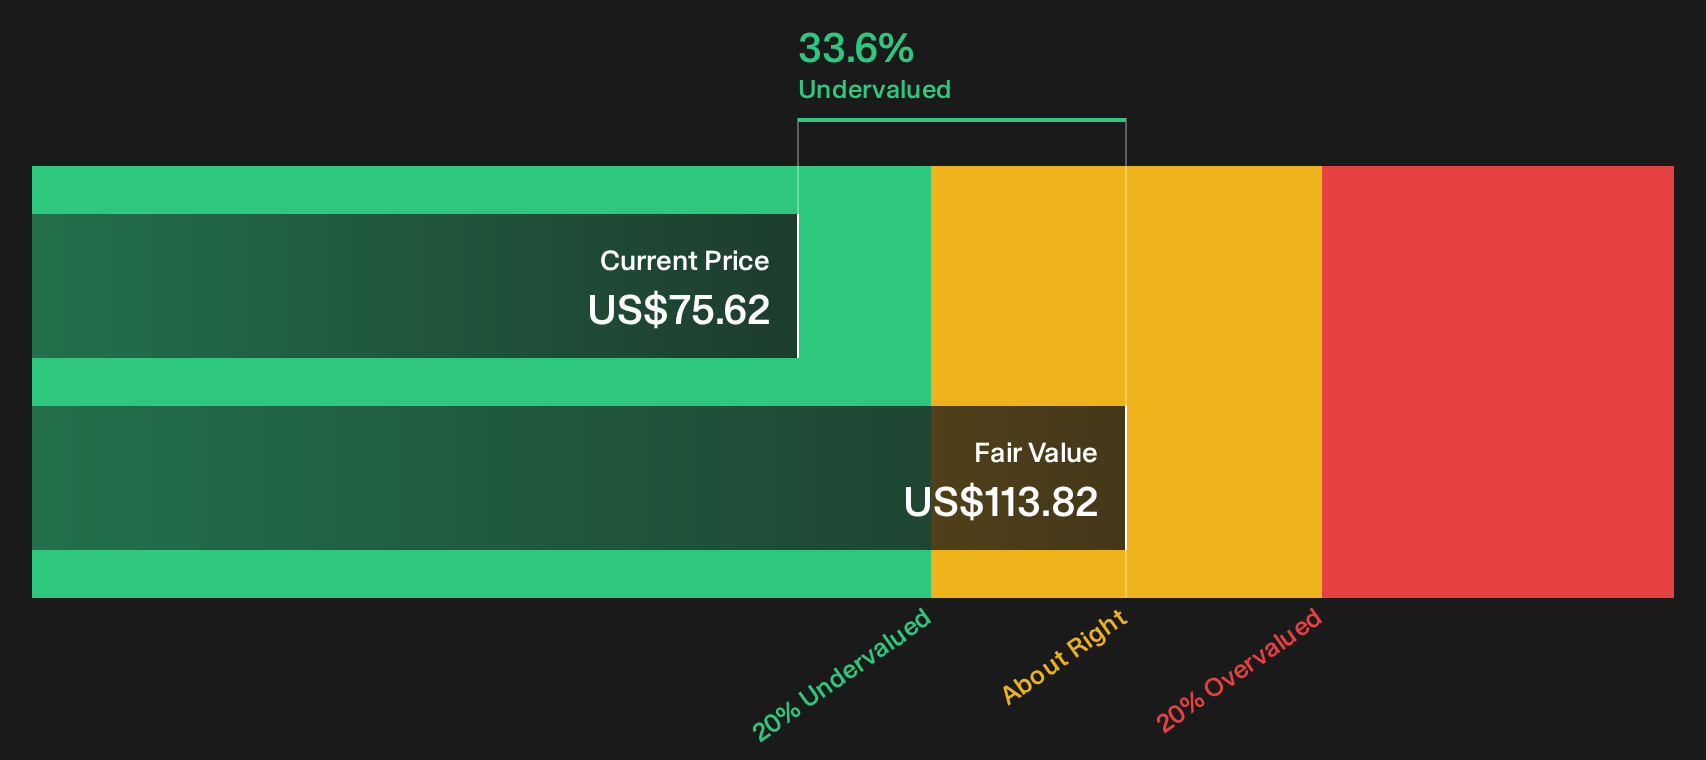
The Discounted Cash Flow (DCF) model here is built off Crown Castle’s adjusted funds from operations. On that basis, the latest twelve month free cash flow sits at about $1.9b, with the projection assuming growing but relatively measured cash flows rather than a sharp acceleration. Plugging those estimates into the two stage framework produces an intrinsic value of about $114 per share.
With the stock price sitting below that figure, the DCF output implies Crown Castle trades at roughly a 33.6% discount to the model’s fair value estimate. For readers, the key question is how comfortable you are with the growth path embedded in those cash flow assumptions and whether potential swings in funding costs or required network spend could erode that gap.
On these DCF assumptions, Crown Castle stock currently screens as undervalued relative to its estimated intrinsic worth.
Our Discounted Cash Flow (DCF) analysis suggests Crown Castle is undervalued by 33.6%. Track this in your watchlist or portfolio, or discover 31 more high quality undervalued stocks.
Is Crown Castle Still Cheap on Earnings?
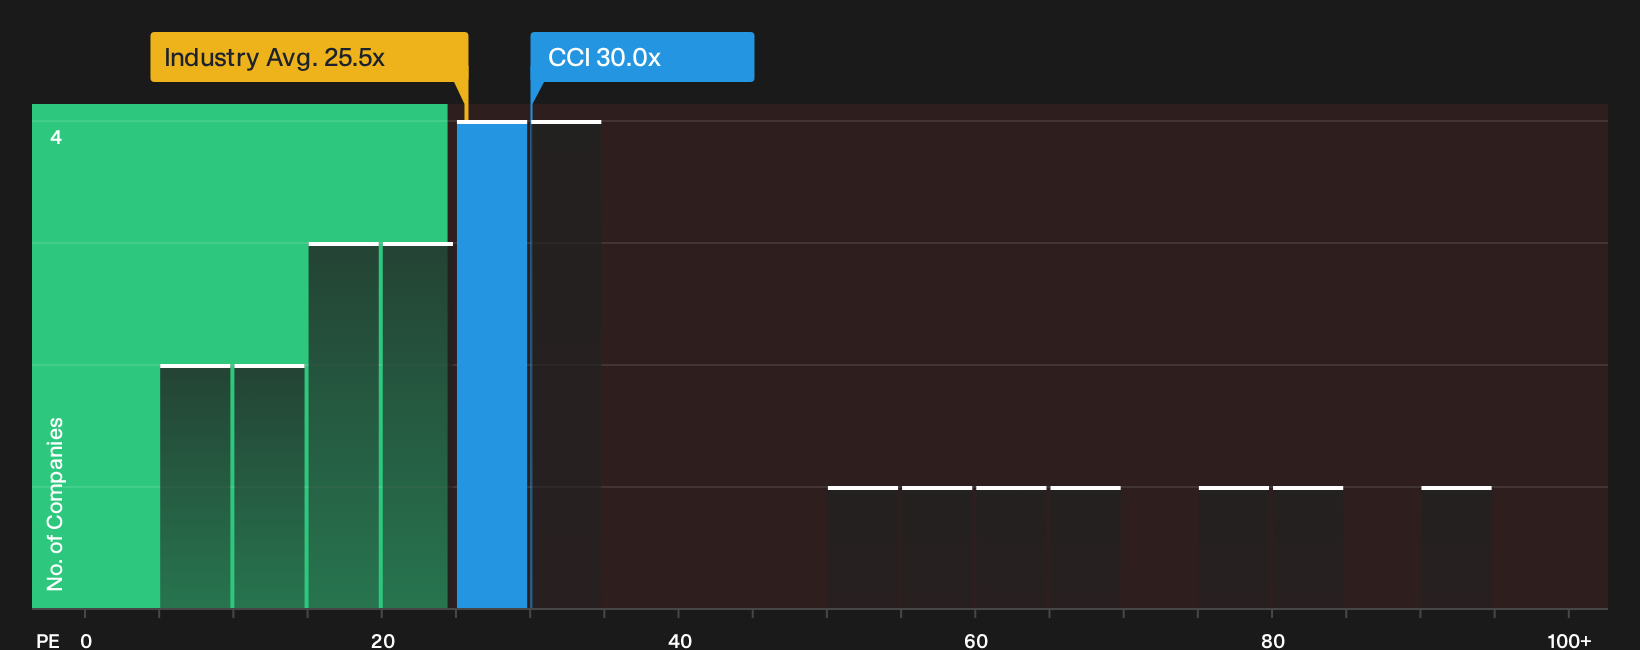
The P/E ratio suits Crown Castle because investors often focus on earnings power for mature, cash generative REITs. On this lens, the stock trades on a P/E of about 30.0x, which is above the specialized REITs sector average of 17.2x but below a peer group average of roughly 34.0x. That difference indicates the shares carry a premium to the broader industry, yet do not fully match how similar businesses in the peer set are valued.
The fair P/E ratio implied by the model is closer to 39.0x. Compared with the current 30.0x, that gap suggests the market is pricing Crown Castle below the level that would typically align with its earnings profile, scale, and risk inputs. For readers evaluating the stock, this indicates that the market multiple does not fully reflect the valuation suggested by the tailored P/E benchmark.
On the P/E yardstick, Crown Castle stock appears undervalued relative to the fair multiple implied by its fundamentals and peer context.
See what the numbers say about this price — find out in our valuation breakdown.
The Crown Castle Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St take the valuation puzzle around Crown Castle and turn it into clear, testable stories about what would need to happen to future growth, margins and earnings for the stock to be worth materially more or less than today’s price. These narratives sit on the Community page. Each narrative links its number to a specific view on where Crown Castle's cash generation, profitability and risk profile go next, which you can revisit as fresh information comes through.
You can add your own number driven narrative on Crown Castle, set out a clear view on where its growth, margins and execution go from here, and see how that thesis stacks up as fresh data arrives.
Do you think there's more to the story for Crown Castle? Head over to our Community to see what others are saying!
The Bottom Line
Crown Castle screens as undervalued on both the Discounted Cash Flow (DCF) intrinsic value estimate and the tailored P/E comparison, which points to a consistent message across very different yardsticks. The gap between current pricing and those frameworks only really makes sense if you think future cash generation will be pressured by funding costs or heavier network investment than the models assume. The big swing factor from here is whether that discount reflects genuine concern about the durability of its tower and fiber cash flows, or whether the stock simply needs a shift in sentiment for the valuation gap to narrow.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com