
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does Higher Oil Prices Change The Bull Case For Chevron (CVX)?
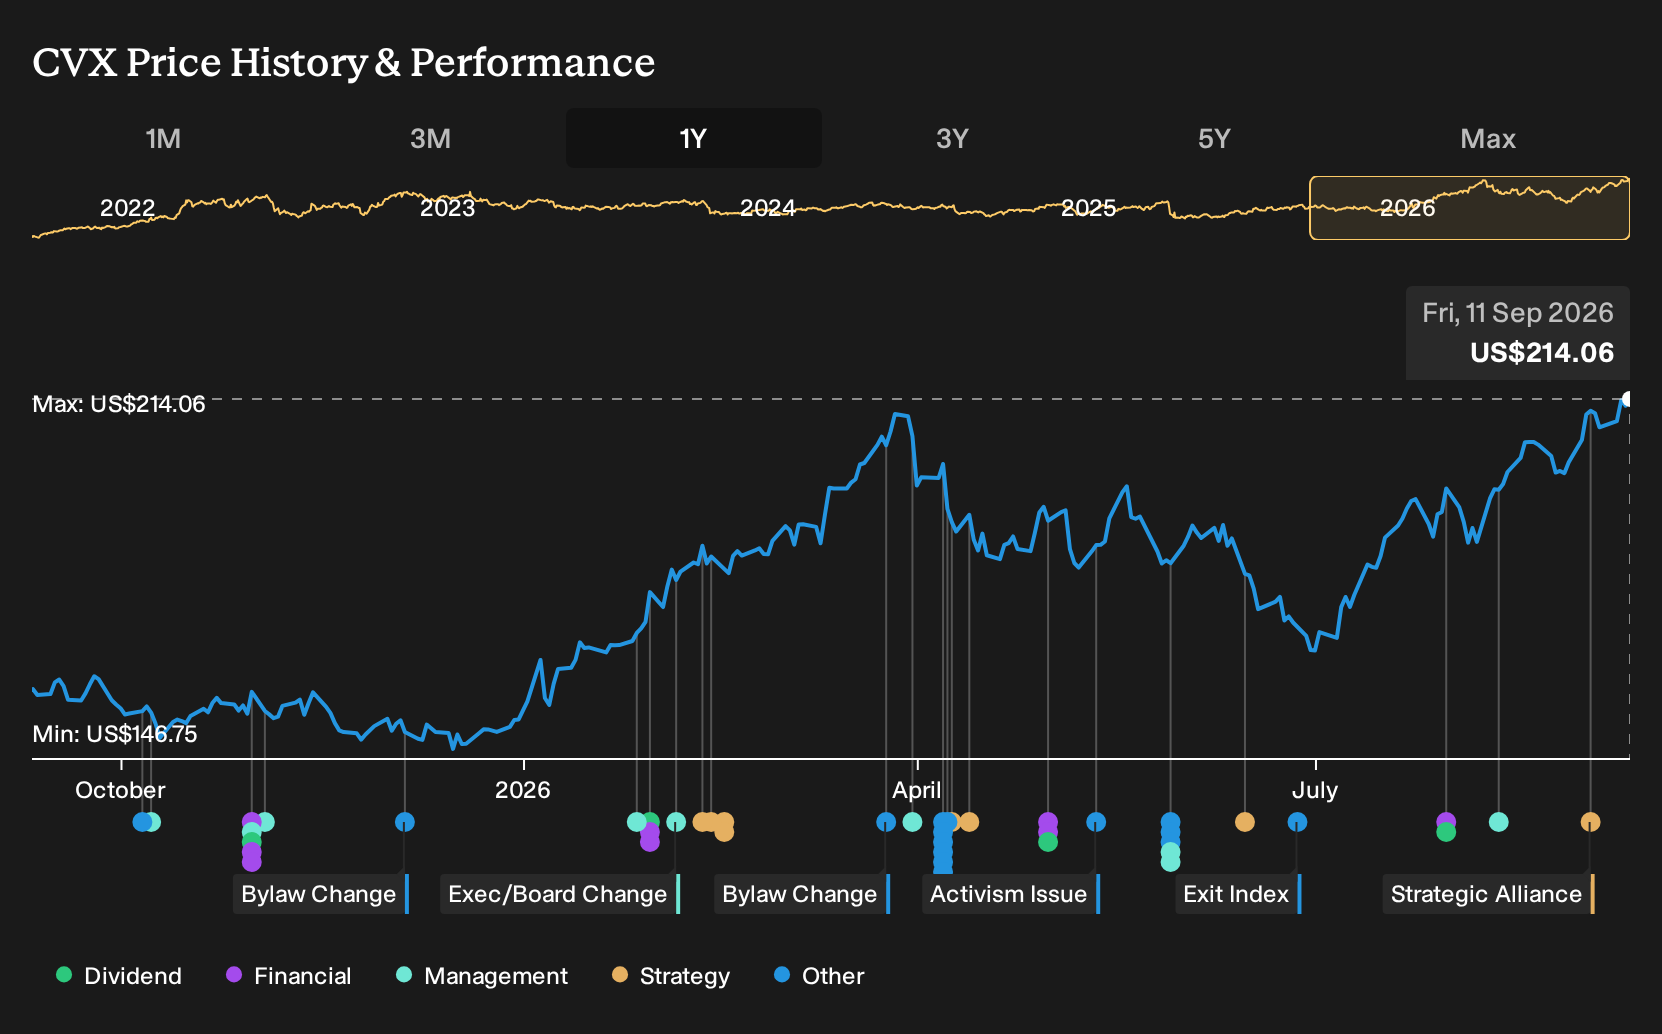
- Chevron updated its joint venture terms in Venezuela, committed over US$7,000 million of planned investment, and received additional Orinoco Belt acreage after production from its three ventures rose 15% year to date.
- The business is pairing heavier Venezuelan oil expansion with long-term power deals, such as its 20 year Microsoft agreement. This points to more diversified cash flow sources beyond traditional upstream output.
- We will look at how Chevron's investment narrative is shaped by this Venezuela build out and long term power contract focus.
Scan how Chevron's Venezuela push and long-term power deals compare with other heavy hitters by reviewing a curated list of 39 power grid technology and infrastructure stocks in the energy transition build out.
Chevron Investment Narrative Recap
Owning Chevron means believing the integrated model can keep turning oil and gas assets into steady cash, even as demand patterns evolve. The Venezuela acreage expansion and over US$7,000 million of planned spending point to a business still leaning into large, long life projects. The near term swing factor remains commodity prices and uptime across key hubs.
The biggest risk right now sits in execution and geopolitics. Venezuela exposure raises country risk on top of existing large project commitments elsewhere. If operational or regulatory issues slow volumes or inflate costs, the payoff from this Venezuela build out could be delayed and the short term production catalyst less meaningful.
The 20 year natural gas power agreement with Microsoft is the announcement that ties most closely to the current story. Chevron is using Permian gas and behind the meter power to supply a hyperscale data center in West Texas. That creates a defined, contracted outlet for gas that can be hard to move at attractive prices.
For you as a shareholder, the interest is in how that contract interacts with upstream volatility. A long dated power deal can help smooth cash flow while heavy Venezuelan spending increases capital needs and operational exposure. Execution on both fronts, and how reliably Microsoft related power cash arrives, will influence how resilient Chevron feels through the next oil price swing.
Chevron's current analyst narrative points to revenues of US$199.4b and earnings of US$25.3b by 2029. That implies revenue declining 1.6% per year and an earnings increase of about US$4.7b from US$20.6b today.
Uncover why Chevron's fair value indicates a 3% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$221 to US$349 per share. This represents a wide band for Chevron, and private investors are clearly not aligned. Some focus on Venezuela execution risk and long-term oil demand uncertainty, while others see the Microsoft power deal and cost cuts as possible cash flow supports. You should expect sharp disagreement and treat these as starting points to explore more viewpoints, not conclusions.
Explore 2 other Chevron fair value estimates, including one that suggests as much as 63% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Chevron research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Chevron. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Chevron's overall financial health at a glance.
Looking for more Chevron investment ideas?
If the Chevron story has sharpened your thinking but you want a broader watchlist, the Simply Wall St screener can help you quickly filter for other opportunities that fit your risk profile and income needs.
- For investors who want resilient businesses first and excitement second, consider filtering for 11 resilient stocks with low risk scores that may better match a cautious approach to capital.
- If reliable balance sheets appeal to you more than headline growth stories, run a search across a list of solid balance sheet and fundamentals (23 results) and see which tickers deserve a deeper look alongside Chevron.
- Those hunting for potential mispricings can scan a curated 31 high quality undervalued stocks and build a watchlist of candidates to research in more detail.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com