
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Raised Earnings Outlook Require Action From Amphenol (APH) Investors?
- Amphenol Corporation recently presented at Citi’s 2026 Global TMT Conference in New York, outlining its role across electrical, electronic and fiber optic connectors.
- Management focus on high-speed, power and fiber interconnect demand tied to AI-related IT datacom, defense and industrial applications highlights how current orders and customer commitments are shaping near-term operating visibility.
- We will now look at how Amphenol's investment narrative is influenced by rising earnings expectations that are supported by sustained AI datacom product demand.
Scan the AI infrastructure opportunity around Amphenol by lining it up against our hand-picked 89 AI infrastructure stocks that is shaping high-speed data and power connectivity demand.
Amphenol Investment Narrative Recap
To own Amphenol, you need to believe that demand for high speed, power and fiber interconnects tied to AI infrastructure, datacom, defense and industrial gear stays supportive enough to keep factories busy and pricing disciplined. The Citi conference appearance mainly reinforces that story, with management pointing to record orders and broad book to bill strength as the key short-term driver.
The biggest swing factor in the near term is how smoothly AI related IT datacom programs convert from large awards into stable shipment patterns instead of uneven quarters with pull forward demand. The main risk is that customers pause or rebalance spending while Amphenol has already committed capital and carries higher debt, which could pressure margins and cash generation.
The most relevant backdrop for this conference update is the ongoing focus on AI infrastructure across the connector and fiber ecosystem, illustrated by Corning’s multiyear fiber agreement with Verizon. That contract sits upstream in the optical chain, while Amphenol’s opportunity is in the high speed electrical, power and fiber connectivity that links compute, storage and networking gear.
For you as an investor, this pairing matters because it highlights how AI driven buildouts rely on both capacity in the ground and dense interconnect inside data centers. Progress on projects like Verizon’s broadband and AI expansion helps frame the durability of demand that Amphenol is targeting, while also underscoring that sector spending can shift quickly if large carriers or cloud customers change rollout pacing.
Amphenol Forecasts Through an AI Infrastructure Lens
For Amphenol, the AI infrastructure story comes with explicit numbers that investors can benchmark. Analysts are working off a view that the business can sustain revenue growth tied to dense connectivity inside data centers, while also leaning on defense, industrial and automotive demand to smooth out some of the cycle risk.
Those forecasts assume a yearly increase in sales of 20.5% over the next three years, with profit margins moving from 17.7% today to 21.4% by 2029. That margin shift matters because it shapes how much of the AI related demand actually drops through to profit rather than being absorbed by higher production, logistics or capital costs.
Current earnings are pegged at about US$5.1b, with consensus projections of US$10.8b by 2029 and some analysts modeling as much as US$12.0b. That implies a bit more than a doubling of earnings, so investors are effectively being asked to underwrite roughly a 2x increase in profit as AI infrastructure, high speed interconnect and broader electronic content themes play through the income statement.
Amphenol's narrative projects US$50.7b revenue and US$10.8b earnings by 2029. This requires 20.5% yearly revenue growth and roughly a 2x earnings increase from about US$5.1b today.
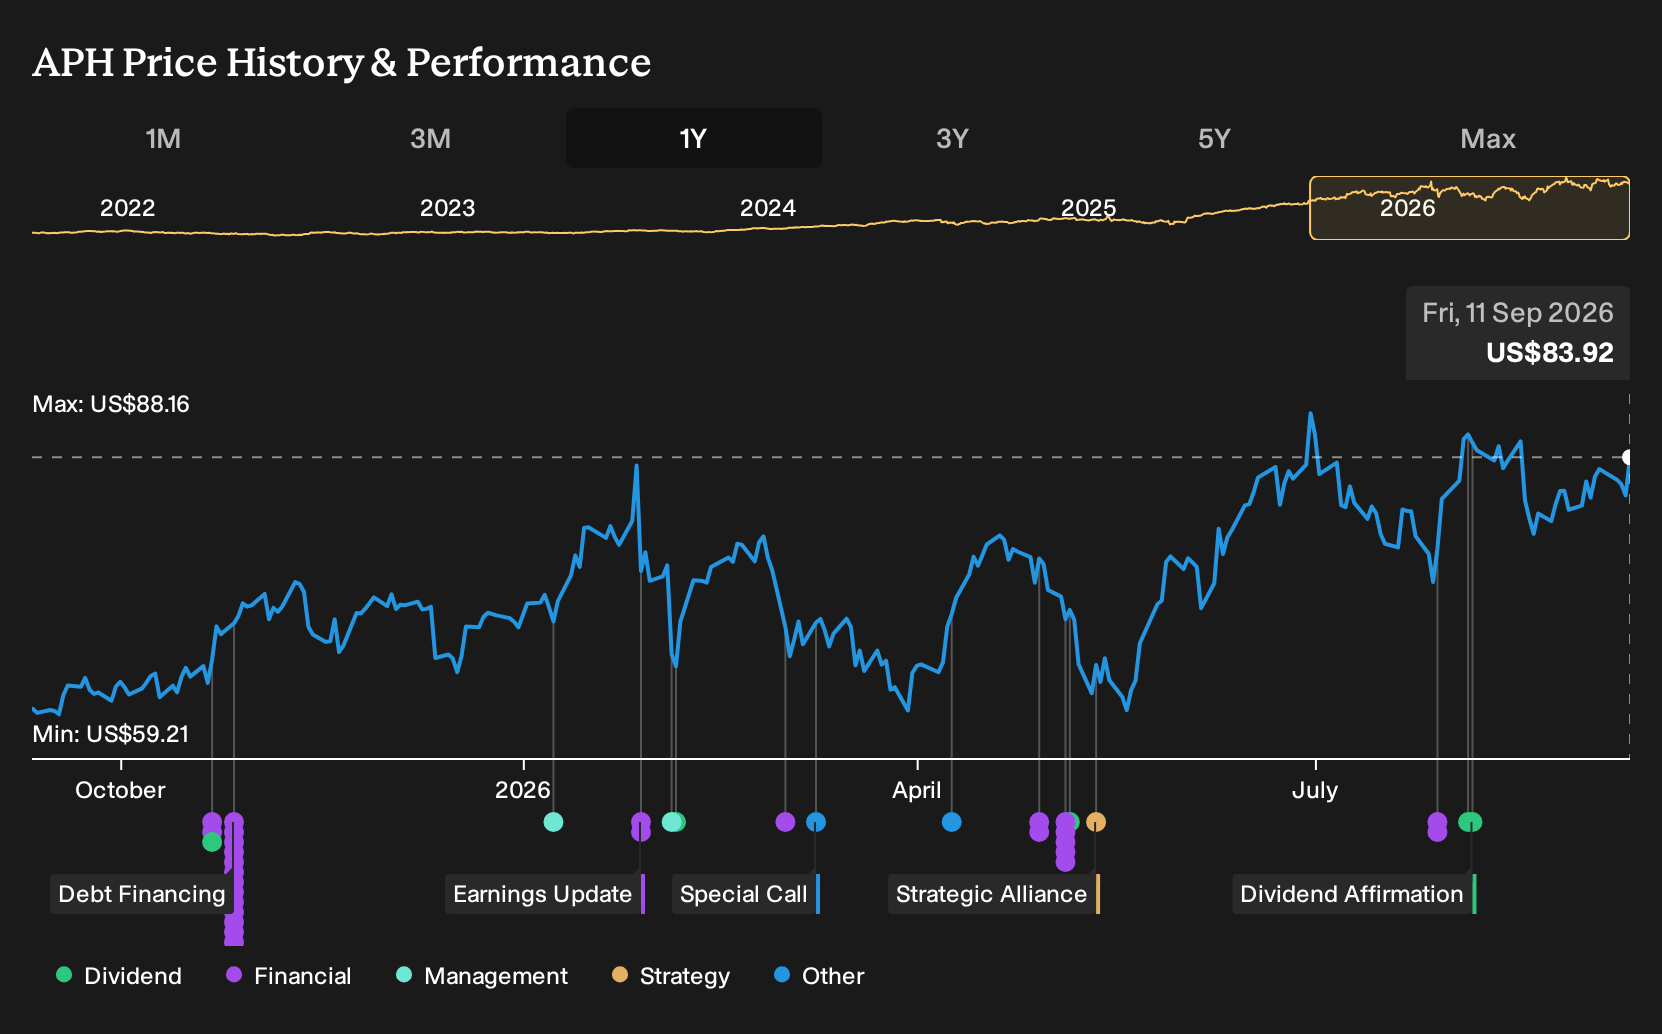
On these projections, the consensus fair value work coalesces around earnings of US$10.8b on that US$50.7b in revenue in 2029, paired with a P/E of 29.9x. Analysts are comparing that multiple to a current P/E of 39.7x for Amphenol and about 29.8x for the broader US electronic industry, so the thesis leans on strong AI and datacom demand intersecting with a gradually moderating valuation multiple.
For you as a shareholder or prospective buyer, those inputs provide a simple gut check. The AI datacenter and high speed connectivity story needs to be strong enough to justify US$50.7b in revenue, rising margins and a 29.9x P/E on 2029 earnings, rather than the higher multiple that the stock trades on today.
Uncover why Amphenol's fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view sees wireless and contactless tech slowly chipping away at demand for Amphenol’s core connectors. On that logic, the most cautious analysts were only penciling in about US$39.5b of revenue and US$7.2b of earnings by 2029, compared with higher consensus figures. That gap shows how far opinions can spread, so use this conference update as a prompt to compare several narratives against your own expectations.
Explore 6 other Amphenol fair value estimates, including one that suggests it could be worth just $87.68.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Amphenol research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Amphenol. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amphenol's overall financial health at a glance.
Looking For More Investment Ideas Beyond Amphenol?
If the Amphenol story has you thinking about how AI infrastructure, balance sheet strength and earnings quality line up across the rest of your watchlist, it can help to scan a wider field of companies with similar traits before committing fresh capital.
- If income reliability is high on your list, take a look at 6 dividend fortresses that focus on payouts backed by stronger balance sheets.
- For investors prioritizing resilience over excitement, review a curated 11 resilient stocks with low risk scores that screens for steadier financial profiles and lower risk scores.
- When you want potential upside without stretching on quality, survey a 16 high quality undiscovered gems that combines solid fundamentals with under-followed stories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com