
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Polestar (PSNY) Stock May Be Undervalued As US Sales Plans Change
Polestar Automotive Holding UK stock has dropped sharply over the past few years, yet some valuation checks still hint at potential mispricing rather than a clear verdict. With pressure on the share price and mixed signals from the broader metrics, investors are trying to work out whether the current level reflects the business outlook or an overreaction.
- Over the past 3 years the share price has declined about 90.6%, which puts Polestar firmly in the category of a heavily sold off electric vehicle stock.
- Recent updates around reduced U.S. growth ambitions and restructuring of American operations can weigh on sentiment. At the same time, a stable first half sales base and a growing contribution from the Polestar 4 model may support expectations for longer term volume stability.
- The stock carries a mixed value score of 3 out of 6, which points to a valuation picture that is neither a clear bargain nor clearly expensive on the broader set of checks.
The issue now is whether Polestar’s current market price already reflects the business risks around U.S. restrictions and softer EV demand, or if investors are still paying too much for the underlying fundamentals.
Spot potential recovery candidates beyond Polestar Automotive Holding UK by scanning 31 high quality undervalued stocks, which have been filtered for quality fundamentals and marked as out of favour by the market.Does Polestar Automotive Holding UK Look Undervalued on Sales?
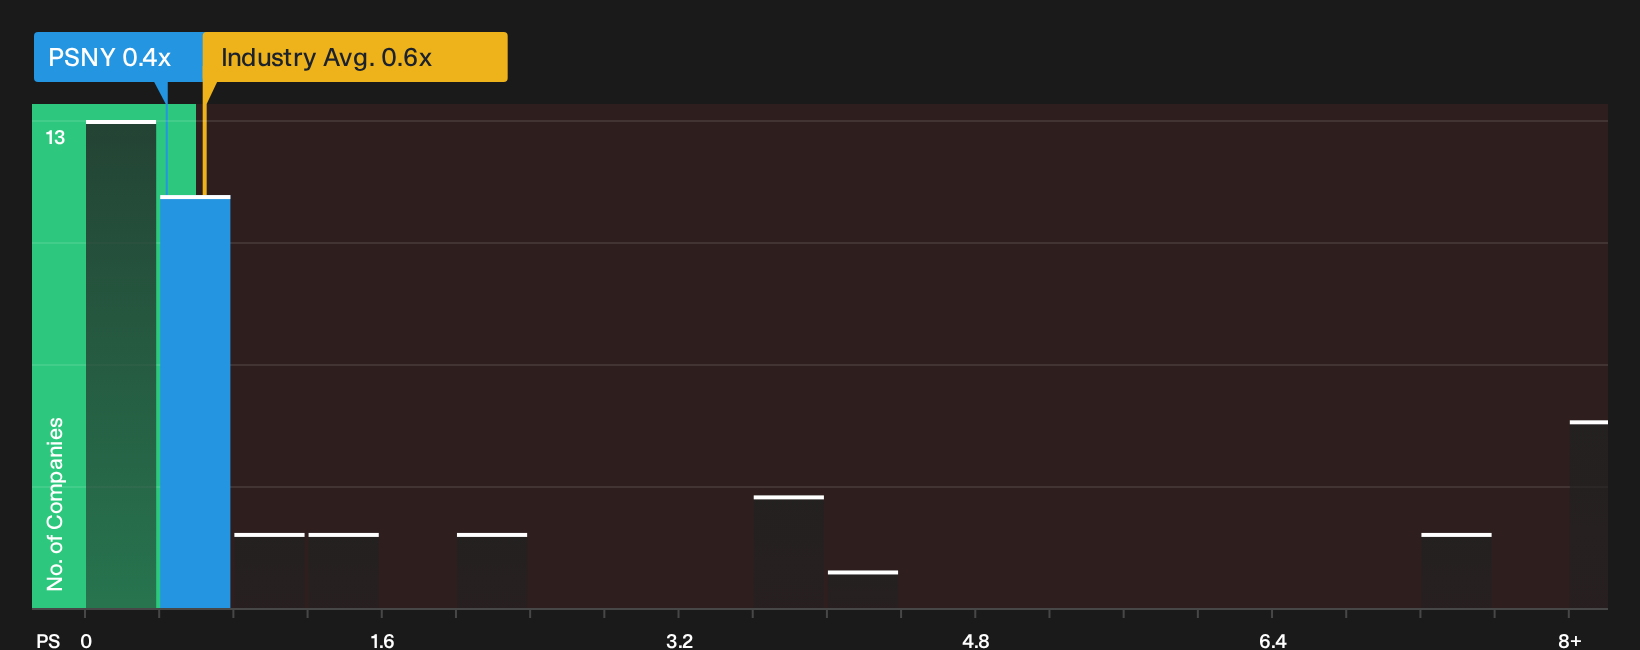
P/S fits Polestar Automotive Holding UK reasonably well because the business is still reporting losses and investors are focusing on the revenue base rather than earnings. Using this lens, the stock trades on a P/S of 0.4x, compared with an auto industry average of about 0.6x and a peer group average near 0.7x, so the market is valuing each dollar of Polestar’s sales at a lower level than many rivals.
The tailored fair P/S multiple for Polestar sits around 1.1x, which is more than double the current ratio and highlights a sizeable gap between what the screening suggests and where the shares trade. Because the recent restrictions on future U.S. model sales have affected sentiment, the low P/S level appears more like a pricing-in of those risks than a rich valuation.
On the P/S multiple alone, Polestar Automotive Holding UK currently appears undervalued relative to both its fair ratio and industry benchmarks.
See what the numbers say about this price — find out in our valuation breakdown.
The Polestar Automotive Holding UK Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Polestar Automotive Holding UK pick up where the P/S puzzle leaves off by spelling out which future growth, margin and earnings paths would need to play out for the stock to be worth materially more or less than today’s price on the Community page. Each narrative turns that into a clear, testable view on Polestar Automotive Holding UK's business so you can see how the idea holds up over time.
One of the top community narratives on Polestar Automotive Holding UK: 48% undervalued
"The company's strategy to leverage over-the-air software updates, expansion into automotive connectivity, and potential subscription-based features opens substantial high-margin, recurring revenue streams that could significantly lift earnings quality and overall profitability over time…"
Read one of the top narratives on Polestar Automotive Holding UK
Do you think there's more to the story for Polestar Automotive Holding UK? Head over to our Community to see what others are saying!
The Bottom Line
Polestar Automotive Holding UK screens as undervalued on sales based on its current P/S discount to both peers and the tailored fair multiple. That gap only matters if revenue holds up and the business can convert model launches and geographic shifts into a steadier volume and margin profile. The central question for investors is whether the discount compensates for the risks around U.S. constraints and softer EV appetite, or whether it reflects a fair precaution for those pressures. The answer rests on how confident you are that Polestar can turn its existing sales base into a more durable, profitable franchise over time.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com