
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Blackstone Mortgage Trust (BXMT) Stock Still Looks Pricey On Earnings Pressure
Blackstone Mortgage Trust has had a difficult year in the market, with the share price down 31.5% year to date, yet the current valuation checks still suggest the stock is not a clear bargain on traditional metrics.
- The year to date decline of 31.5% raises the question of whether recent weakness already reflects investor concerns about the mortgage REIT sector and credit conditions.
- Future cash flow from its loan portfolio can support the current price if credit performance holds up. However, pressure on funding costs and any rise in borrower stress may weigh on what investors are willing to pay for the shares.
- The broader valuation score, with only 1 of 6 checks screening as attractive, leans toward Blackstone Mortgage Trust looking expensive rather than like a clear value opportunity.
The issue now is whether Blackstone Mortgage Trust's current price already reflects these risks or still embeds too much optimism for a mortgage-focused lender with this recent track record.
Broaden your watchlist beyond Blackstone Mortgage Trust by scanning a curated set of resilient income plays through the 6 dividend fortresses.
Does Blackstone Mortgage Trust Look Pricey on Earnings?
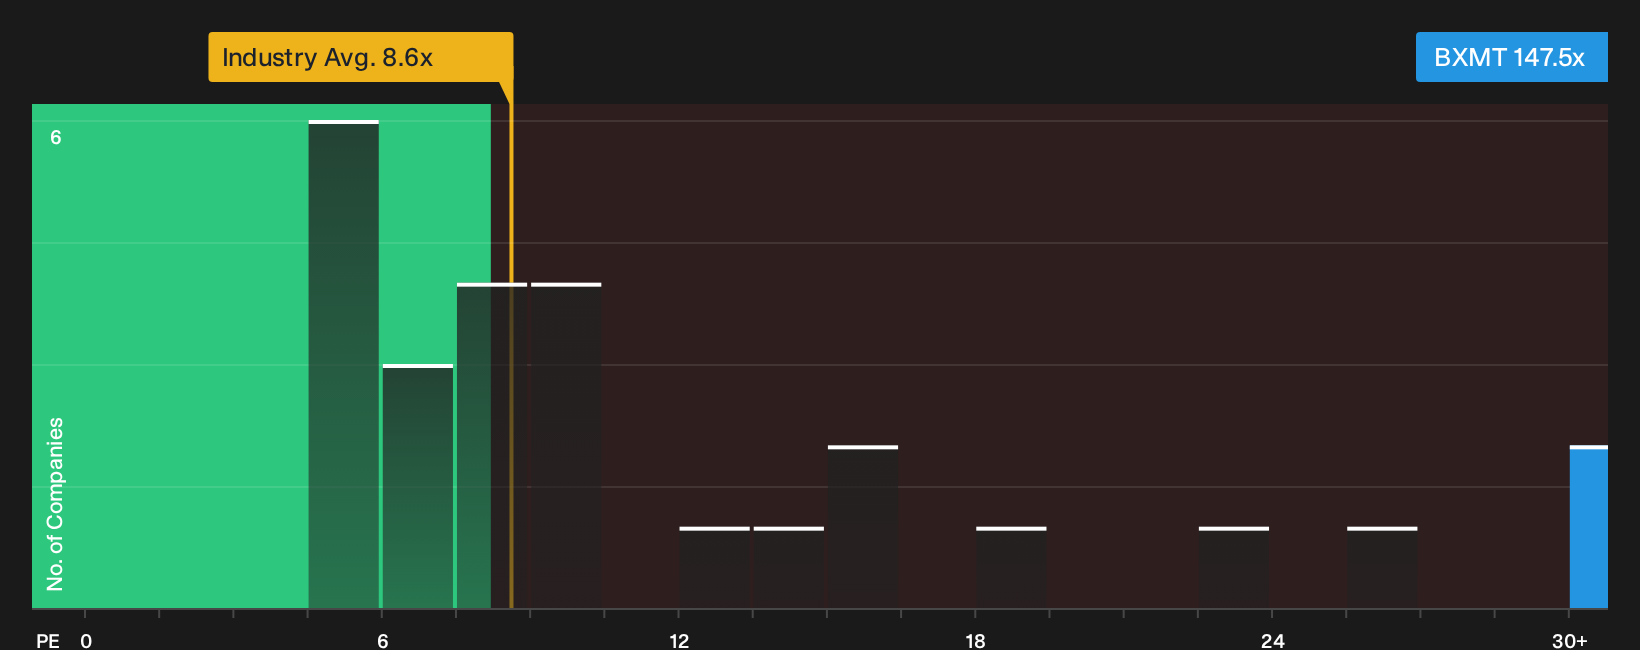
The P/E ratio is a useful yardstick for Blackstone Mortgage Trust because earnings are a key driver of how investors judge a mortgage REIT’s payout capacity. On this measure, the stock trades at about 147.5x earnings, compared with an average of roughly 8.6x for the wider Mortgage REITs industry and 14.9x for its peer group. That is a very large premium to both direct competitors and the sector backdrop.
The Fair Ratio model, which adjusts the expected P/E for Blackstone Mortgage Trust based on factors like profitability, risk and size, points to a benchmark of about 49.5x. The current multiple still sits roughly three times higher than that tailored yardstick, so the shares appear expensive even after allowing for company specific traits.
On the P/E yardstick, Blackstone Mortgage Trust currently appears overvalued relative to both sector norms and its own modelled fair multiple.
See what the numbers say about this price — find out in our valuation breakdown.
The Blackstone Mortgage Trust Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Blackstone Mortgage Trust take the high P/E puzzle above and translate it into specific future paths for earnings, growth and margins that would need to play out for the current share price to look much higher or lower. Instead of a single ratio or model output, they spell out the underlying story that number relies on so you can watch how Blackstone Mortgage Trust's actual results line up over time.
If you have a clear, number driven view on where Blackstone Mortgage Trust's growth, margins and execution go from here, add your Narrative and let other investors test it against the company’s future results.
Do you think there's more to the story for Blackstone Mortgage Trust? Head over to our Community to see what others are saying!
The Bottom Line
Blackstone Mortgage Trust currently screens as overvalued on traditional earnings multiples, even after accounting for its specific risk profile. The market is asking investors to pay a rich price for each dollar of profit, so the burden of proof now sits with future credit performance and funding costs. The key debate is simple. Either earnings power and asset quality hold up well enough to defend this premium, or the valuation needs to compress if those assumptions do not stick.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com