
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Smoke Free Expansion Just Shift Altria's (MO) Investment Narrative?
- Altria Group is responding to ongoing pressures in traditional tobacco by putting more emphasis on smoke-free products, alongside peers Philip Morris International and British American Tobacco.
- This pivot toward smoke-free offerings highlights how Altria is trying to reshape its product mix in response to volume declines and higher operating costs.
- We will look at how Altria Group's investment narrative is affected as it leans harder into smoke-free products to offset these pressures.
Scan beyond Altria Group and see how other tobacco and consumer staples players are reshaping their product mix with our handpicked 31 high quality undervalued stocks.
Altria Group Investment Narrative Recap
To own Altria Group, you need to believe the core cigarette franchise can keep generating cash while the smoke free portfolio scales enough to matter. The near term swing factor is how quickly products like on! and NJOY can win share in tightly regulated categories that still deal with illicit competition and shifting consumer budgets.
The biggest risk today sits in regulatory and competitive pressure across e vapor and oral nicotine. Illicit devices, synthetic alternatives and tariffs can all weigh on volumes and costs. The recent push toward smoke free options does not remove those threats; however, it does keep Altria Group aligned with where demand is already moving.
Recent commentary around NJOY remains one of the most relevant operational threads for this story. Shipment volume and market share have been affected by the ITC exclusion order, which directly affects a key pillar of Altria Group's reduced risk ambitions and keeps the e vapor recovery path uneven.
For investors, that means the NJOY franchise sits alongside the traditional Marlboro engine as both a major catalyst and a visible risk. Execution on product approvals, enforcement against illicit vapes and distribution reach all contribute to whether the smoke free shift can offset pressure from inflation, discount down trading and higher operating costs.
Altria Group's current narrative points to forecast revenue of US$20.9b and consensus earnings of US$9.7b by 2029, with analysts broadly assuming fairly flat top line performance and profit margins rising from 39.4% today to 46.2%. That outlook implies earnings today of US$8.0b would need to increase by about US$1.7b to reach the 2029 estimate.
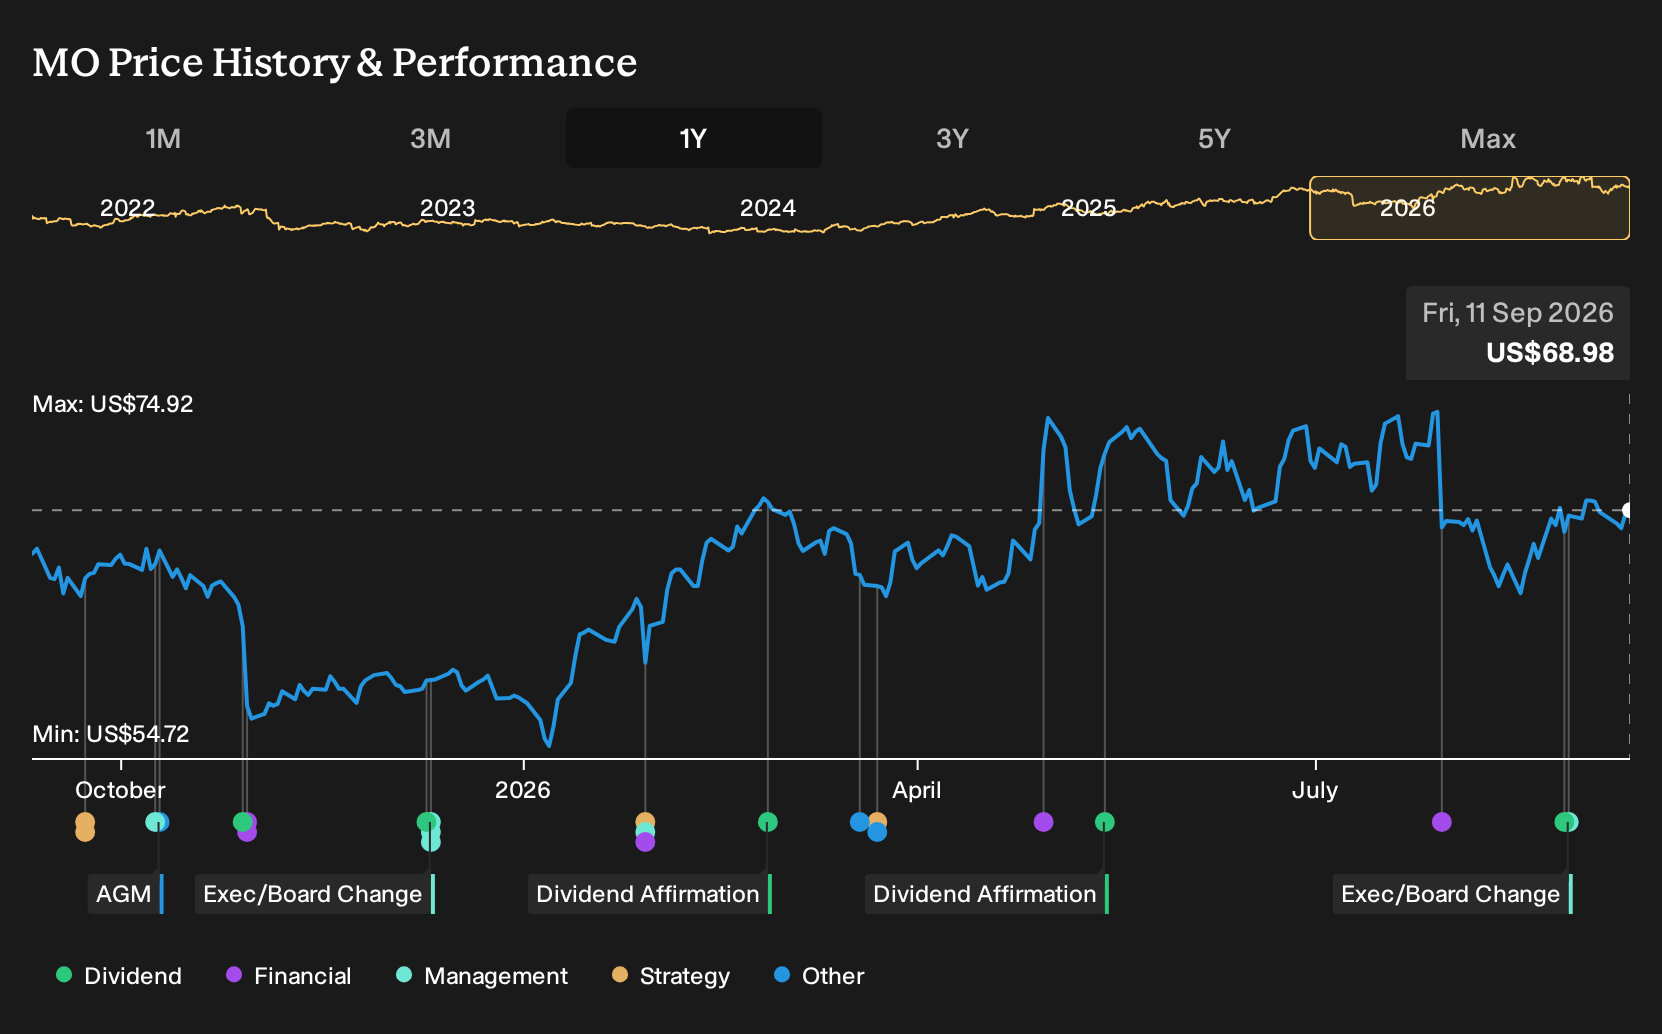
Uncover why Altria Group's fair value is essentially aligned with its current price.
Exploring Other Perspectives
One alternate read on Altria Group puts far more weight on the risk that smoke free goals slip as illicit e vapor stays above 60% of the market. The most cautious analysts were pencilling in 2029 revenue of about US$20.7b and earnings near US$9.5b, then applying a lower 12.8x P/E. These views were formed before the latest news, so sentiment and forecasts may shift as new information lands.
Explore 3 other Altria Group fair value estimates, including one that suggests as much as 8% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Altria Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Altria Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Altria Group's overall financial health at a glance.
Looking for more Altria Group style investment ideas?
If the Altria Group story has you thinking about where else dependable cash generation or future income could come from, the Simply Wall St Screener can help you widen the net without losing discipline on quality and risk.
- For investors who want potential upside without ignoring fundamentals, consider building a watchlist starting with 16 high quality undiscovered gems that already clear quality and financial strength hurdles.
- If your priority is resilience over excitement, scan through 11 resilient stocks with low risk scores that aim to keep business volatility and financial risk in check.
- Income focused investors can anchor a portfolio around 6 dividend fortresses that may help support a more reliable stream of cash returns over time.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com